Eurozone Macro Daily(Beta Mode)
Bunds Steady as ECB Hike Bets Build
Market Snapshot
| Asset | Level | Change |
|---|---|---|
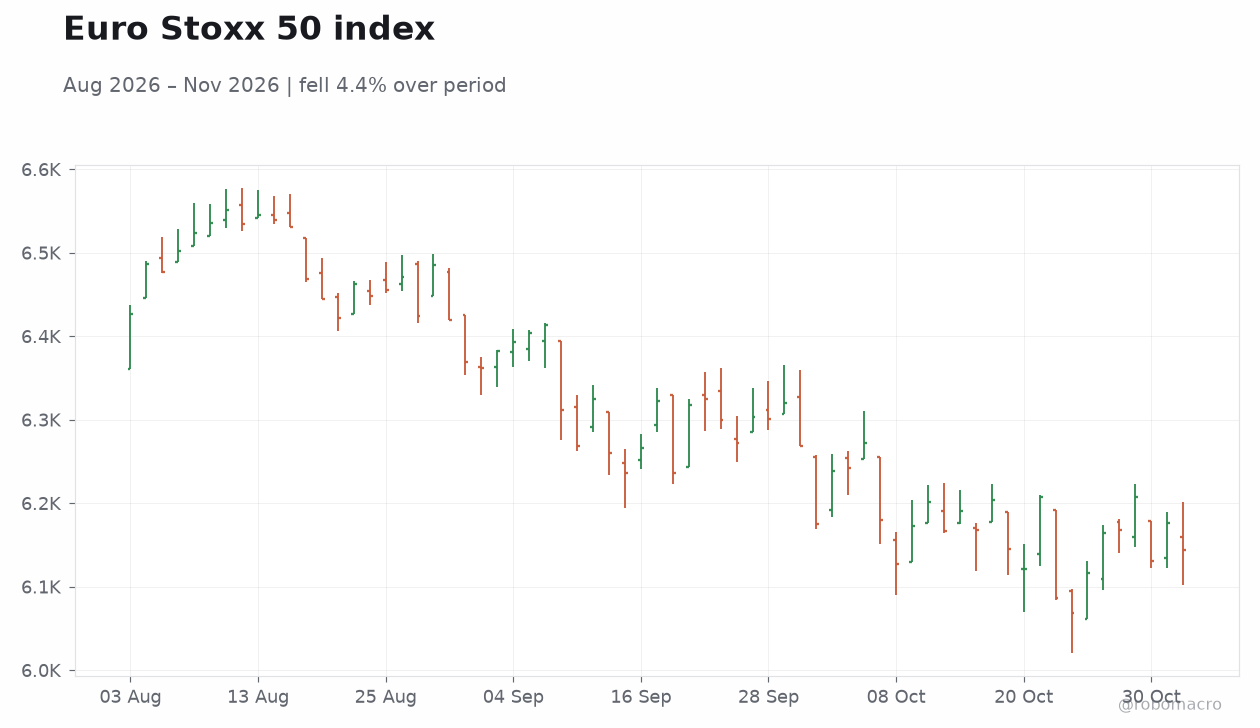
| Euro Stoxx 50 | 6,144.56 | -0.51% |
| DAX | 25,864.62 | -0.45% |
| CAC 40 | 8,020.31 | -0.34% |
| EUR/USD | 1.12 | +0.39% |
| EUR/GBP | 0.83 | +0.00% |
| EUR/JPY | 177.31 | +0.34% |
| Gold | 3,940.40 | -0.74% |
| Brent Crude | 103.60 | -1.12% |
| Bitcoin | 77,179.96 | +0.66% |
| German 2Y Bund | 3.04% | +1 bp |
| German 10Y Bund | 3.35% | +1 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Retail Sales Month-over-Month | 1.20 | 0.40 | -2 |
| Retail Sales Year-over-Year | -0.30 | - | -2.30 |
| S&P Global Manufacturing PMI Index | 51 | 50.80 | 52.20 |
| S&P Global Manufacturing PMI Index | 50.40 | 50.20 | 49.40 |
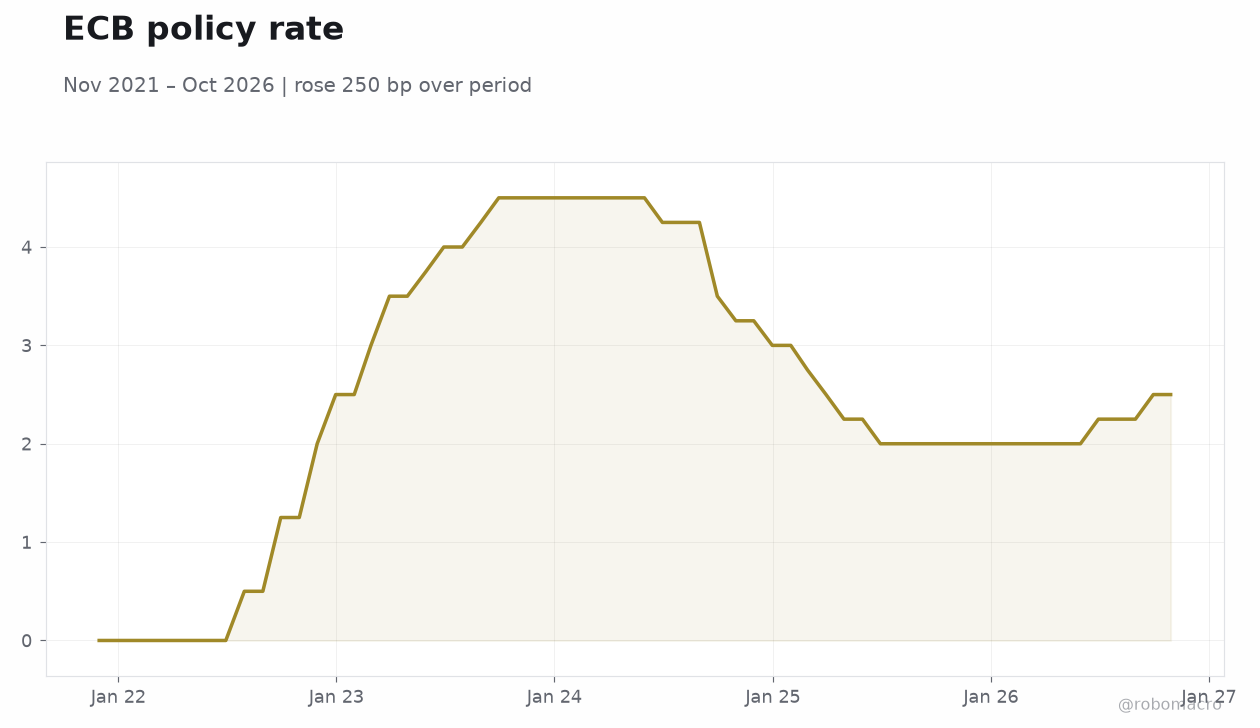 ECB policy rate | Type: macro_line | ECB policy rate %: 2.5 (2026-10-29) | Range: 0–4.5 | Trend(5pt): 0,3,4.5,2,2.5
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Inflation Rate Year-over-Year Preliminary | 3.40 | - | 00:30 |
| Unemployment Level Change | 23,587 | 25,300 | 03:00 |
| S&P Global Services PMI | 58.30 | 57.20 | 03:15 |
| S&P Global Services PMI | 51.70 | - | 03:45 |
- German retail sales plunge 2.0% m/m in September, far below the 0.4% consensus, underscoring fragile consumer demand in the bloc's largest economy.
- Eurozone manufacturing PMIs diverge sharply: Spanish PMI rises to 52.2 while Italy slips to 49.4, signaling uneven industrial momentum across member states.
- Bundesbank President Nagel joins the ECB chorus backing a December rate hike, with markets pricing further tightening as inflation heads toward 4%.
Yesterday's Recap
German retail sales contracted sharply in September, falling 2.0% m/m against consensus of 0.4% and -2.3% y/y, a stark reversal from the prior 1.2% gain and a warning on household consumption. Spain's S&P Global manufacturing PMI beat expectations at 52.2 versus 50.8 consensus, up from 51.0 previously, showing resilient Spanish industrial activity. Italy's manufacturing PMI disappointed, printing 49.4 against 50.2 expected and down from 50.4, slipping back into contraction territory.
Markets softened on the mixed data: the Euro Stoxx 50 fell 0.51% to 6,144.56, the DAX dropped 0.45% to 25,864.62, and the CAC 40 declined 0.34% to 8,020.31. German 10-year Bund yields edged up 1 bp to 3.35%, with the 2-year at 3.04%, also up 1 bp. EUR/USD strengthened 0.39% to 1.12 despite the weak German data, while Brent crude fell 1.12% to $103.60.
The Day Ahead
Dutch preliminary inflation for October is due, with the prior reading at 3.4% y/y, a key input ahead of the eurozone aggregate flash estimate. Spain releases unemployment change data, with consensus at 25,300 versus the prior 23,587 level, alongside Spanish services PMI expected at 57.2 from 58.3 previously. Italy's services PMI follows, with no consensus published against the prior 51.7 reading.
These releases will shape the services-inflation narrative the ECB is closely monitoring ahead of its December decision.
Other Economic Notes
The Bank of France is likely to cut its 2026 GDP forecast after activity unexpectedly shrank in the third quarter, Governor Moulin indicated, adding to concerns about French momentum. France's fiscal trajectory remains in focus, with commentary highlighting that Paris lacks a central bank to print money, keeping upward pressure on OAT spreads versus Bunds. Eurozone factory growth reportedly hit its highest level since 2022, though energy costs and inflation continue to surge, complicating the growth-inflation tradeoff.
The eurozone unemployment rate stands at 6.50% as of September, a historically tight labor market that underpins wage pressures.