Eurozone Macro Daily(Beta Mode)
Bunds Rally on Weak German Demand
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| Euro Stoxx 50 | 6,231.54 | -0.55% |
| DAX | 26,325.01 | -0.43% |
| CAC 40 | 8,205.37 | +0.34% |
| EUR/USD | 1.12 | -0.30% |
| EUR/GBP | 0.83 | +0.01% |
| EUR/JPY | 176.81 | -0.62% |
| Gold | 4,113.50 | +0.99% |
| Brent Crude | 98.29 | +3.88% |
| Bitcoin | 75,631.32 | -5.94% |
| German 2Y Bund | 3.01% | -4 bp |
| German 10Y Bund | 3.31% | -4 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Retail Sales Month-over-Month | 1.20 | 0.40 | -2 |
| Retail Sales Year-over-Year | -0.30 | - | -2.30 |
| S&P Global Manufacturing PMI Index | 51 | 50.80 | 52.20 |
| S&P Global Manufacturing PMI Index | 50.40 | 50.20 | 49.40 |
| Inflation Rate Year-over-Year Preliminary | 3.40 | - | 3.70 |
| Unemployment Level Change | 23,587 | 18,700 | 43,128 |
| S&P Global Services PMI | 58.30 | 57.60 | 57.20 |
| S&P Global Services PMI | 51.70 | - | 52 |
| Factory Orders Month-over-Month | -10.10 | 4.80 | 4.40 |
| Industrial Production Month-over-Month | -0.40 | 0.30 | -0.50 |
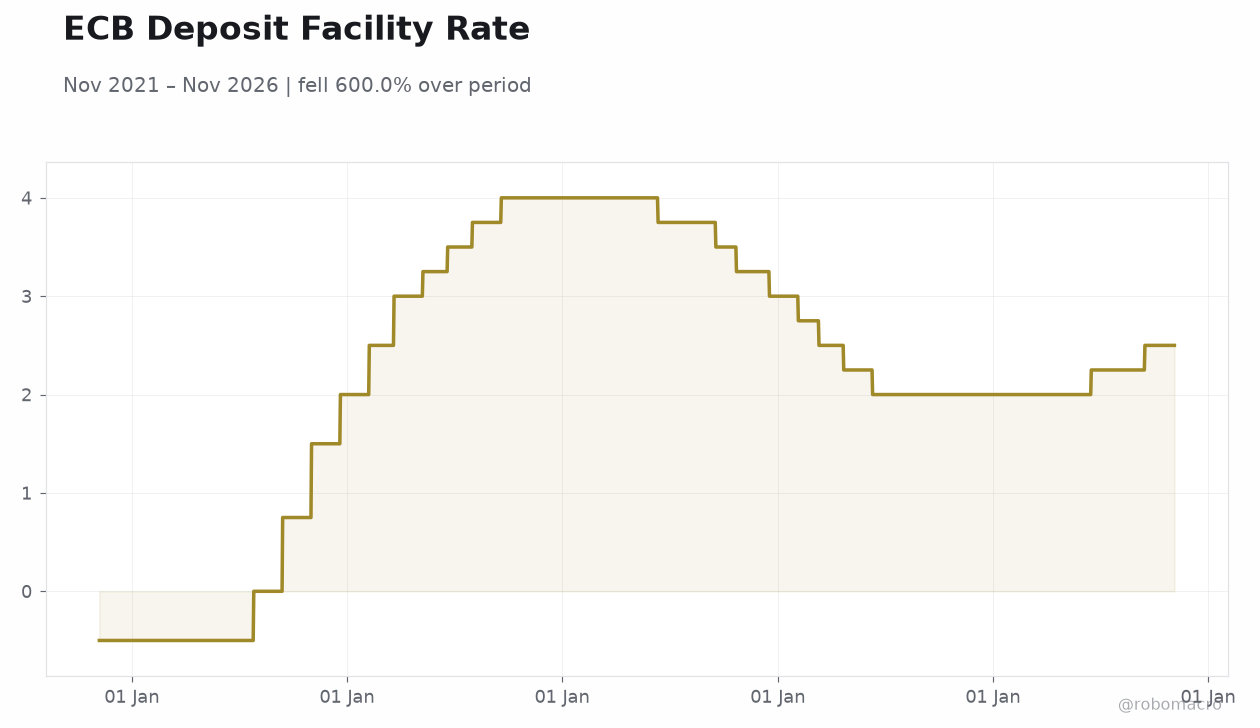 ECB Deposit Facility Rate | Type: macro_line | ECB Deposit Facility Rate: 2.5 (2026-11-05) | Range: -0.5–4 | Trend(5pt): -0.5,2,4,2,2.5
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Industrial Production Month-over-Month | 2 | 0 | 02:00 |
| Trade Balance | -6,100m | -5,800m | 02:45 |
- German retail sales plunged 2.0% m/m and 2.3% y/y, far below the 0.4% consensus, signaling consumer retrenchment in the eurozone's largest economy
- Italian manufacturing PMI slipped to 49.4, entering contraction territory, while Spanish services PMI eased to 57.2 from 58.3
- Bund yields fell 4 bp across the curve (2Y at 3.01%, 10Y at 3.31%) as oil-driven inflation fears and soft demand data weighed on rate expectations
Yesterday's Recap
German retail sales contracted sharply, falling 2.0% m/m versus consensus of 0.4% and a prior 1.2% gain, with the y/y print at -2.3%. German factory orders rebounded 4.4% m/m, undershooting the 4.8% consensus but recovering from a steep -10.1% prior decline. French industrial production disappointed at -0.5% m/m against 0.3% expected.
In southern Europe, Spanish manufacturing PMI beat at 52.2, though Spanish services PMI eased to 57.2 and unemployment rose by 43,128, well above the 18,700 consensus. Italian manufacturing PMI fell to 49.4, slipping into contraction, while Italian services PMI held at 52.0 and retail sales rose just 0.1% m/m. Dutch preliminary inflation accelerated to 3.7% y/y from 3.4%.
Markets reflected the soft demand backdrop: the Euro Stoxx 50 fell 0.55%, the DAX lost 0.43%, and EUR/USD slipped 0.30% to 1.12, while Bunds rallied.
The Day Ahead
German industrial production is due at 02:00 ET, with consensus at 0.0% m/m following a 2.0% prior gain — a soft print would reinforce the narrative of German industrial stagnation. France releases its trade balance at 02:45 ET, with consensus at -€5.8bn versus a prior -€6.1bn deficit. No major ECB speakers or Governing Council events are scheduled, leaving markets to digest the week's data flow.
Attention will increasingly turn to the 17 December ECB meeting, the final decision of the year, where staff projections will be updated. Bund price action and EUR crosses will likely track oil headlines given the energy-inflation nexus flagged by strategists.
Other Economic Notes
The divergence within the eurozone is widening: Spain's services sector remains robust while Italy's manufacturing base contracts and Germany's consumer falters. Dutch inflation at 3.7% y/y underscores persistent price pressures in core economies even as demand softens. Eurozone producer prices are rising at their fastest pace since early 2023, per WirtschaftsWoche, complicating the ECB's disinflation narrative.
↓ p.2