Eurozone Macro Daily(Beta Mode)
Bunds Steady as ECB Succession Race Heats Up
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| Euro Stoxx 50 | 6,327.87 | +0.59% |
| DAX | 26,347.45 | +0.31% |
| CAC 40 | 8,278.59 | +0.55% |
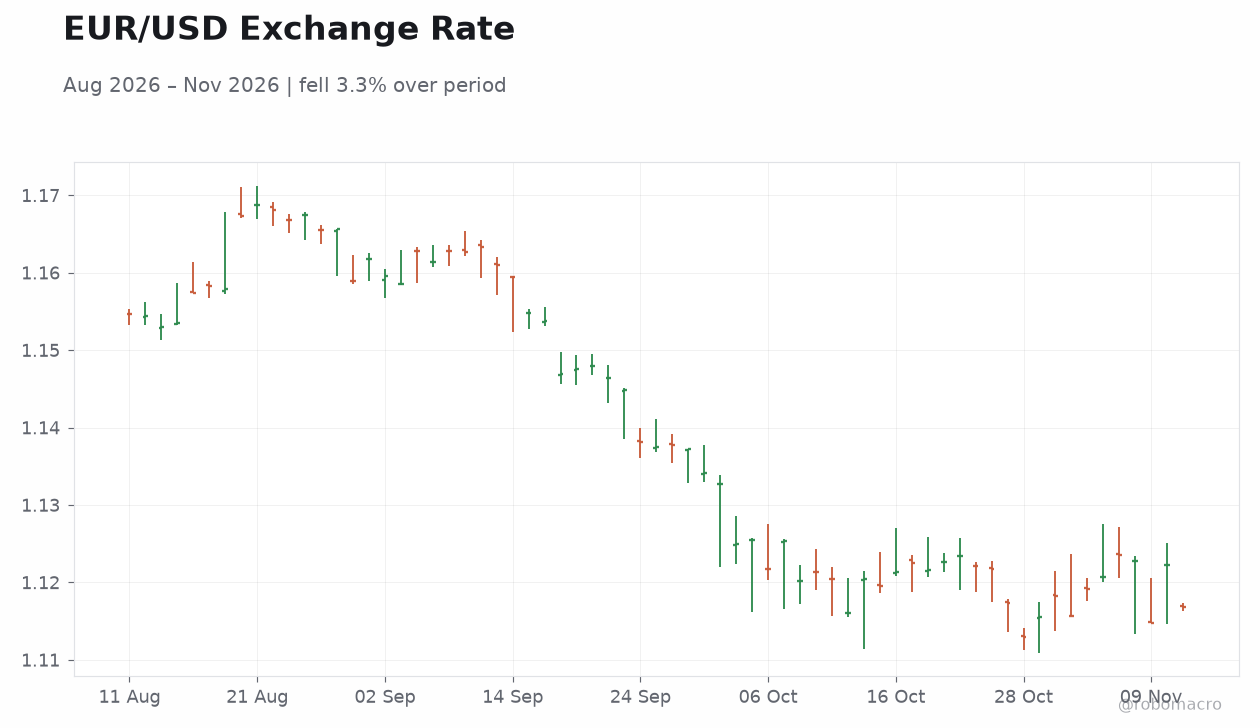
| EUR/USD | 1.12 | -0.47% |
| EUR/GBP | 0.84 | +0.19% |
| EUR/JPY | 177.26 | -0.02% |
| Gold | 4,030.20 | -2.05% |
| Brent Crude | 91.49 | -1.17% |
| Bitcoin | 73,604.51 | -2.15% |
| German 2Y Bund | 3.01% | +2 bp |
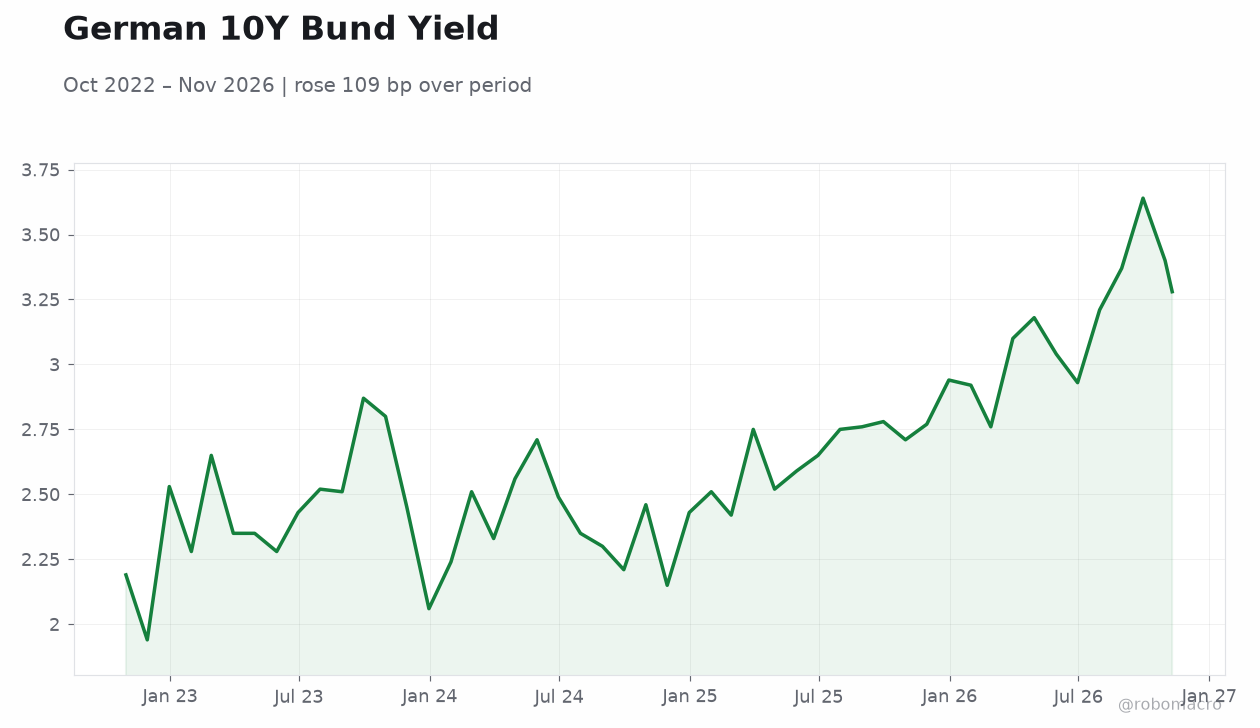
| German 10Y Bund | 3.28% | -2 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Trade Balance | 17,800m | 19,200m | 15,600m |
| Exports Month-over-Month | -0.40 | - | 2 |
| Headline Unemployment Rate | 8.30 | 8.40 | 8.20 |
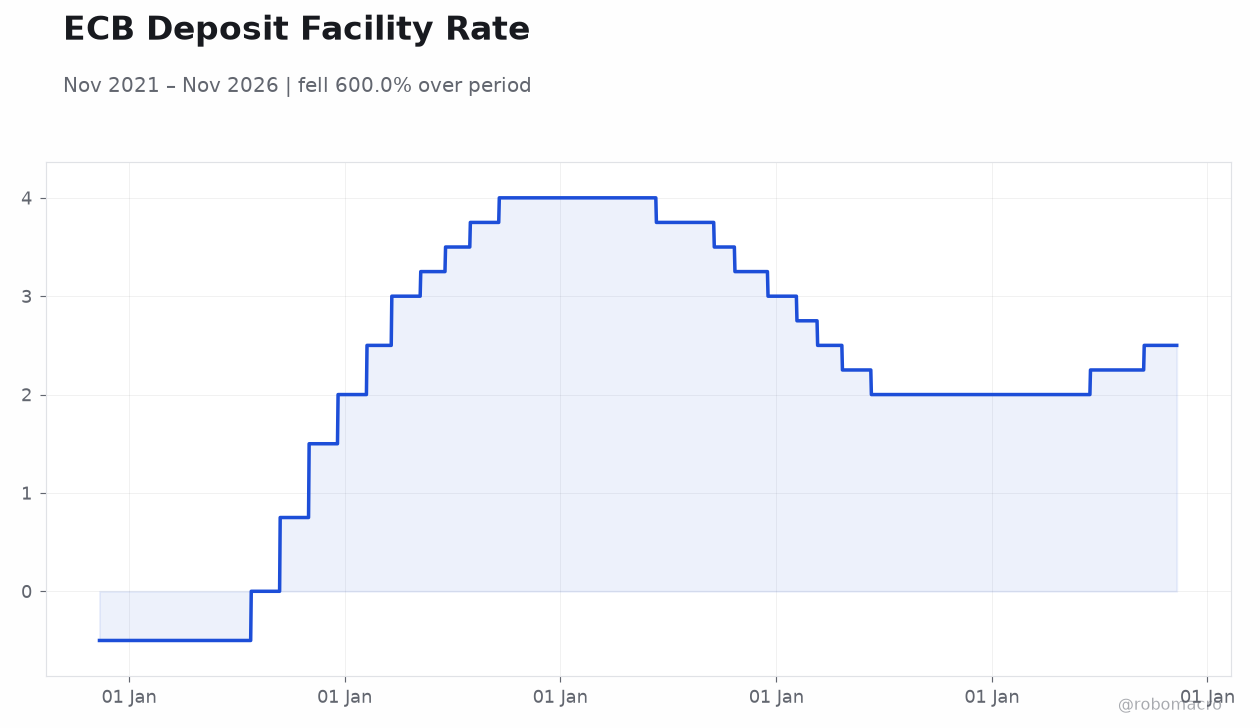
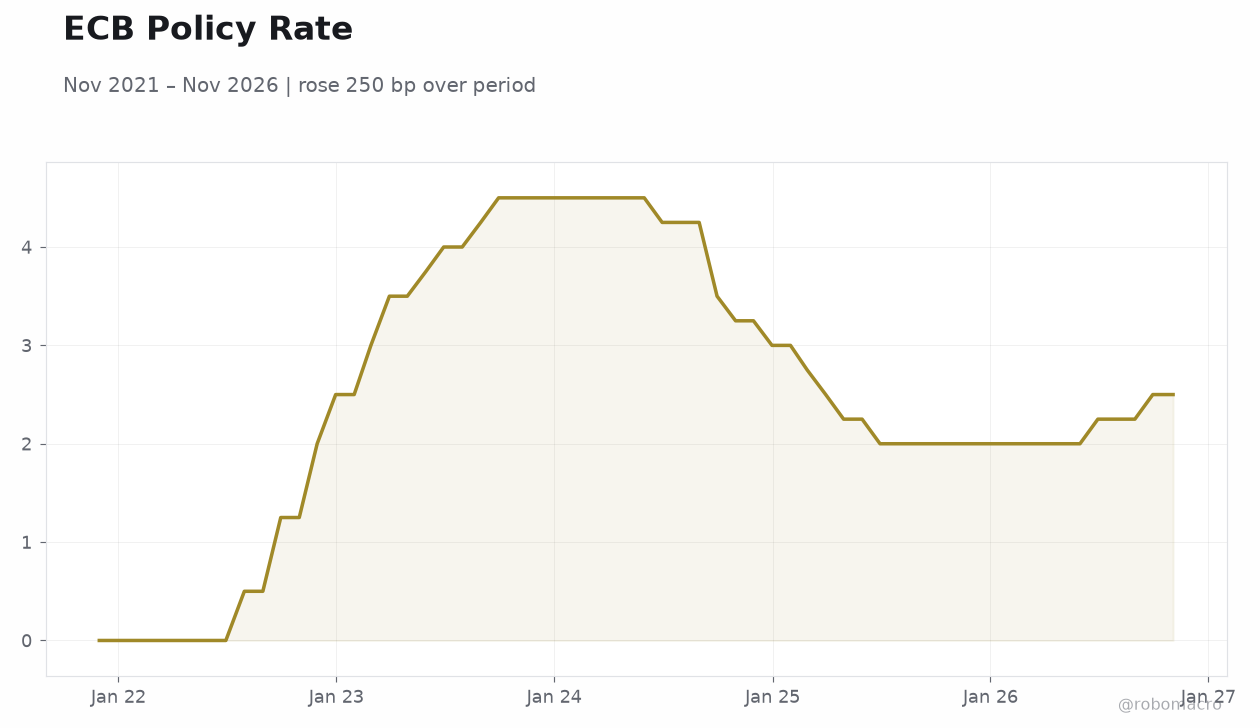 ECB Policy Rate | Type: macro_line | Policy Rate %: 2.5 (2026-11-03) | Range: 0–4.5 | Trend(5pt): 0,3,4.5,2,2.5
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Industrial Production Month-over-Month | -1.30 | 1 | 04:00 |
- German trade surplus narrowed sharply to €15.6bn in September, well below the €19.2bn consensus, as exports rose 2.0% m/m but imports outpaced.
- French unemployment unexpectedly fell to 8.2% versus 8.4% expected, bucking the softening labour-market narrative.
- ECB leadership succession dominates the agenda, with France positioning for the chief economist role and a two-horse race to succeed Lagarde.
Yesterday's Recap
German September trade data disappointed, with the surplus contracting to €15.6bn against a €19.2bn consensus and prior €17.8bn, as exports rebounded 2.0% m/m but import growth ran hotter. In France, the headline unemployment rate unexpectedly eased to 8.2% from 8.3%, undershooting the 8.4% consensus and signalling unexpected labour-market resilience. Markets were mixed: the Euro Stoxx 50 added 0.59% and the CAC 40 rose 0.55%, while the DAX lagged at +0.31%.
Rates diverged along the curve, with the German 2-year yield up 2 bp to 3.01% and the 10-year down 2 bp to 3.28%, a modest steepening bias. EUR/USD slipped 0.47% to 1.12, pressured by the softer German trade print and a firmer dollar backdrop. Gold fell 2.05% to $4,030/oz and Brent eased 1.17% to $91.49 as risk appetite rotated into equities.
The Day Ahead
The calendar is thin, with only Italian industrial production m/m due at 04:00 ET, where consensus looks for a 1.0% rebound following the prior -1.3% contraction. That print will be scrutinised as a bellwether for the Italian manufacturing cycle and broader euro-area industrial momentum heading into year-end. No other tier-one Eurozone releases are scheduled, leaving markets to trade off ECB succession headlines and global risk sentiment.
Bund and BTP spreads will likely react to any Italian production surprise, with peripheral duration sensitive to growth disappointment. Attention increasingly rotates toward the December ECB meeting and the intensifying race to fill senior ECB posts.
Other Economic Notes
Corporate restructuring is accelerating, with Vodafone cutting a further 2,300 jobs in Germany as part of a broader 3,000-role reduction across the UK and Europe, underscoring pressure on telecom margins. UniCredit is set to secure unconditional EU antitrust approval for its acquisition of Commerzbank, a landmark consolidation step for German banking. Berlin is launching a "House of Germany" presence in Davos to attract foreign investment, signalling official concern about the country's competitiveness.
Chancellor Merz has reportedly threatened to veto the EU's next seven-year budget unless all member states contribute to Ukraine financing, adding fiscal-politics risk to the outlook.