Eurozone Macro Daily(Beta Mode)
Bunds Sell Off as German Data Surprises
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| German 2Y Bund | 3.08% | +7 bp |
| German 10Y Bund | 3.37% | +6 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Trade Balance | 17,800m | 19,200m | 15,600m |
| Exports Month-over-Month | -0.40 | - | 2 |
| Headline Unemployment Rate | 8.30 | 8.40 | 8.20 |
| Industrial Production Month-over-Month | -1.20 | 0.70 | 1.20 |
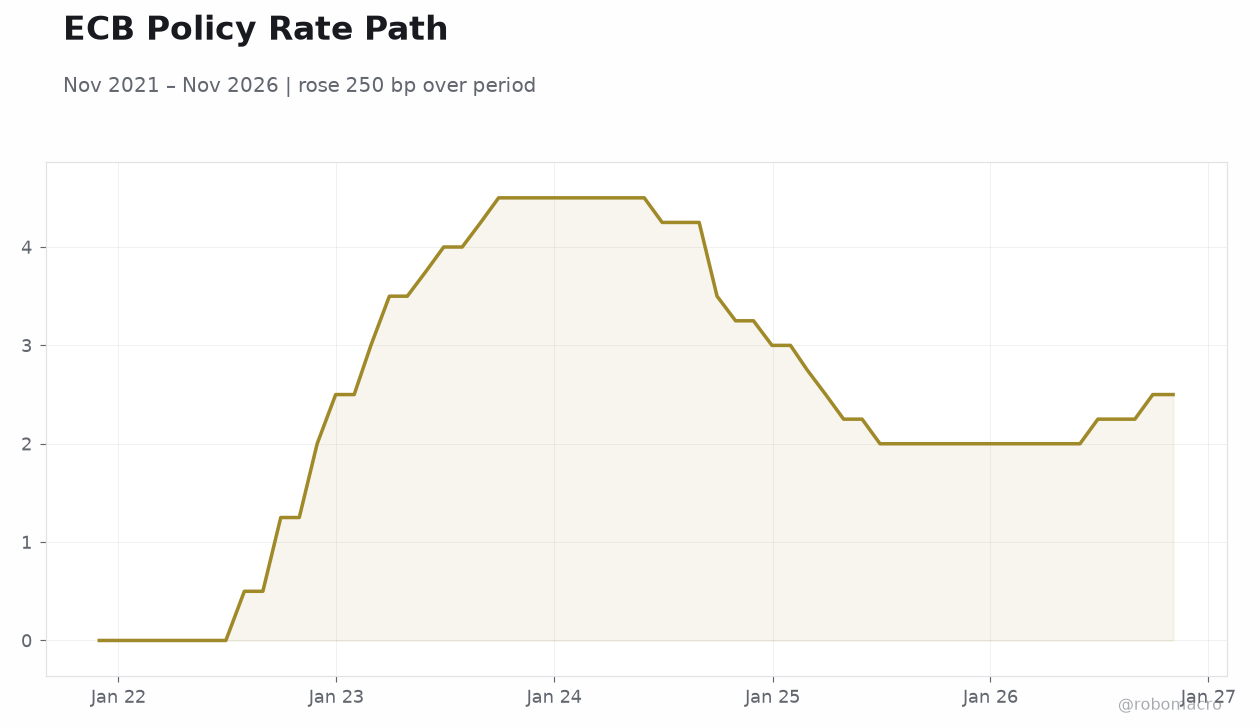 ECB Policy Rate Path | Type: macro_line | Policy Rate %: 2.5 (2026-11-03) | Range: 0–4.5 | Trend(5pt): 0,3,4.5,2,2.5
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Friday (2026-11-13) | |||
| Wholesale Prices Month-over-Month | 1.90 | 0.40 | 02:00 |
| Wholesale Prices Year-over-Year | 8.70 | - | 02:00 |
| Trade Balance | 1,773m | 1,850m | 04:00 |
- German exports rebounded 2.0% m/m in September while the trade surplus narrowed to €15.6bn, missing the €19.2bn consensus as import growth outpaced shipments.
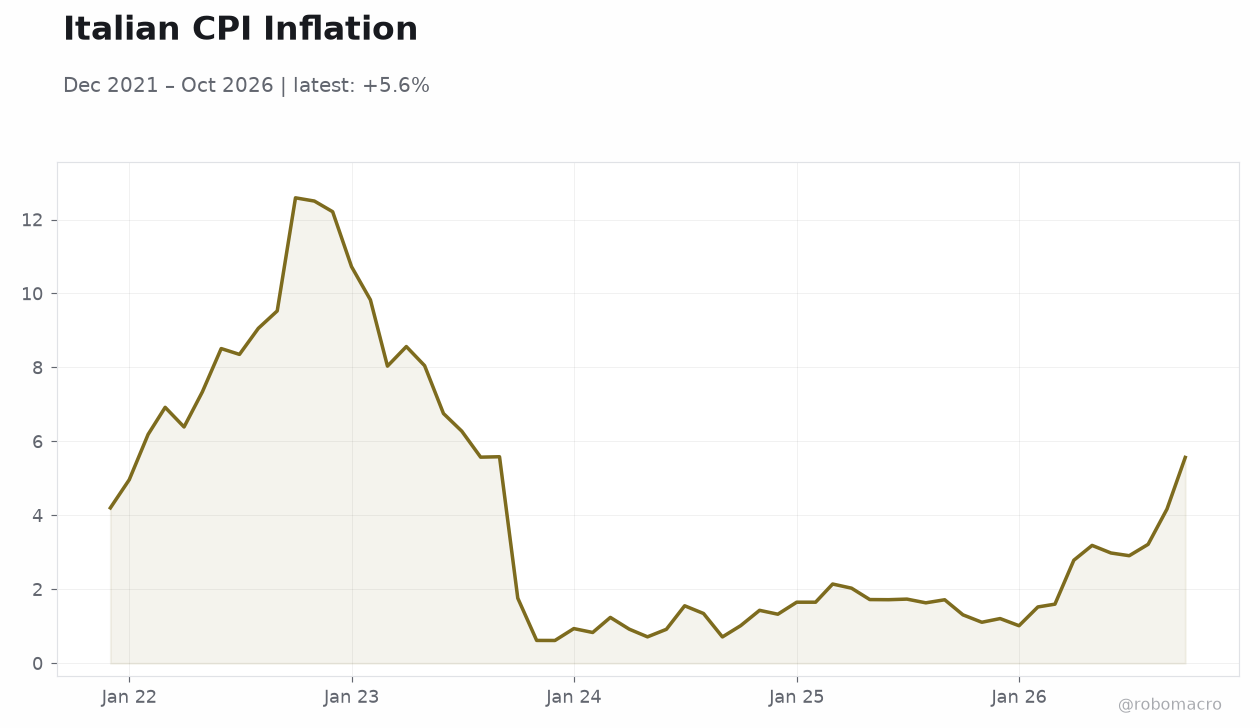
- Italian industrial production jumped 1.2% m/m in September, beating the 0.7% consensus and reversing the prior 1.2% decline, while French headline unemployment unexpectedly fell to 8.2%.
- Bund yields extended their climb, with the 2-year up 7 bp to 3.08% and the 10-year up 6 bp to 3.37%, as markets digest the ECB's September hike to a 2.50% deposit rate.
Yesterday's Recap
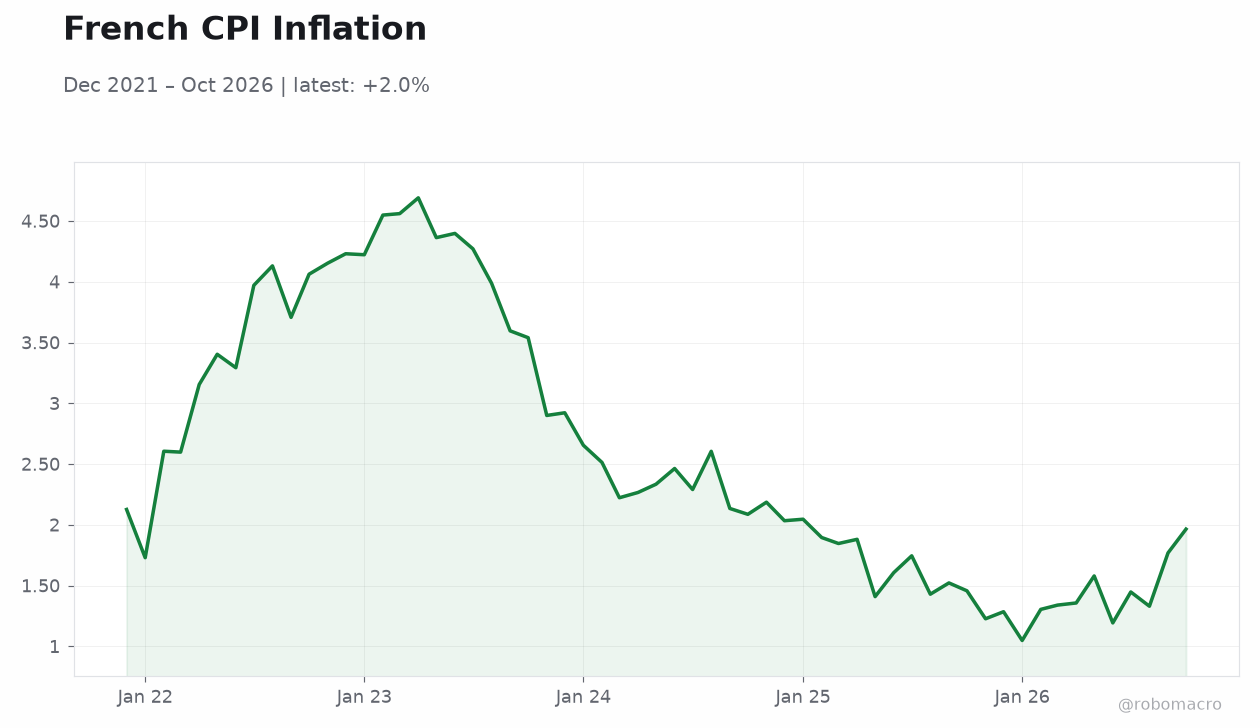
German trade data for September disappointed on the headline, with the surplus at €15.6bn versus a €19.2bn consensus, though exports rose 2.0% m/m after a 0.4% contraction the prior month — the import side drove the shortfall. Italian industrial production for September surprised strongly to the upside at +1.2% m/m against a 0.7% consensus, reversing the previous month's 1.2% drop and offering a rare positive signal from Rome's manufacturing base. French headline unemployment came in at 8.2%, below both the 8.4% consensus and the prior 8.3% reading, a modest but welcome improvement in the euro area's second-largest economy.
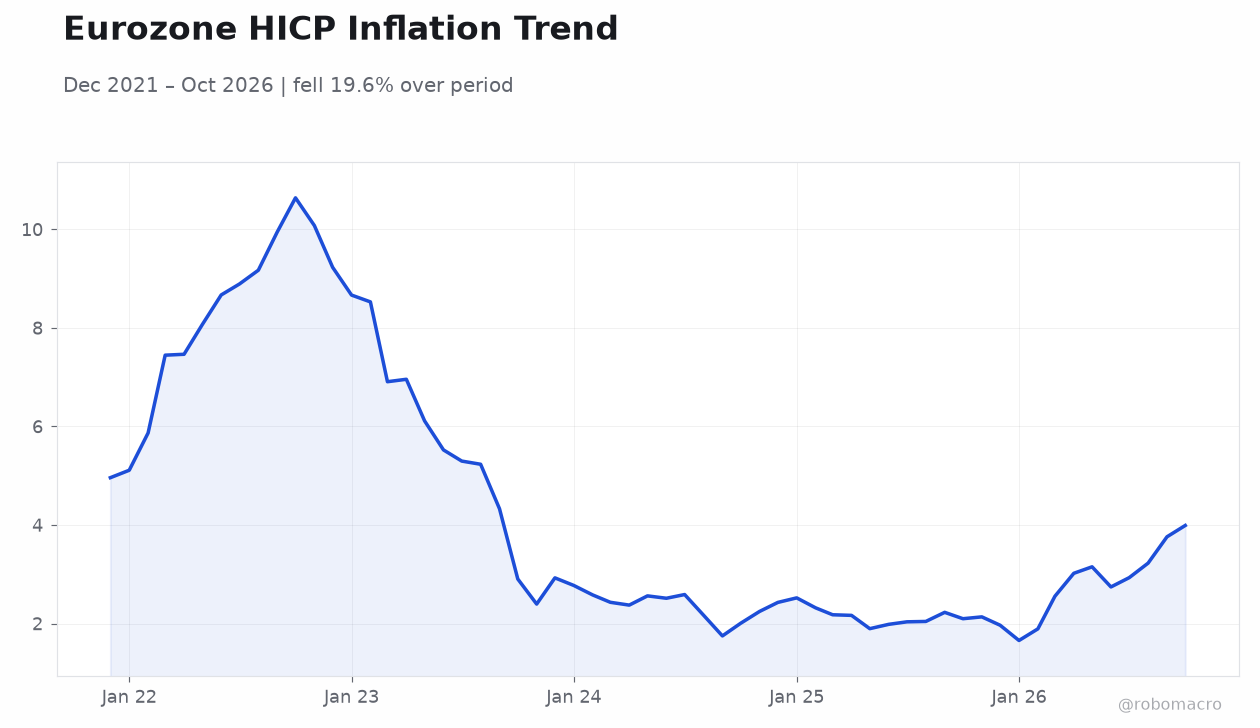
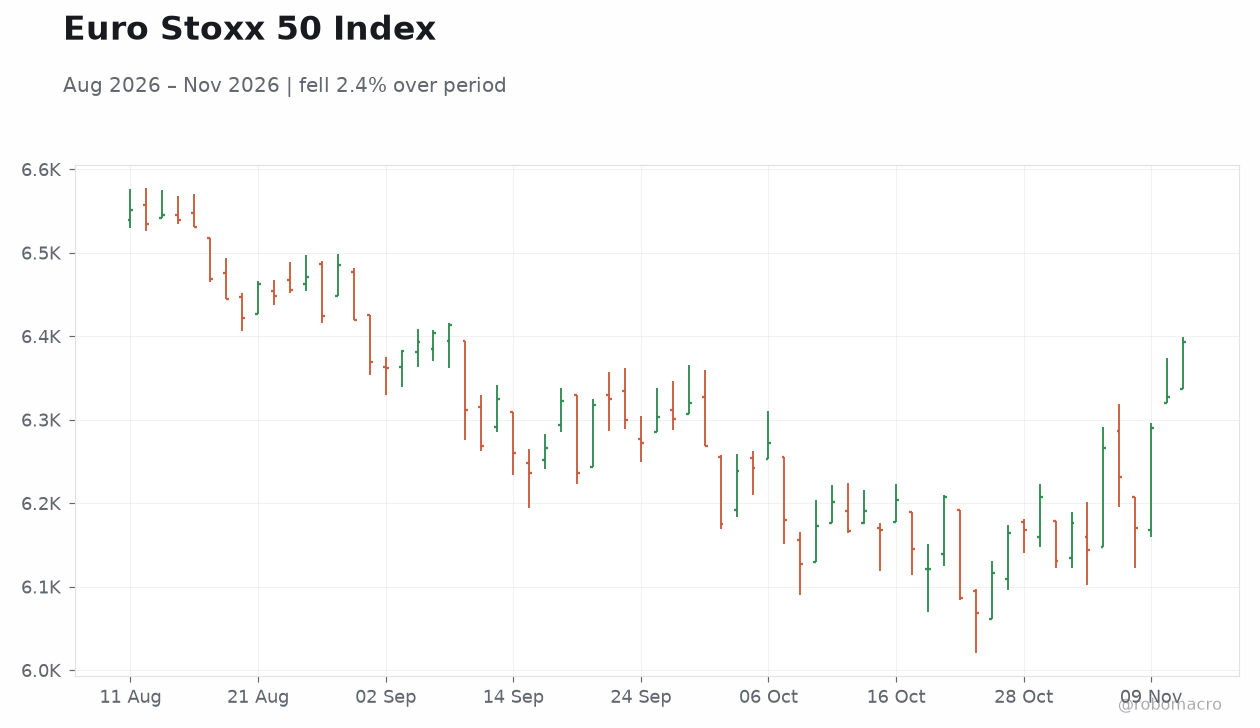
Markets focused squarely on the rates complex: the German 2-year yield rose 7 bp to 3.08% and the 10-year added 6 bp to 3.37%, steepening modestly as the curve repriced. The move reflects persistent inflation pressure — euro area CPI stands at 4.00% — and the ECB's September decision to hike the deposit rate by 25 bp to 2.50%. Equities and EUR crosses took a back seat to the bond sell-off, with the FT noting a widening divide in eurozone bond markets that has singled out France and Belgium.
The Day Ahead
The calendar is light, with Friday's German wholesale price data for October the main item: m/m prices are seen at 0.4% following a 1.9% prior, while the y/y series carries an 8.7% prior with no consensus published. Italian trade balance data for September is also due, with a €1.85bn consensus against a €1.773bn prior. No tier-one euro area releases land today, so flows will be driven by positioning into Friday's prints and by cross-market moves.
Attention increasingly turns to the December 17 ECB meeting, the first since the September hike, where staff projections will be updated. With the deposit rate at 2.50% and CPI at 4.00%, the burden of proof remains on the doves to justify any reversal.
Other Economic Notes
The Bundesbank chief's comments that German growth will accelerate in Q4, driven by industry recovery and public spending, echo the more constructive tone from the government's economic advisers, who more than doubled their 2026 growth forecast. ↓ p.2