Eurozone Macro Daily(Beta Mode)
Bunds Firm as ECB Succession Race Heats Up
Market Snapshot
| Asset | Level | Change |
|---|---|---|
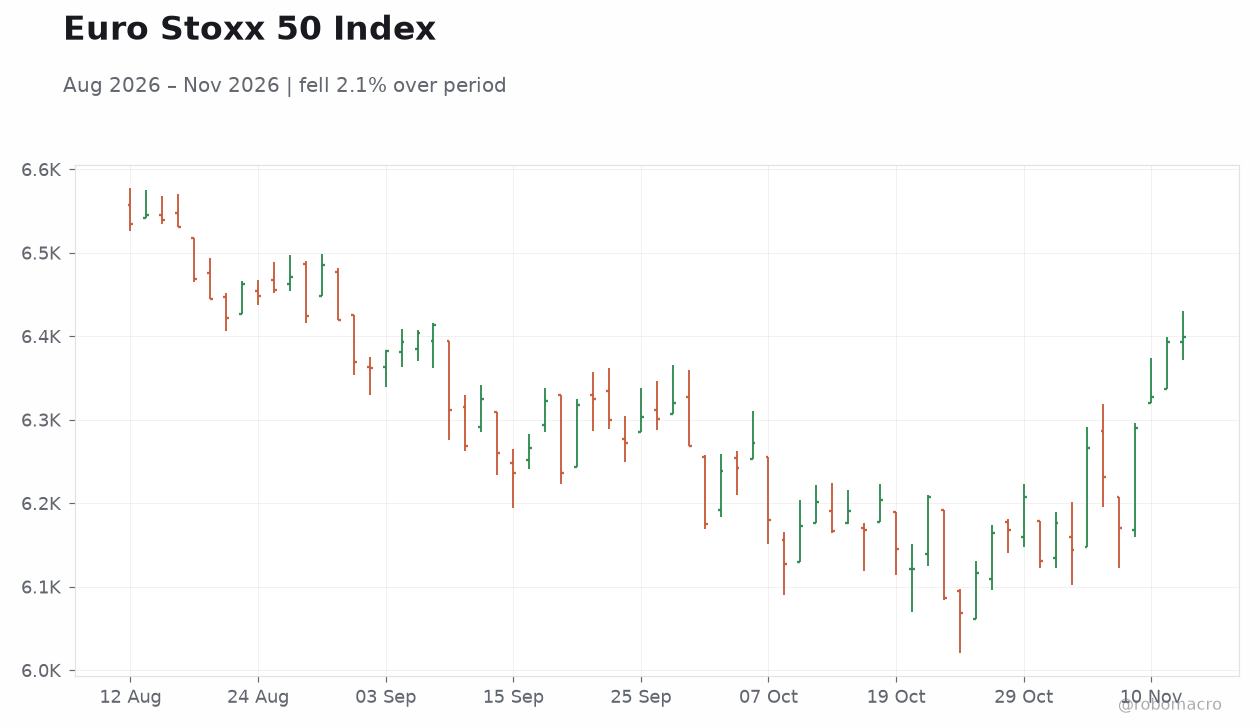
| Euro Stoxx 50 | 6,398.98 | +0.09% |
| DAX | 26,771.88 | +0.41% |
| CAC 40 | 8,361.36 | +0.34% |
| EUR/USD | 1.11 | -0.28% |
| EUR/GBP | 0.84 | +0.03% |
| EUR/JPY | 176.89 | -0.19% |
| Gold | 3,885.30 | -2.88% |
| Brent Crude | 95.82 | +3.30% |
| Bitcoin | 68,434.73 | -7.48% |
| German 2Y Bund | 3.09% | +1 bp |
| German 10Y Bund | 3.36% | -1 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Trade Balance | 17,800m | 19,200m | 15,600m |
| Exports Month-over-Month | -0.40 | - | 2 |
| Headline Unemployment Rate | 8.30 | 8.40 | 8.20 |
| Industrial Production Month-over-Month | -1.20 | 0.70 | 1.20 |
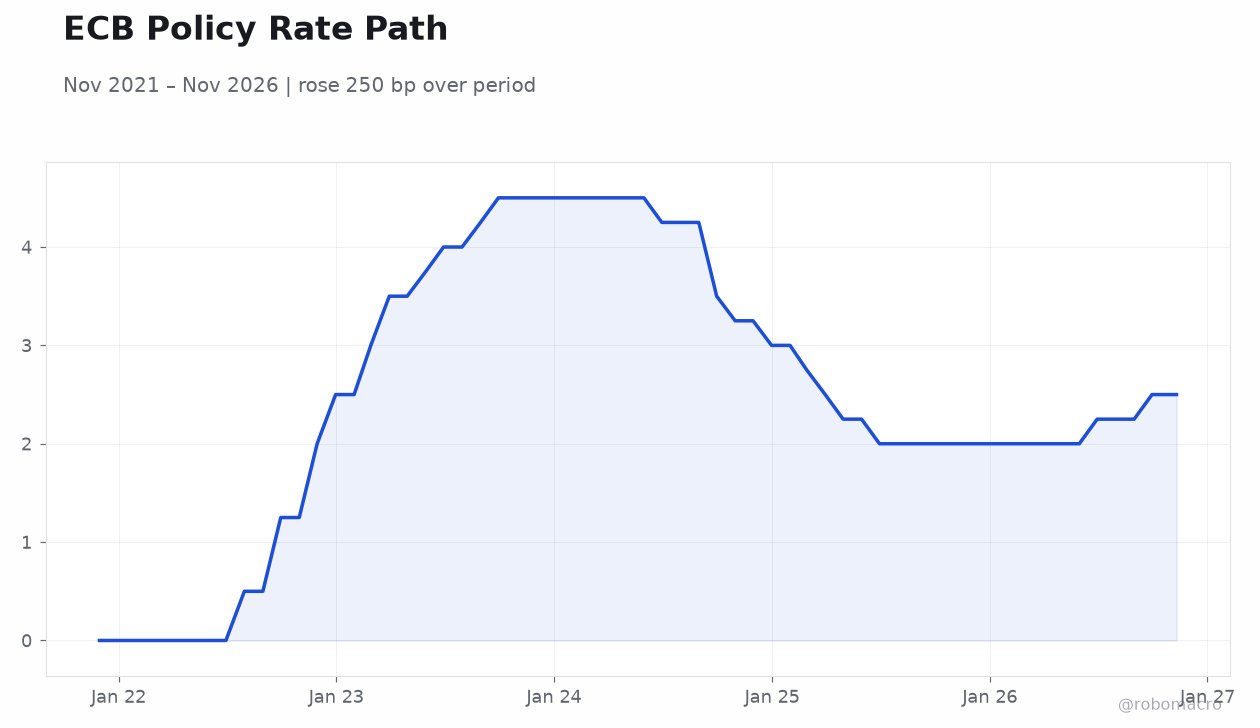
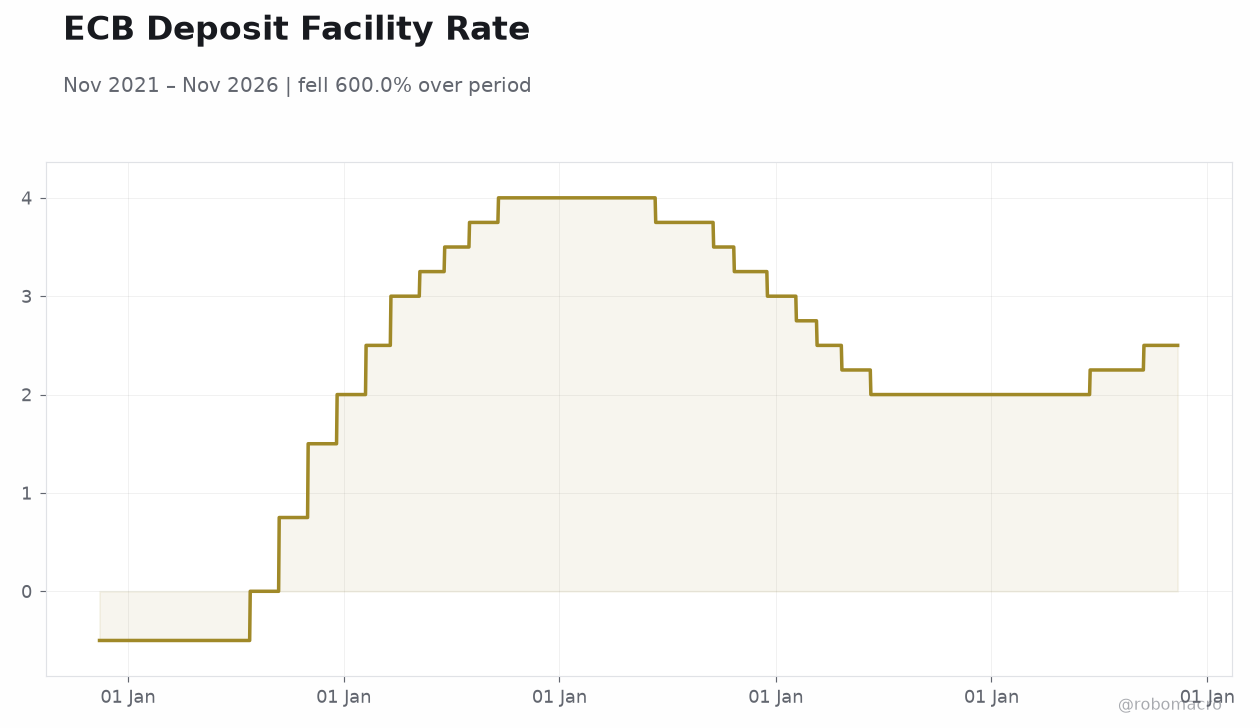 ECB Deposit Facility Rate | Type: macro_line | ECB Deposit Facility Rate: 2.5 (2026-11-12) | Range: -0.5–4 | Trend(5pt): -0.5,2.5,4,2,2.5
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Wholesale Prices Month-over-Month | 1.90 | 0.40 | 02:00 |
| Wholesale Prices Year-over-Year | 8.70 | - | 02:00 |
| Trade Balance | 1,773m | 1,850m | 04:00 |
- German trade surplus narrowed to €15.6bn in September, well below the €19.2bn consensus, as exports rose 2.0% m/m but imports outpaced.
- French headline unemployment fell to 8.2%, beating the 8.4% consensus; Italian industrial production rebounded 1.2% m/m in September.
- France has signaled backing for Spain's Pablo Hernández de Cos to succeed Lagarde at the ECB, with Paris and Berlin eyeing a package deal on central bank leadership.
Yesterday's Recap
German September trade data disappointed, with the trade balance at €15.6bn versus €19.2bn expected, despite exports rising 2.0% m/m. French headline unemployment printed at 8.2%, below the 8.4% consensus and down from 8.3% previously. Italian industrial production rebounded 1.2% m/m in September, beating the 0.7% consensus after a 1.2% decline the prior month.
Markets were mixed: the DAX rose 0.41% and the CAC 40 added 0.34%, while the Euro Stoxx 50 was roughly flat at +0.09%. EUR/USD slipped 0.28% to 1.11, and the German 10-year Bund yield eased 1 bp to 3.36% while the 2-year edged up 1 bp to 3.09%. Gold fell 2.88% and Brent crude jumped 3.30% to $95.82.
The Day Ahead
Germany releases October wholesale prices at 02:00 ET, with month-over-month consensus at 0.4% following a 1.9% prior reading; the year-over-year series last printed 8.7%. Italy publishes its September trade balance at 04:00 ET, with consensus at €1.85bn versus €1.773bn previously. The calendar is otherwise light, with no Eurozone-wide releases scheduled and nothing on the docket for tomorrow.
Attention will therefore rotate toward ECB succession headlines and any Governing Council commentary ahead of the December 17 meeting.
Other Economic Notes
The Bundesbank warned that financial stability risks in Germany remain elevated amid geopolitical tensions and structural challenges, a theme likely to resonate as the bloc confronts weak external demand. Belgium is emerging as a debt flashpoint, with observers questioning whether France's budget-policy paralysis is spilling across the border. German corporate news was more constructive, with Merck raising its 2026 core profit guidance for the third time this year and Siemens' outlook helping lift the DAX.
The mixed German trade print underscores the fragility of the export engine at the current euro level.
Global Macro News
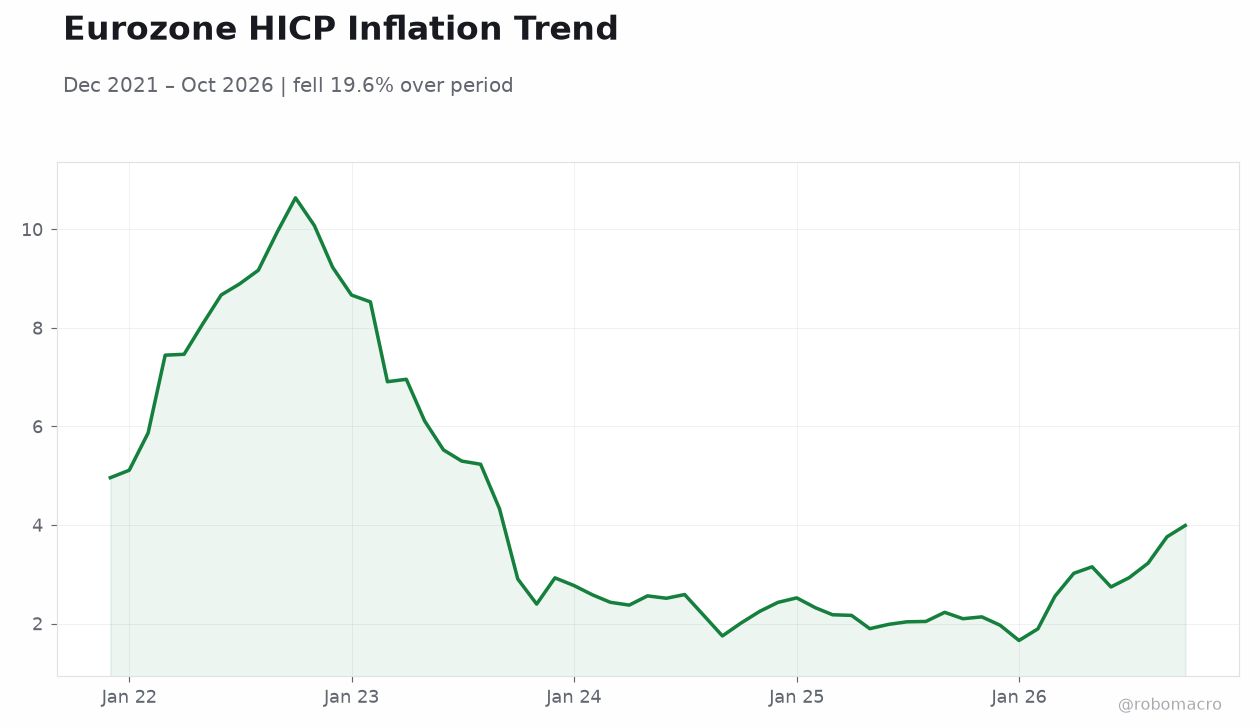
Brent crude's 3.30% surge to $95.82 is the dominant global input for the euro area, threatening to complicate the disinflation path given the currency bloc's energy import dependence. ↓ p.2