Eurozone Macro Daily(Beta Mode)
ECB Succession Talks Intensify as Bunds Sell Off
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| Euro Stoxx 50 | 6,386.86 | -0.19% |
| DAX | 26,749.95 | -0.08% |
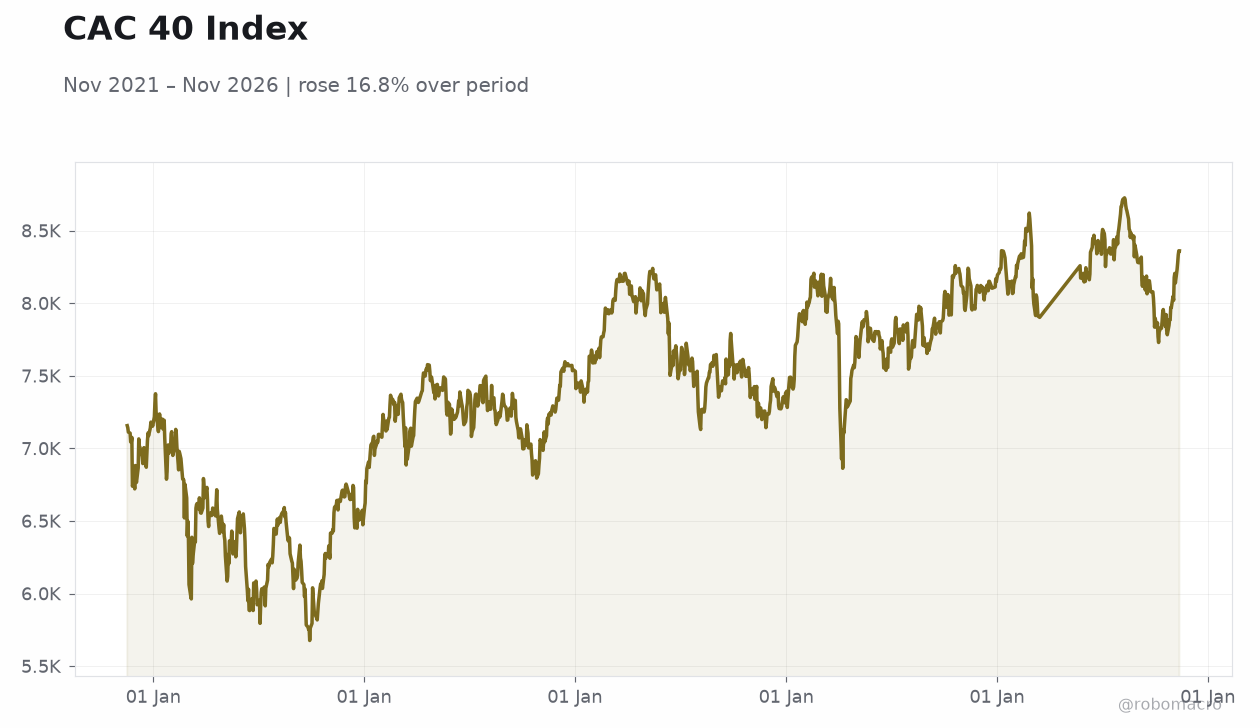
| CAC 40 | 8,368.91 | +0.09% |
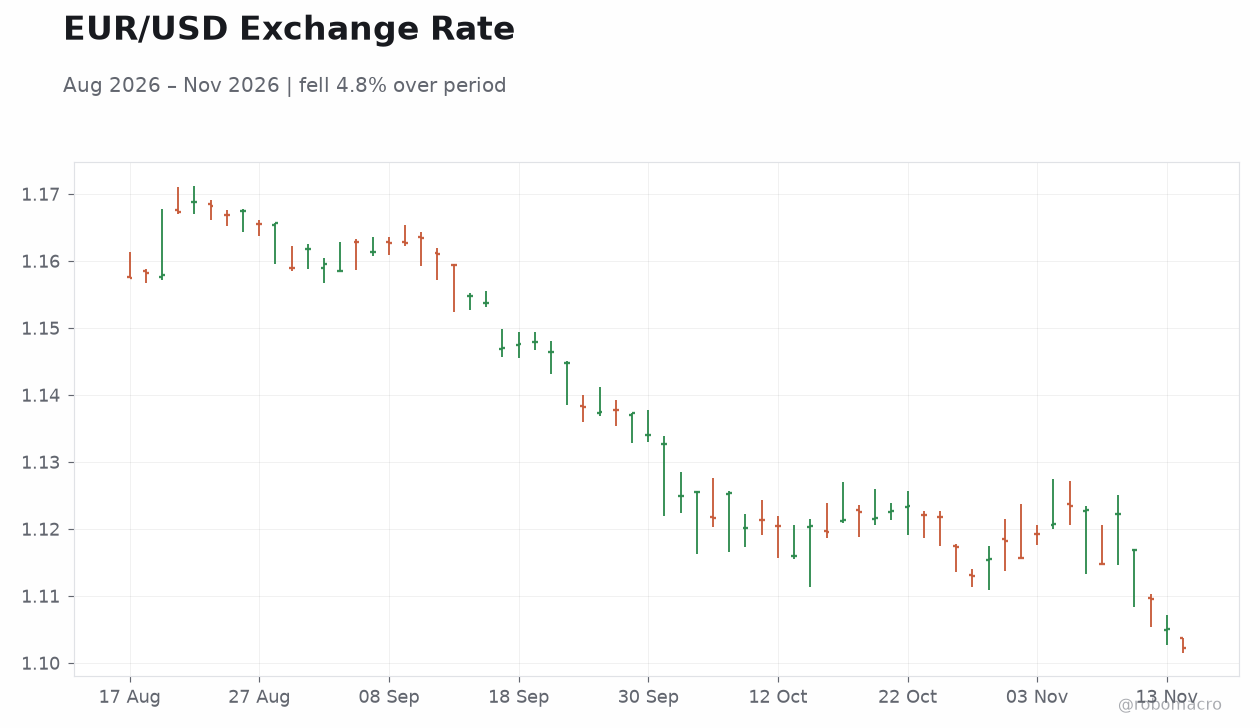
| EUR/USD | 1.10 | -0.26% |
| EUR/GBP | 0.83 | -0.09% |
| EUR/JPY | 175.84 | -0.47% |
| Gold | 3,886.30 | +0.03% |
| Brent Crude | 95.84 | +0.02% |
| Bitcoin | 64,605.36 | +0.74% |
| German 2Y Bund | 3.13% | +4 bp |
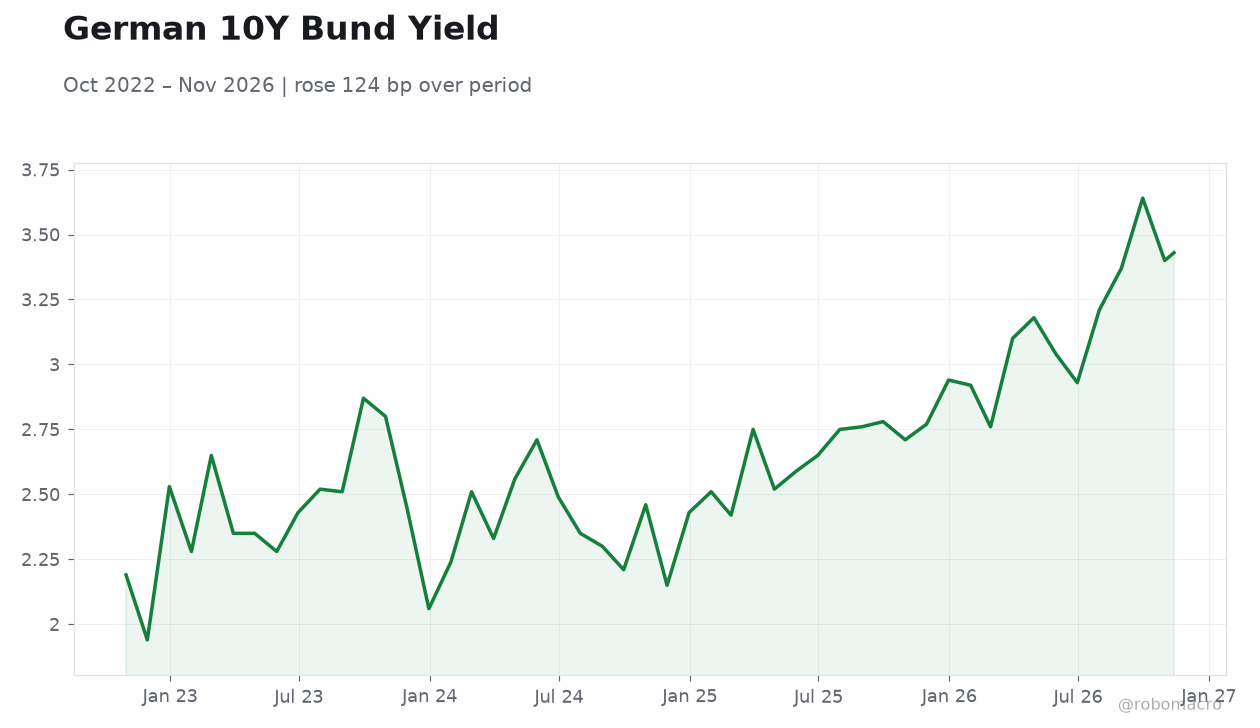
| German 10Y Bund | 3.43% | +7 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
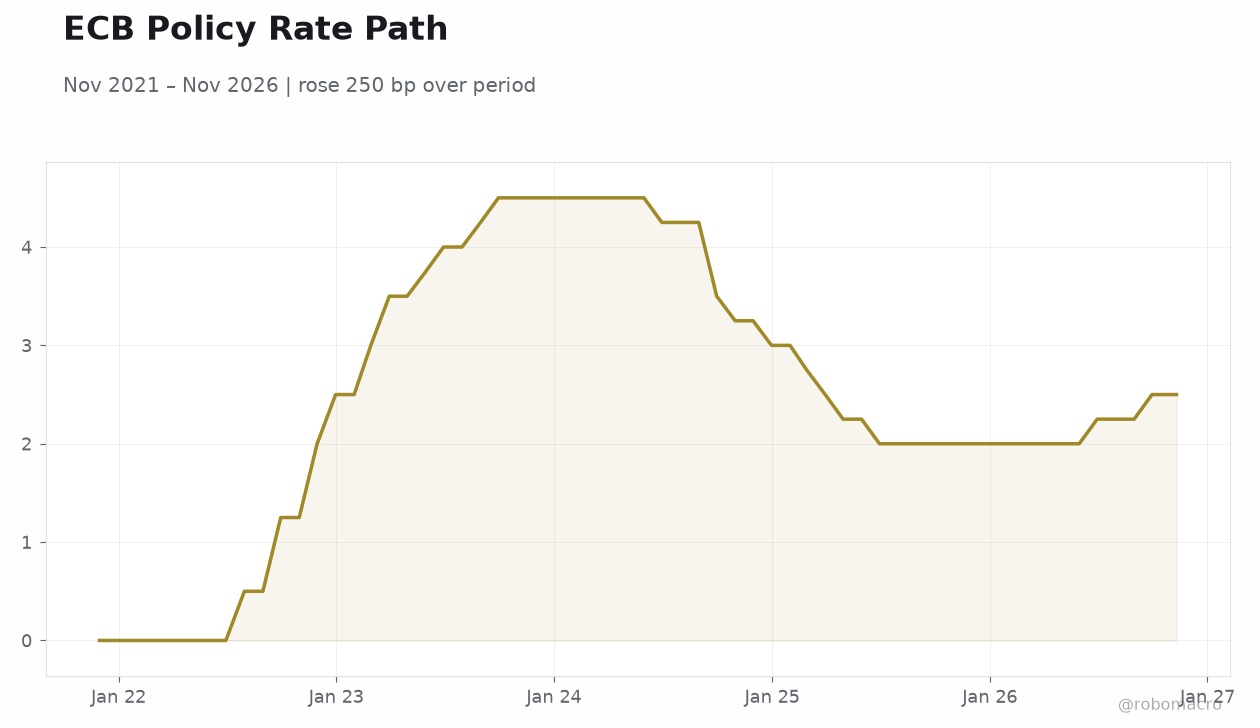 ECB Policy Rate Path | Type: macro_line | Policy Rate %: 2.5 (2026-11-10) | Range: 0–4.5 | Trend(5pt): 0,3,4.5,2,2.5
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Tuesday (2026-11-17) | |||
| Trade Balance | -5,980m | - | 04:00 |
| ZEW Economic Sentiment Index | 28.10 | - | 05:00 |
- German-French negotiations over ECB leadership accelerate, with De Cos emerging as frontrunner to succeed Lagarde
- Bund curve bear-steepened Friday, 10Y yield +7bp to 3.43% and 2Y +4bp to 3.13%, as markets price a firmer policy path
- German ZEW sentiment and Spanish trade balance headline Tuesday's light Eurozone calendar
Yesterday's Recap
Friday's session closed with a mildly defensive risk tone across Eurozone assets. The Euro Stoxx 50 slipped 0.19% and the DAX eased 0.08%, while the CAC 40 bucked the trend with a modest +0.09% gain. The standout move was in rates: the German 10-year Bund yield rose 7bp to 3.43% and the 2-year climbed 4bp to 3.13%, a bear-steepening that points to markets pricing firmer policy expectations rather than growth optimism.
EUR/USD weakened 0.26% to 1.10, with EUR/JPY down 0.47% to 175.84 and EUR/GBP off 0.09% at 0.83. No tier-one Eurozone data releases printed Friday, leaving flows and ECB succession headlines to drive positioning into the weekend.
The Day Ahead
Tuesday's calendar is thin but carries two notable prints. Spain's trade balance is due at 04:00 ET, with the previous deficit of EUR 5.98bn in focus as a gauge of external demand momentum. Germany's ZEW Economic Sentiment Index for November follows at 05:00 ET, with the prior reading at 28.1 — a survey that will be scrutinised for any deterioration in expectations amid the ECB succession uncertainty and firm rate backdrop.
Beyond the data, ECB leadership headlines remain the dominant event risk, with German proposals for top ECB posts expected next week per Merz. Bund yields near 3.43% on the 10-year leave little room for dovish surprises, so a soft ZEW would be the more market-moving outcome.
Other Economic Notes
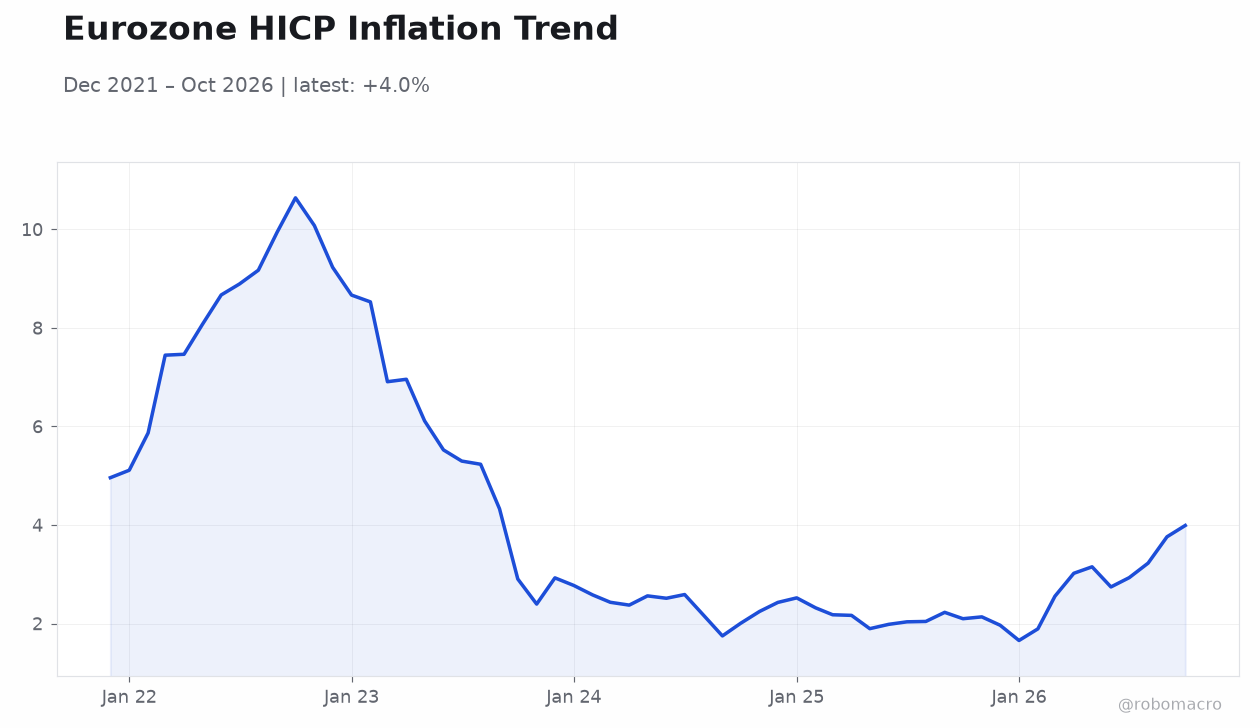
The Eurozone economy continues to outperform expectations, reinforcing the case for a firmer ECB stance — a theme echoed across sell-side commentary. French debt dynamics are drawing renewed attention, with EUR/USD forecasters flagging fiscal risk as a persistent euro headwind. ECB independence is under political scrutiny, a concern amplified by the leadership transition now underway.
Knot's reminder that the ECB cannot substitute sound fiscal policy underscores the Governing Council's discomfort with member-state budget trajectories. Spain's external position remains a watch item given the persistent trade deficit.