Eurozone Macro Daily(Beta Mode)
Bunds Rise as ECB Succession Race Heats Up
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| Euro Stoxx 50 | 6,348.35 | -0.60% |
| DAX | 26,749.95 | -0.08% |
| CAC 40 | 8,352.00 | -0.20% |
| EUR/USD | 1.10 | -0.16% |
| EUR/GBP | 0.83 | -0.00% |
| EUR/JPY | 175.20 | -0.54% |
| Gold | 3,853.00 | -0.86% |
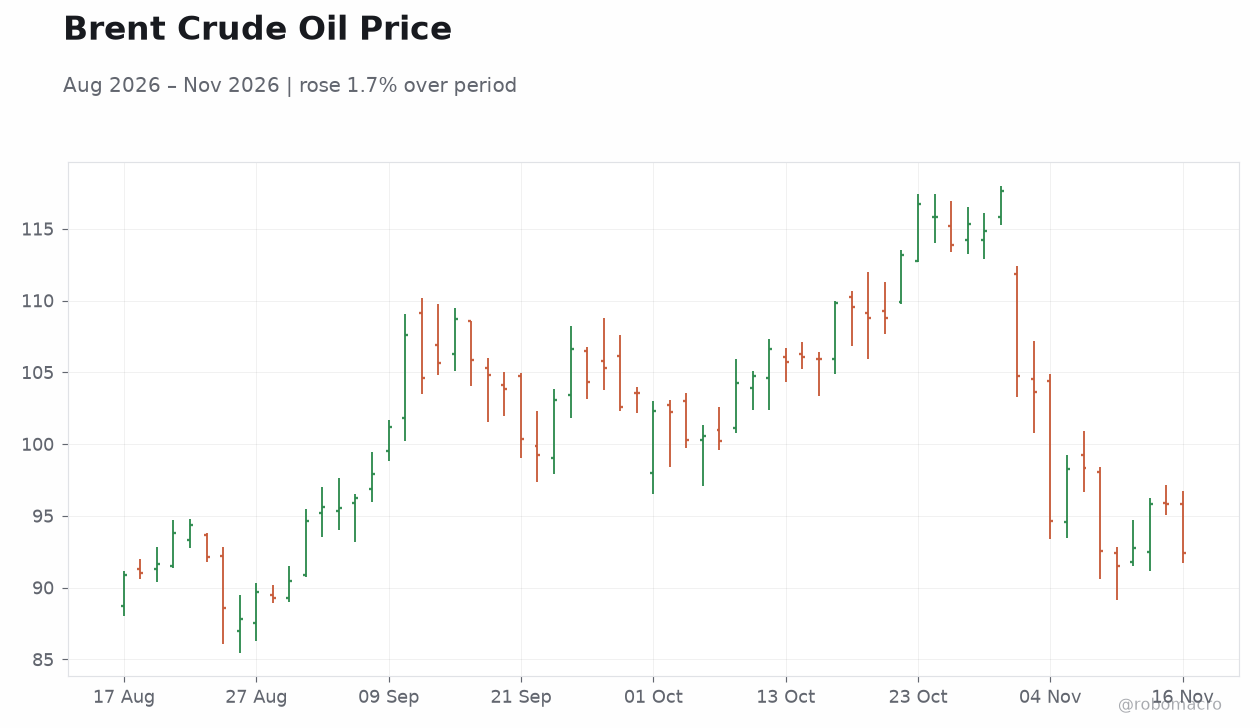
| Brent Crude | 92.44 | -3.55% |
| Bitcoin | 64,887.53 | -0.64% |
| German 2Y Bund | 3.16% | +3 bp |
| German 10Y Bund | 3.45% | +2 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
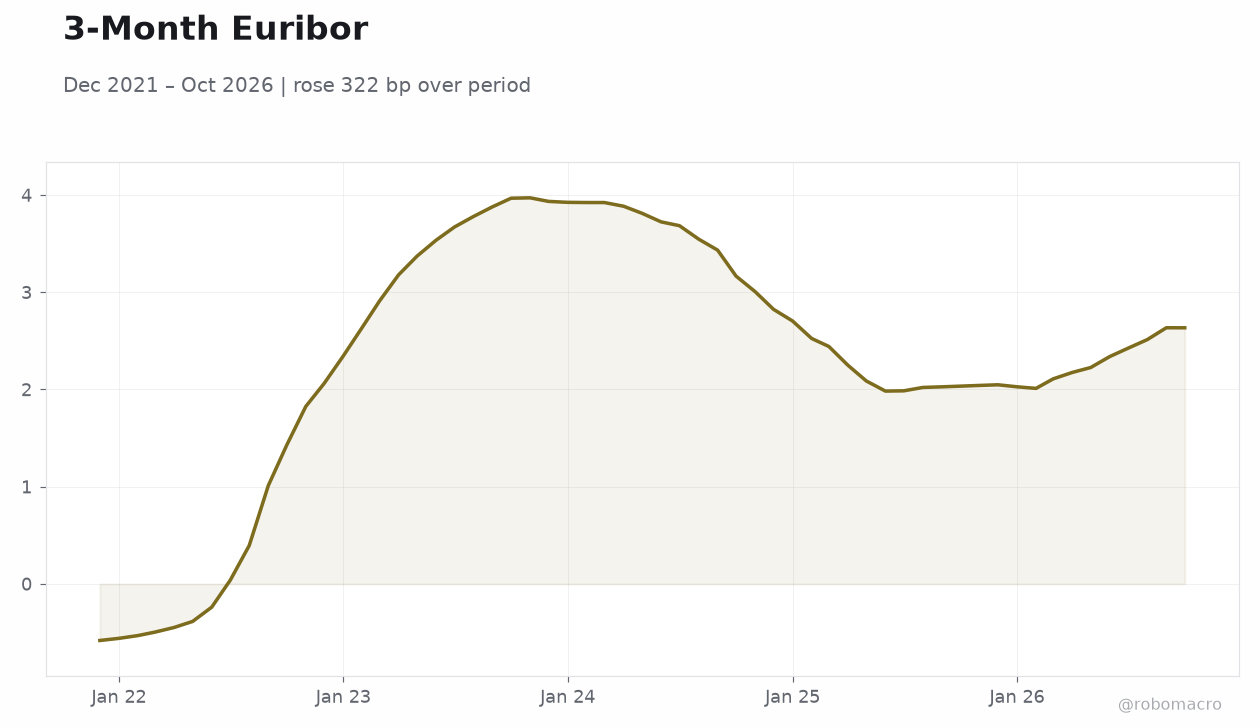
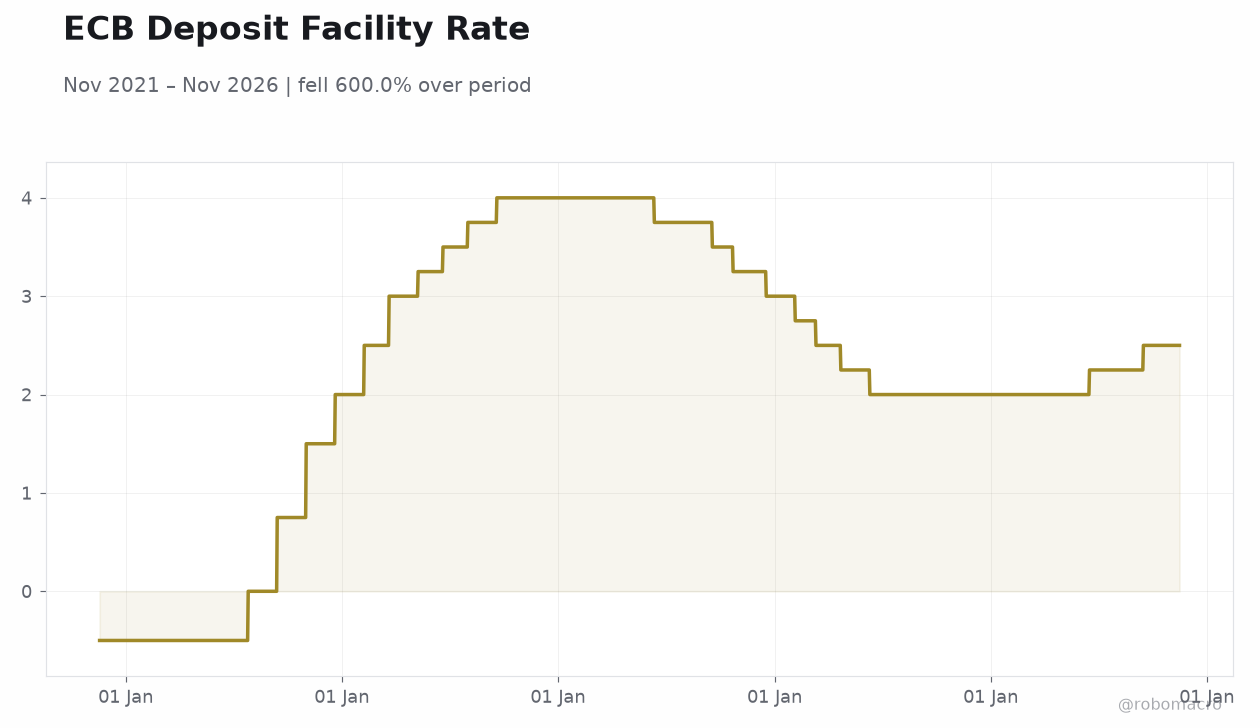 ECB Deposit Facility Rate | Type: macro_line | ECB Deposit Facility Rate: 2.5 (2026-11-16) | Range: -0.5–4 | Trend(5pt): -0.5,2.5,4,2,2.5
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Trade Balance | -5,980m | - | 04:00 |
| ZEW Economic Sentiment Index | 28.10 | - | 05:00 |
- German ZEW sentiment and Spanish trade balance headline a thin Eurozone calendar; ZEW watched after prior 28.1 reading
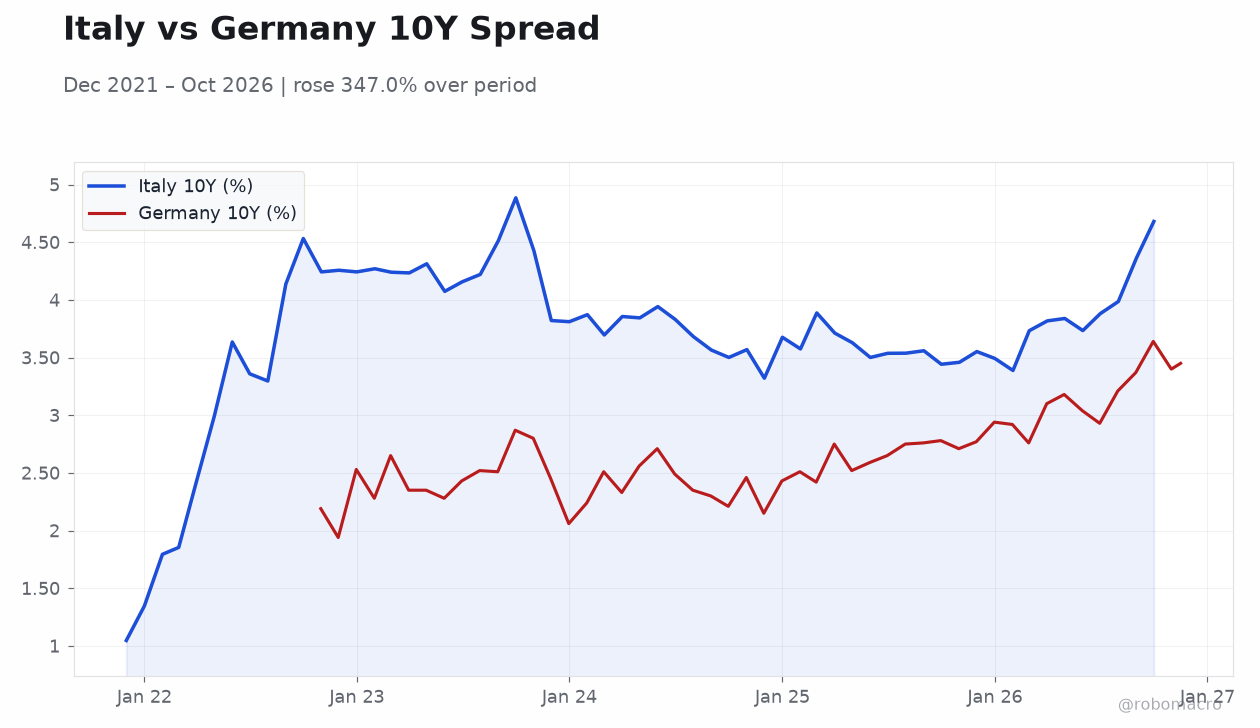
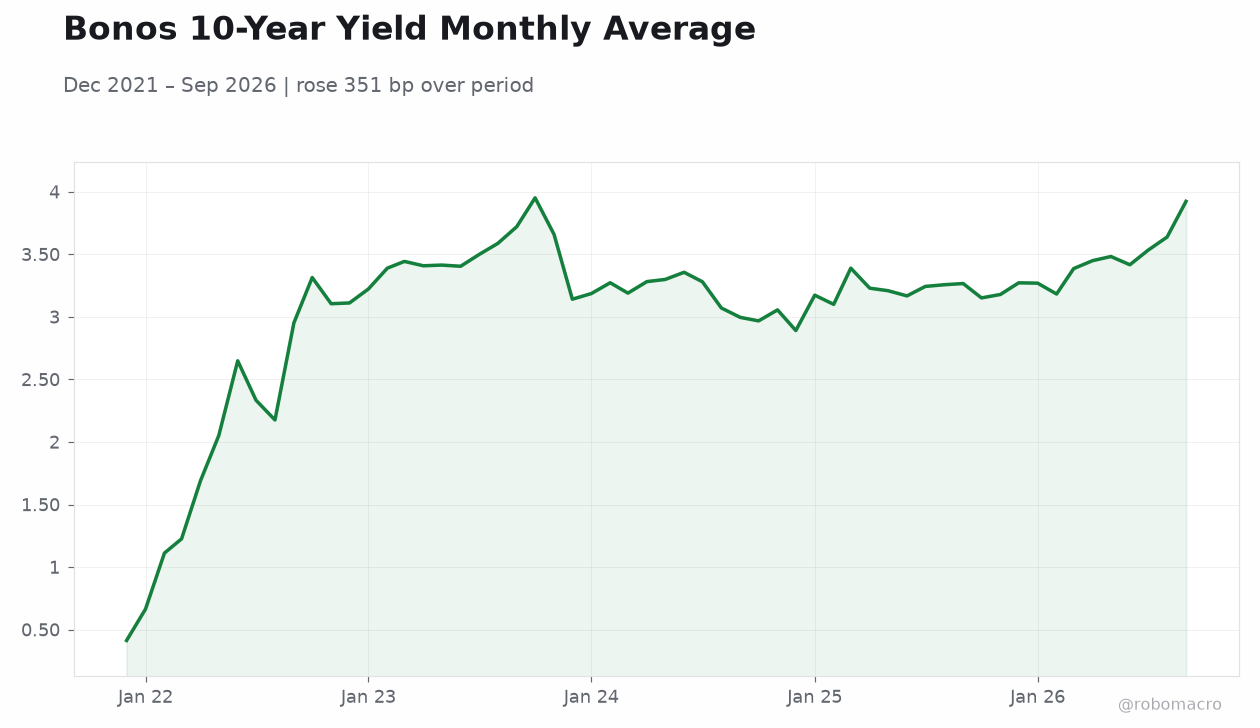
- Bund curve bear-steepened, with 2Y up 3 bp to 3.16% and 10Y up 2 bp to 3.45%, as traders price three ECB hikes by late 2027
- ECB warns AI-driven market concentration and sovereign debt pose financial stability risks; succession talks intensify between Berlin and Paris
Yesterday's Recap
Eurozone markets opened the week on a defensive footing, with the Euro Stoxx 50 shedding 0.60% and the CAC 40 down 0.20%, while the DAX held comparatively firm at -0.08%. The single currency softened across the board, with EUR/USD slipping 0.16% to 1.10 and EUR/JPY falling 0.54% to 175.20, reflecting a broadly firmer dollar tone. German government bonds sold off, pushing the 2-year yield up 3 bp to 3.16% and the 10-year up 2 bp to 3.45%, as markets continued to price an eventual reversal of the ECB's September hike.
Brent crude collapsed 3.55% to $92.44, offering a rare disinflationary offset for an economy still grappling with 4.00% CPI. Gold retreated 0.86% to $3,853, and Bitcoin eased 0.64%. No major Eurozone data releases were scheduled, leaving flows and rate expectations to drive price action.
The Day Ahead
The calendar turns to German ZEW Economic Sentiment for November, a high-impact print watched closely for any deterioration in analyst expectations after the prior 28.1 reading. Spain releases its trade balance, with the prior deficit of €5.98bn in focus as a gauge of external demand resilience. Neither release carries a published consensus in the current calendar, so market reaction will hinge on directional surprise rather than a pre-positioned whisper number.
With no further Eurozone prints scheduled through tomorrow, attention will quickly rotate back to ECB communication and the unfolding leadership succession story.
Other Economic Notes
The ECB's latest Financial Stability Review flagged twin vulnerabilities: extreme market concentration in AI-linked equities and elevated sovereign debt loads across member states. The warning lands as euro-area yields climb on expectations of three ECB hikes by late 2027, a striking repricing given the deposit rate sits at 2.50% following September's 25 bp increase. Greek inflation at 4.00% in October underscores persistent dispersion within the currency bloc, complicating a single policy stance.
Meanwhile, UniCredit's EU- and Fed-approved takeover of Commerzbank marks a significant step in German banking consolidation, with implications for credit provision and sovereign-bank linkages.