Eurozone Macro Daily(Beta Mode)
ZEW Surges, Stocks Slide as ECB Succession Nears
Market Snapshot
| Asset | Level | Change |
|---|---|---|
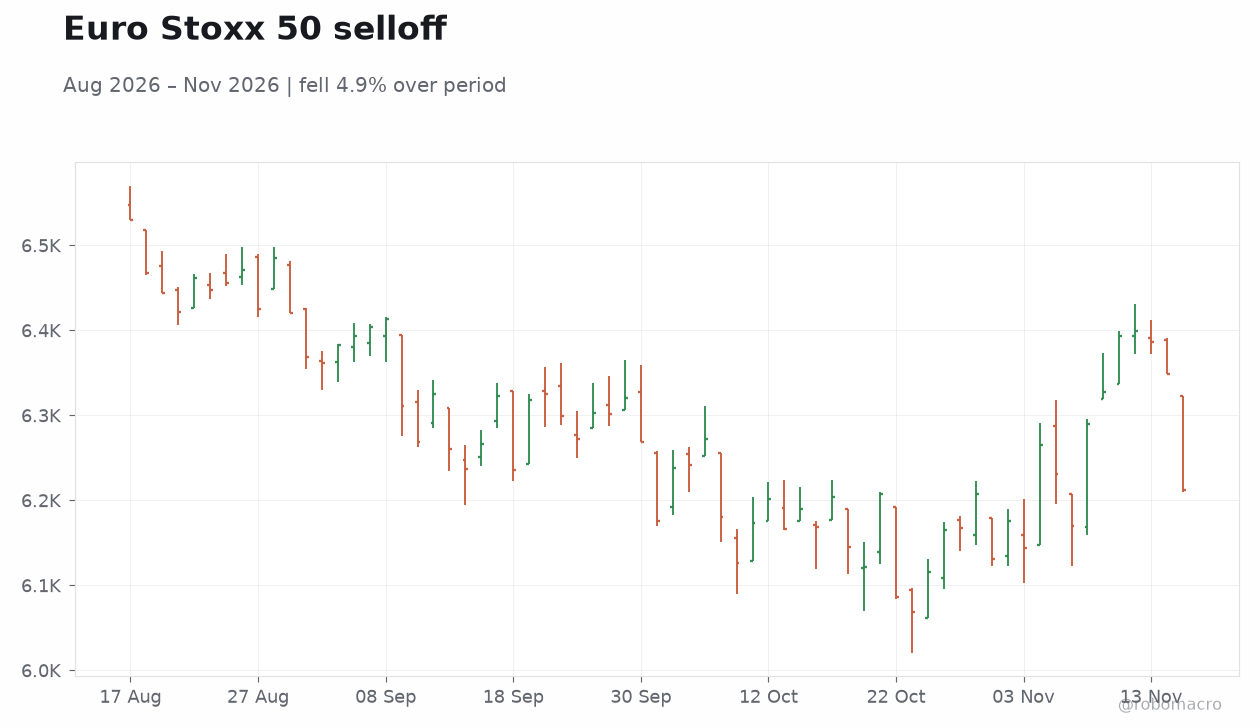
| Euro Stoxx 50 | 6,212.11 | -2.15% |
| DAX | 26,045.37 | -2.08% |
| CAC 40 | 8,216.78 | -1.62% |
| EUR/USD | 1.10 | -0.06% |
| EUR/GBP | 0.83 | -0.17% |
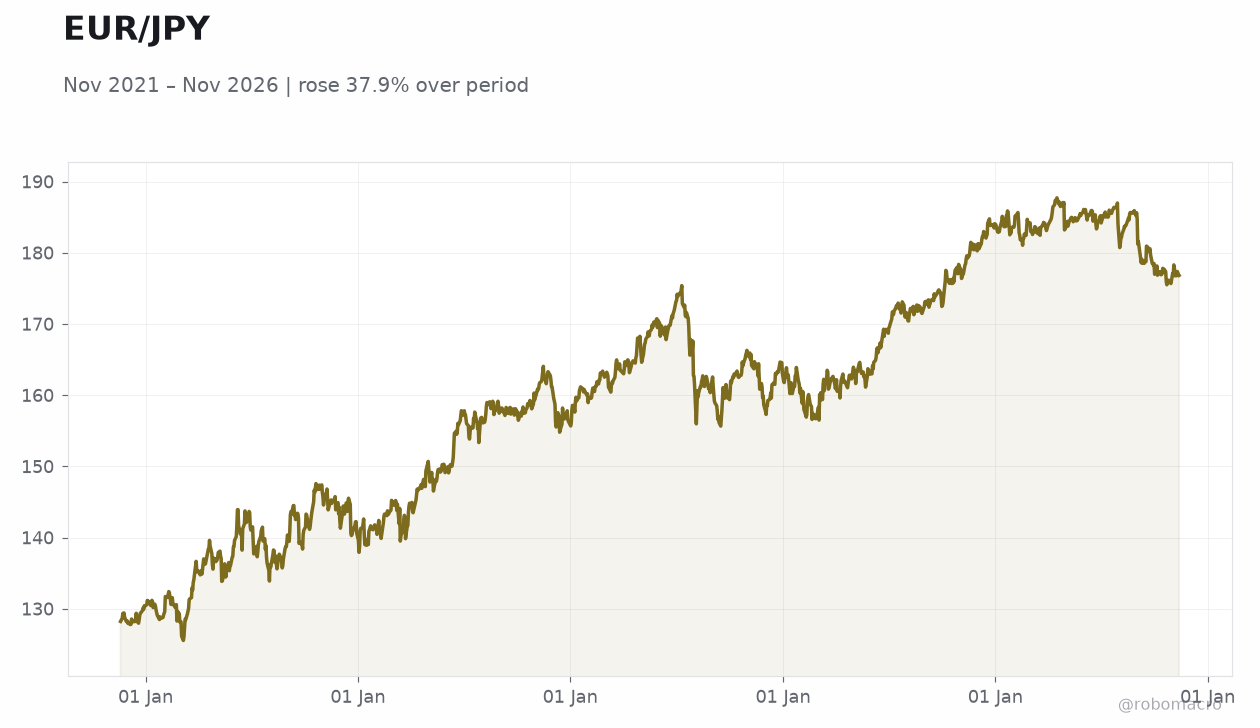
| EUR/JPY | 174.89 | -0.31% |
| Gold | 3,864.20 | +0.29% |
| Brent Crude | 93.14 | +0.76% |
| Bitcoin | 64,284.18 | -0.88% |
| German 2Y Bund | 3.11% | -5 bp |
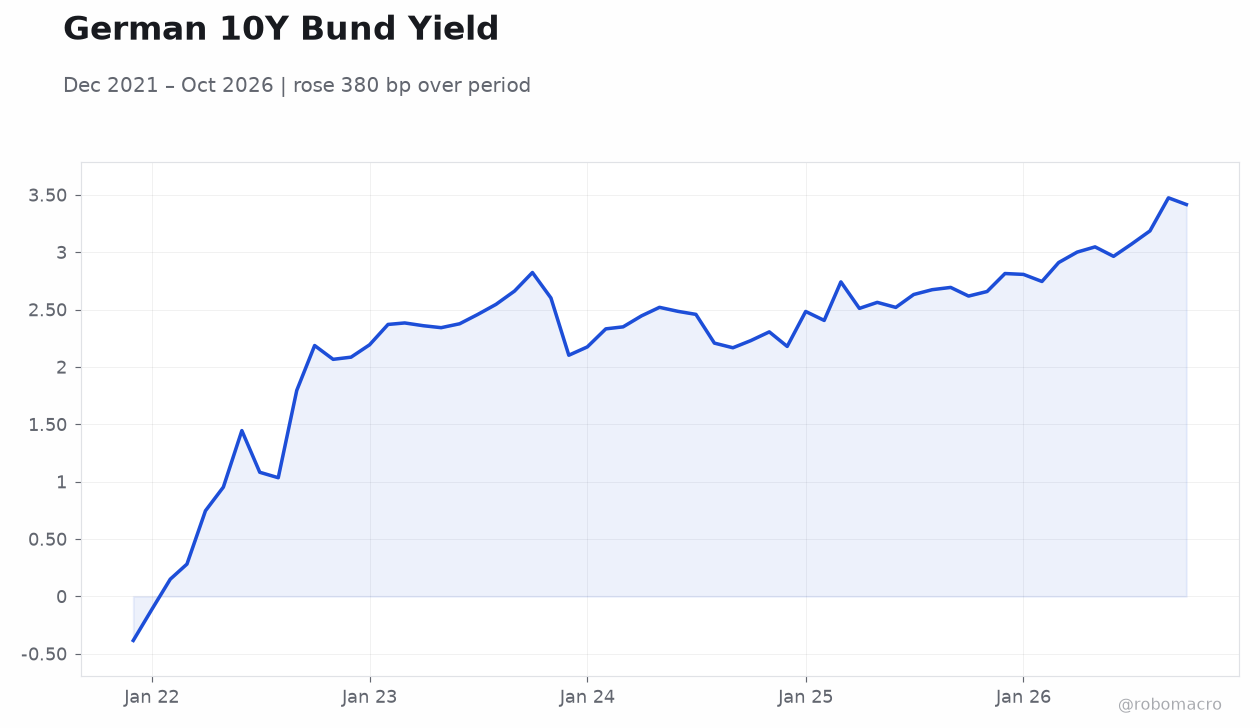
| German 10Y Bund | 3.42% | -3 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Trade Balance | -5,980m | - | -7,820m |
| ZEW Economic Sentiment Index | 28.10 | 29 | 35.60 |
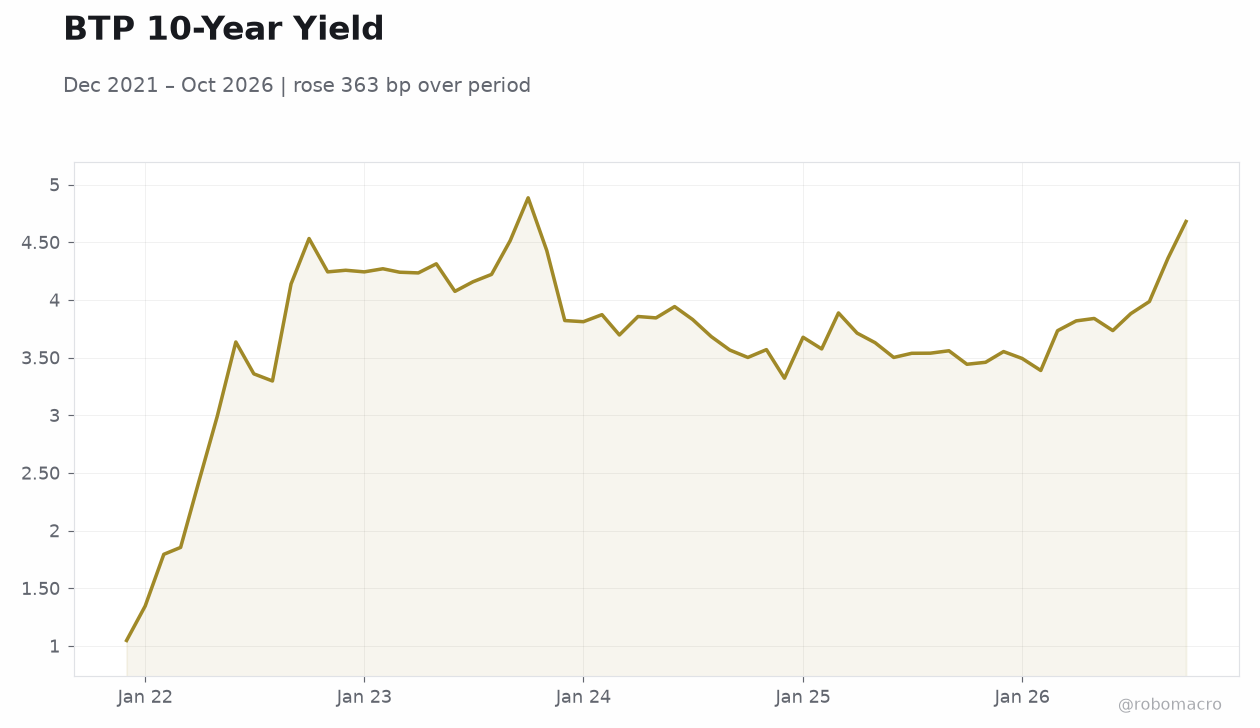 BTP 10-Year Yield | Type: macro_line | BTP 10-Year Yield: 4.68 (2026-10-01) | Range: 1.047–4.885 | Trend(6pt): 1.047,4.27,3.856,3.501,3.986,4.68
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Thursday (2026-11-19) | |||
| Headline Unemployment Rate | 4 | - | 00:30 |
- German ZEW economic sentiment jumped to 35.6 in November, well above the 29 consensus and 28.1 prior, signaling improving investor expectations for Europe's largest economy.
- European equities sold off sharply, with the Euro Stoxx 50 down 2.15% and the DAX off 2.08%, while Bund yields eased (2Y -5bp to 3.11%, 10Y -3bp to 3.42%).
- Spain's Hernández de Cos has emerged as the frontrunner to succeed Lagarde as ECB President, with Germany backing him and nominating Markus Brunnermeier for chief economist.
Yesterday's Recap
Spanish trade data printed a deficit of €7.82bn, widening from the prior €5.98bn shortfall, pointing to softer external demand. The German ZEW economic sentiment index for November surprised sharply to the upside at 35.6 versus consensus of 29 and the prior 28.1, suggesting investors see improving conditions ahead for Germany despite ongoing industrial headwinds. Risk assets nonetheless sold off hard across the bloc: the Euro Stoxx 50 fell 2.15%, the DAX dropped 2.08%, and the CAC 40 lost 1.62%.
Rates moved the other way, with the German 2-year Bund yield easing 5bp to 3.11% and the 10-year down 3bp to 3.42%, a classic risk-off flattening. EUR/USD slipped 0.06% to 1.10, EUR/GBP fell 0.17% to 0.83, and EUR/JPY eased 0.31% to 174.89. Gold gained 0.29% to $3,864/oz while Brent crude rose 0.76% to $93.14, with energy strength contrasting the equity weakness.
The Day Ahead
The Eurozone calendar is light, with the only scheduled release being the Dutch headline unemployment rate, due Thursday at 06:30 CET, with the prior reading at 4.0% and no consensus published. With no tier-one euro area prints on deck, market direction will be driven by spillovers from global risk sentiment and any ECB succession headlines. Bund yields will likely take their cue from core rates abroad, while the euro remains sensitive to the de Cos/Brunnermeier leadership news flow.
Traders will also keep an eye on French political developments after Le Pen's pension pledge. Absent domestic catalysts, expect positioning ahead of Thursday's Dutch print and next month's ECB decision to dominate.
Other Economic Notes
The European Commission raised its euro area growth forecast to 1.2% for 2026, citing an AI-driven export boom, but flagged sharply diverging fortunes among member states — France's GDP projection was halved and its 2027 outlook cut to just 0.6%, with inflation seen elevated through 2027. The Commission noted the eurozone economy is holding up despite the Iran war, though France remains the weakest large economy. ↓ p.2