GCC Macro Daily(Beta Mode)
Saudi Pipeline Restart Offsets Oil Slide
Market Snapshot
| Asset | Level | Change |
|---|---|---|
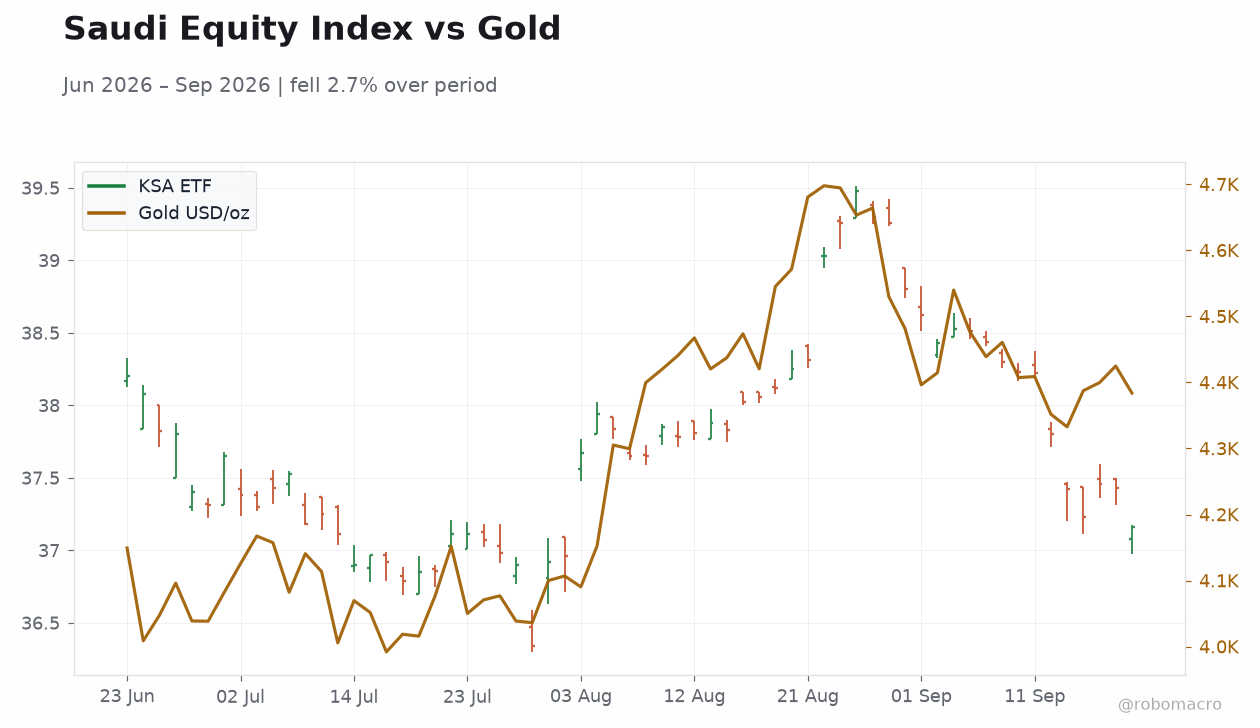
| Saudi Aramco | 25.64 | -0.16% |
| MSCI Saudi | 37.25 | +0.24% |
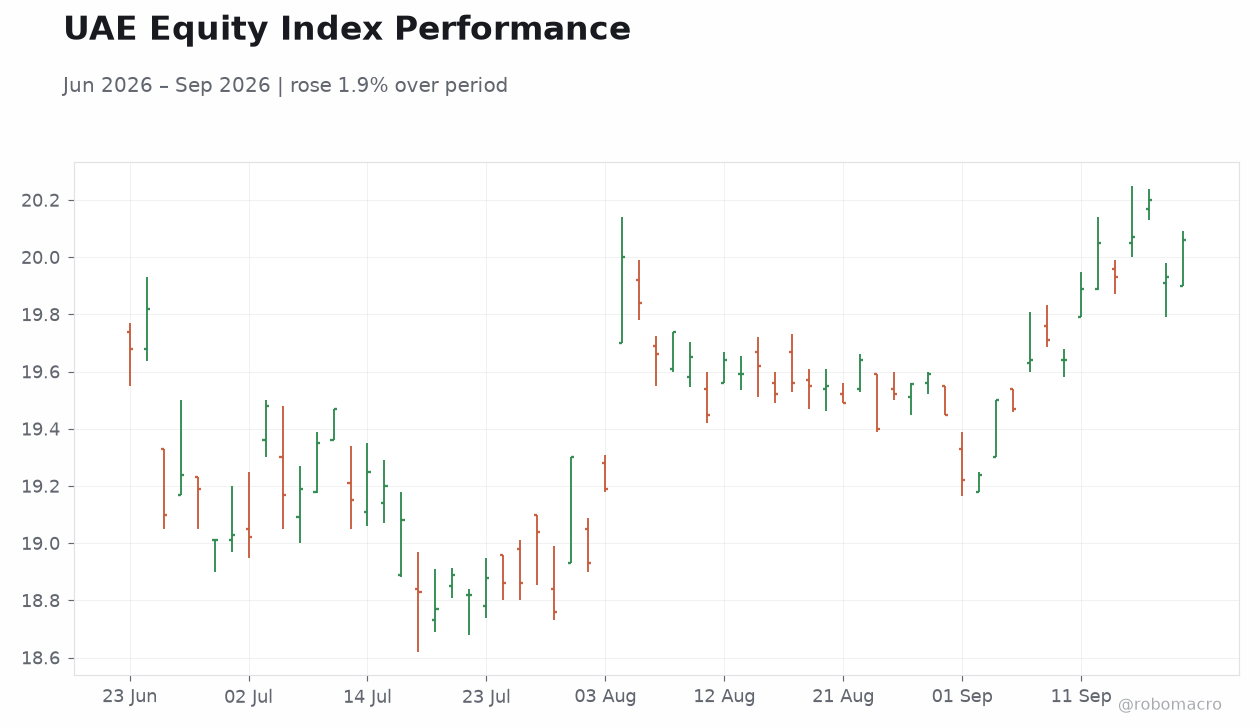
| MSCI UAE | 20.13 | +0.35% |
| MSCI Qatar | 16.77 | -0.65% |
| MSCI Kuwait | 36.99 | +0.00% |
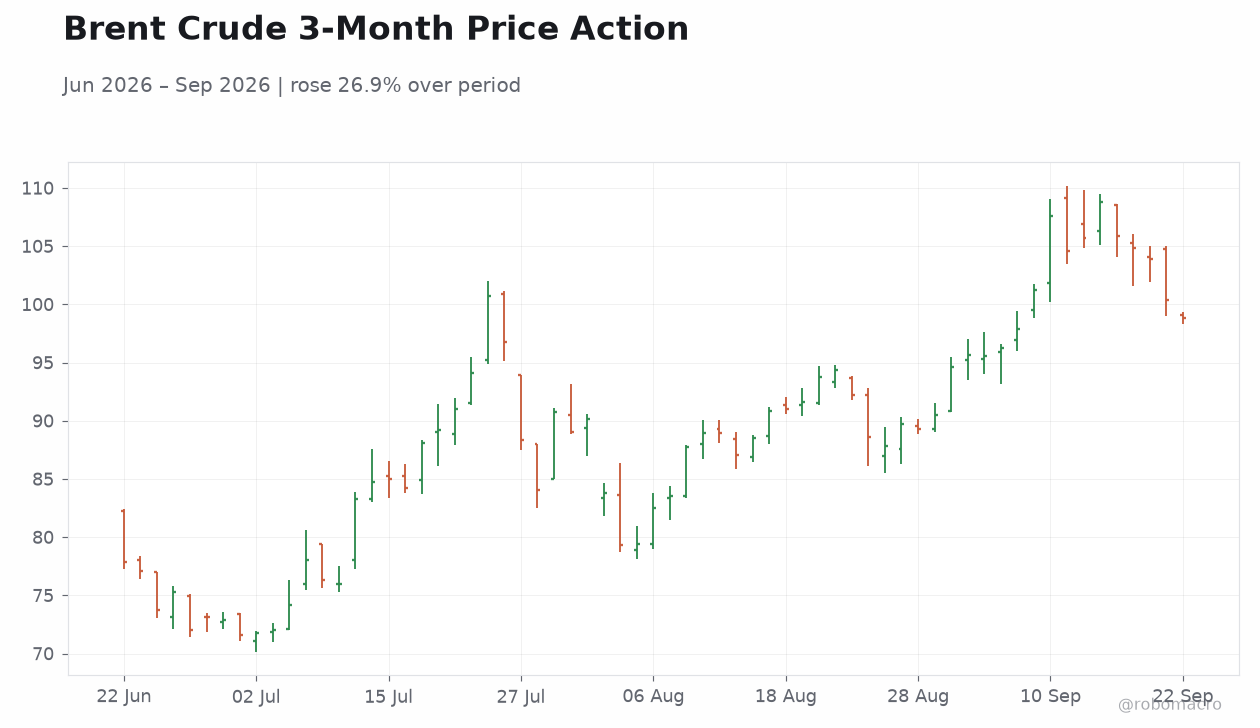
| Brent Crude | 98.81 | -1.52% |
| WTI Crude | 89.83 | -6.21% |
| Gold | 4,372.60 | -0.26% |
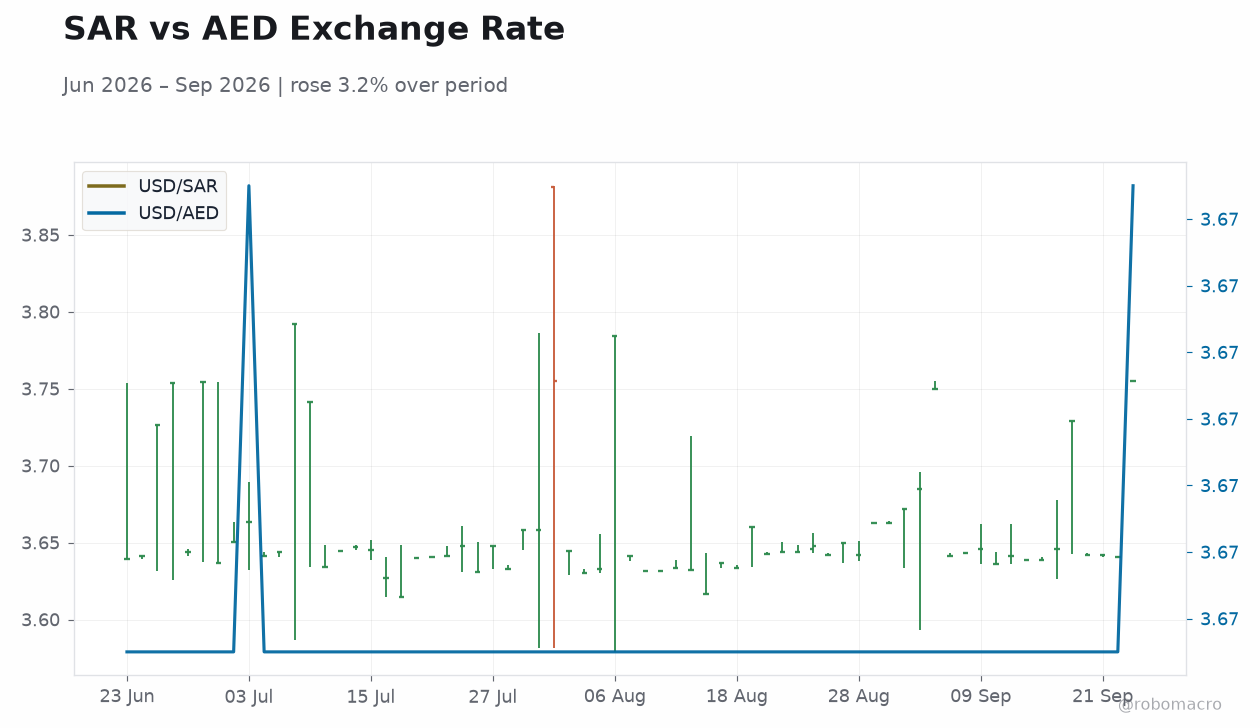
| USD/SAR | 3.76 | +3.14% |
| USD/AED | 3.67 | +0.04% |
| USD/KWD | 0.31 | -0.20% |
| Bitcoin | 86,549.40 | -0.06% |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
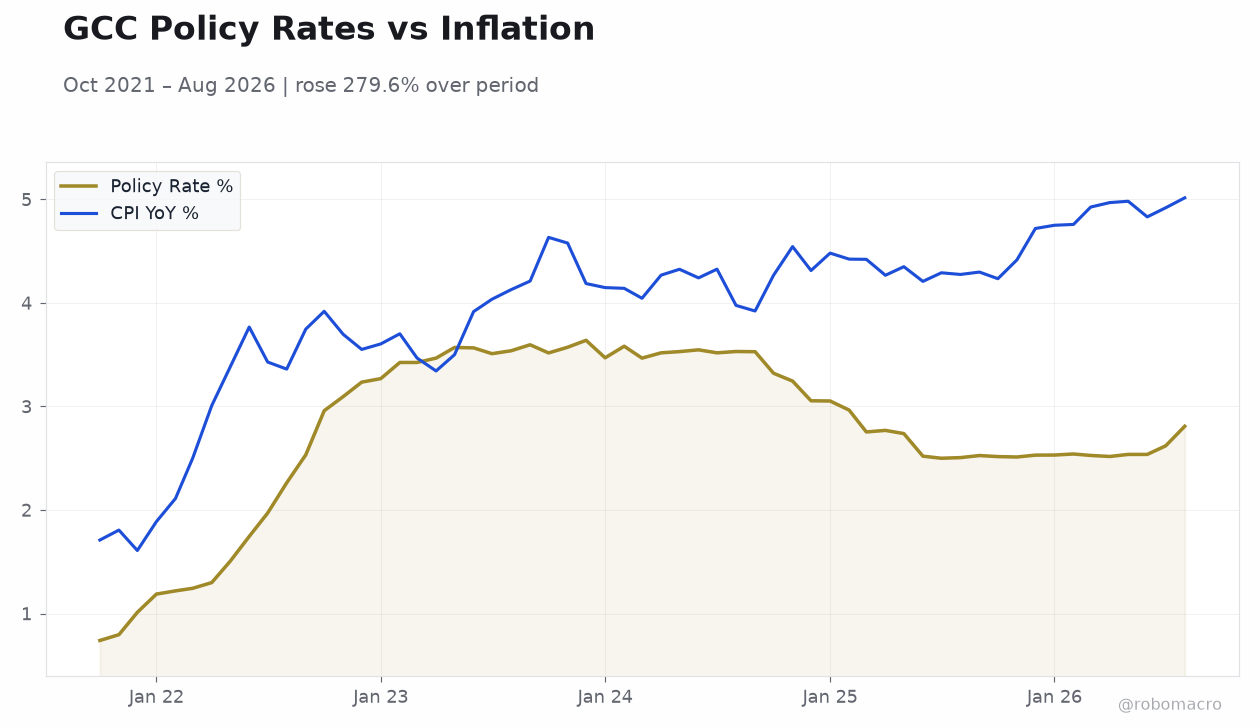 GCC Policy Rates vs Inflation | Type: macro_line | Policy Rate %: 2.809 (2026-08-01) | Range: 0.74–3.639 | Trend(6pt): 0.74,3.235,3.582,2.769,2.537,2.809 | CPI YoY %: 5.015 (2026-08-01) | Range: 1.609–5.015 | Trend(6pt): 1.71,3.551,4.141,4.267,4.831,5.015
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Saudi Arabia restarts East-West pipeline to resume Yanbu exports amid Houthi tensions.
- MSCI UAE leads regional equities with 0.35% gain while WTI crude falls 6.21%.
- Saudi 2027 growth forecast at 6.1% highlights non-oil diversification progress.
Yesterday's Recap
Saudi Arabia restarted its East-West oil pipeline and will resume exports from Yanbu, easing some supply concerns after prior disruptions. Riyadh denied claims that its tanker purchases had increased Iraqi oil transport costs. US Secretary of State Marco Rubio affirmed Washington will meet defence commitments to Saudi Arabia, while the UK offered aerial refuelling support against Houthi threats.
Saudi Aramco declined 0.16% to 25.64 as MSCI Saudi rose 0.24% to 37.25. MSCI UAE advanced 0.35% to 20.13 while MSCI Qatar fell 0.65% to 16.77 and MSCI Kuwait held steady. Brent crude eased 1.52% to 98.81 and WTI dropped sharply 6.21% to 89.83.
Gold eased 0.26% to 4,372.60. USD/SAR jumped 3.14% to 3.76, USD/AED rose 0.04% to 3.67, and USD/KWD slipped 0.20% to 0.31. Bitcoin was little changed, down 0.06% at 86,549.40.
Saudi Arabia’s economy is projected to expand 6.1% in 2027, supporting Vision 2030 goals. The UAE topped the Arab Digital Economy Index 2026, with Saudi Arabia, Bahrain, Qatar and Oman also ranking in the top group.
The Day Ahead
Markets will monitor any follow-through on Saudi pipeline operations and potential OPEC+ supply signals. Geopolitical developments along the Red Sea and Yemen border remain key drivers for oil price volatility. UAE digital economy leadership and regional rankings may draw further investor attention to non-oil sectors.
No major data releases are scheduled across the GCC, shifting focus to equity flows and FX reserve updates. Central banks are expected to maintain current policy stances aligned with global rates. Energy infrastructure security statements from the US and France will continue to influence regional risk sentiment.
UAE, Saudi Arabia, Qatar and five other nations issued a joint Gaza warning, underscoring coordinated diplomatic positioning that supports sovereign credit stability across the bloc even as crude benchmarks face downward pressure.
Other Economic Notes
The UAE topped the Arab Digital Economy Index 2026, with Saudi Arabia, Bahrain, Qatar and Oman also ranking in the top group, underscoring accelerating diversification. Saudi growth projections reinforce fiscal resilience despite oil price swings. ↓ p.2