GCC Macro Daily(Beta Mode)
Houthi Strikes Spur Saudi Oil Supply Fears
Market Snapshot
| Asset | Level | Change |
|---|---|---|
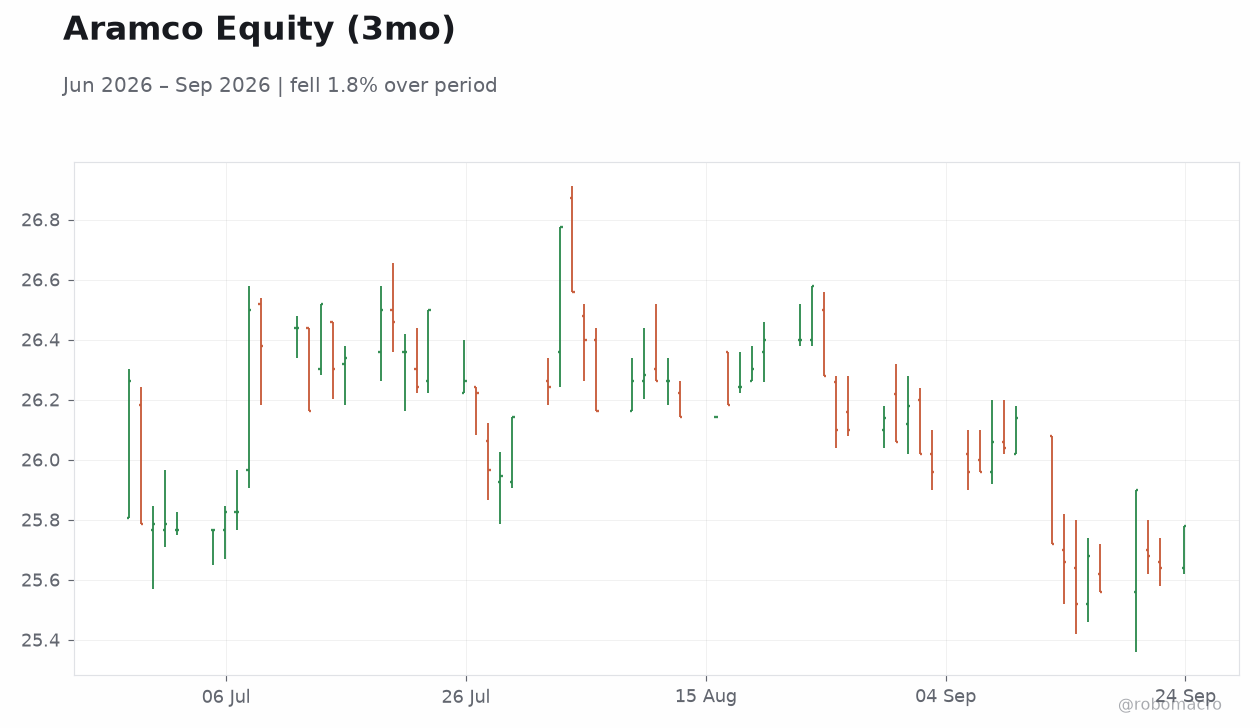
| Saudi Aramco | 25.78 | +0.55% |
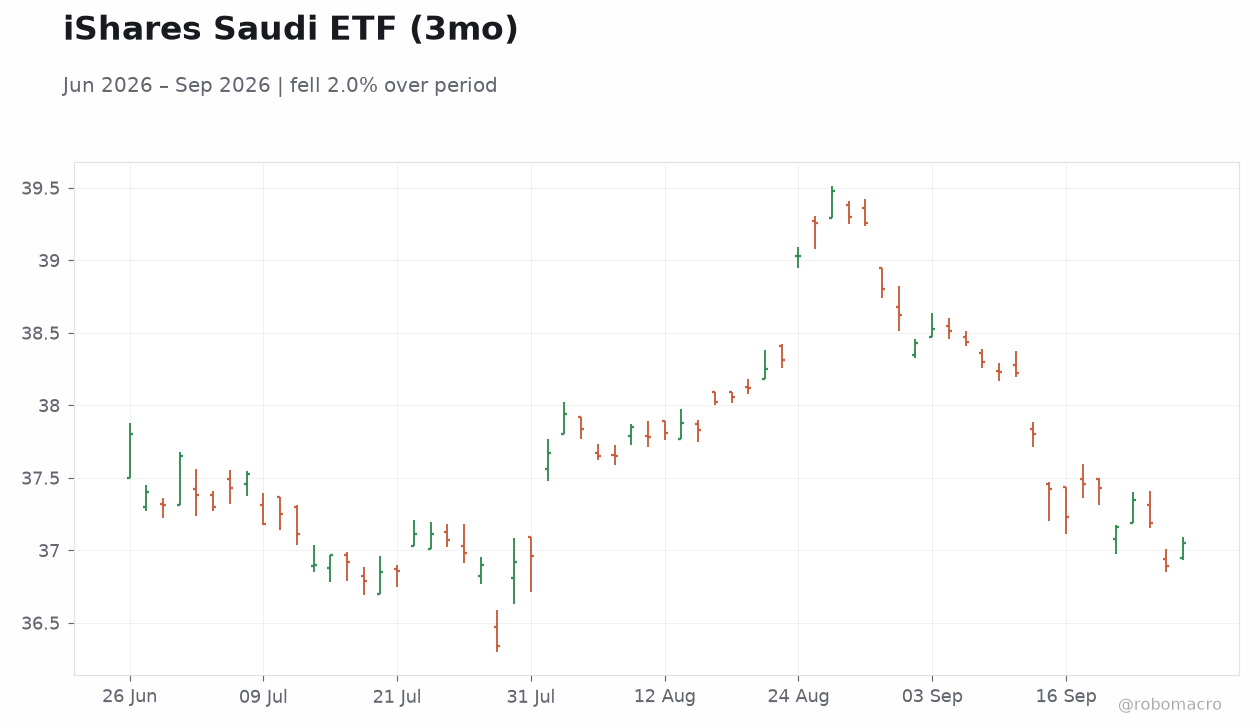
| MSCI Saudi | 37.05 | +0.43% |
| MSCI UAE | 20.24 | +0.25% |
| MSCI Qatar | 16.75 | -0.21% |
| MSCI Kuwait | 36.80 | -0.62% |
| Brent Crude | 98.21 | -5.86% |
| WTI Crude | 93.28 | +0.94% |
| Gold | 4,234.10 | -2.02% |
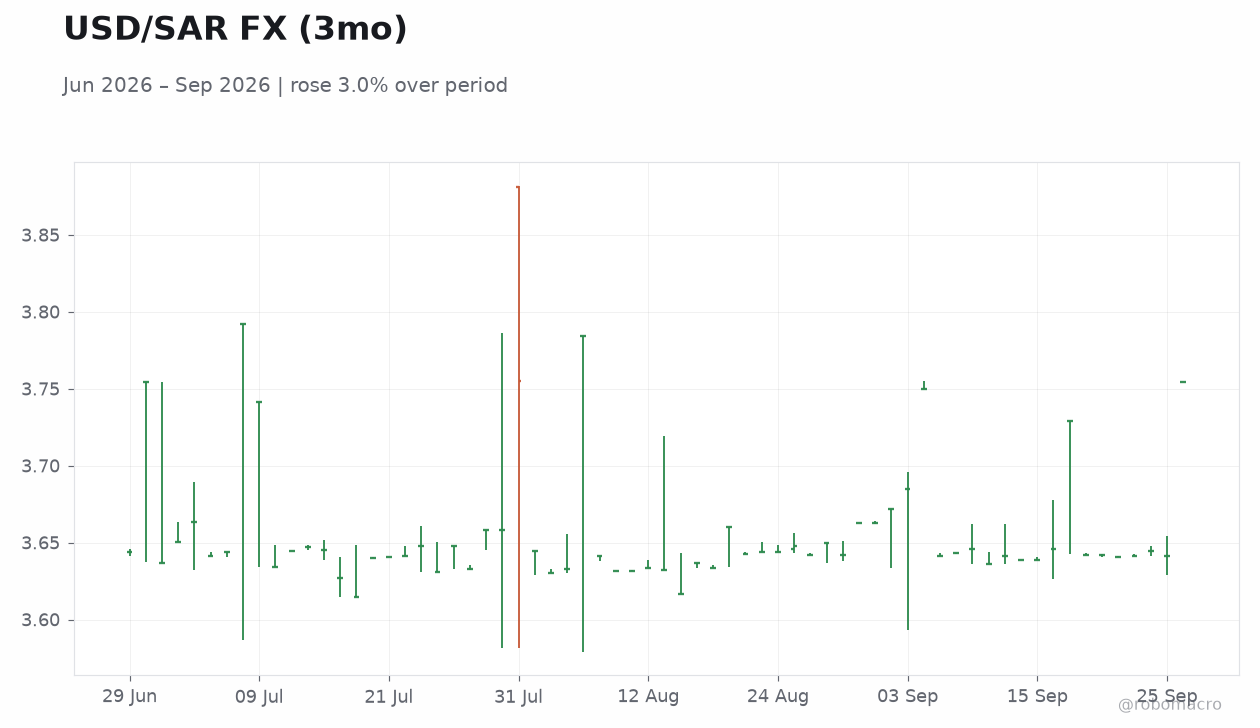
| USD/SAR | 3.75 | +3.10% |
| USD/AED | 3.67 | +0.04% |
| USD/KWD | 0.31 | -0.25% |
| Bitcoin | 83,494.59 | -1.08% |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
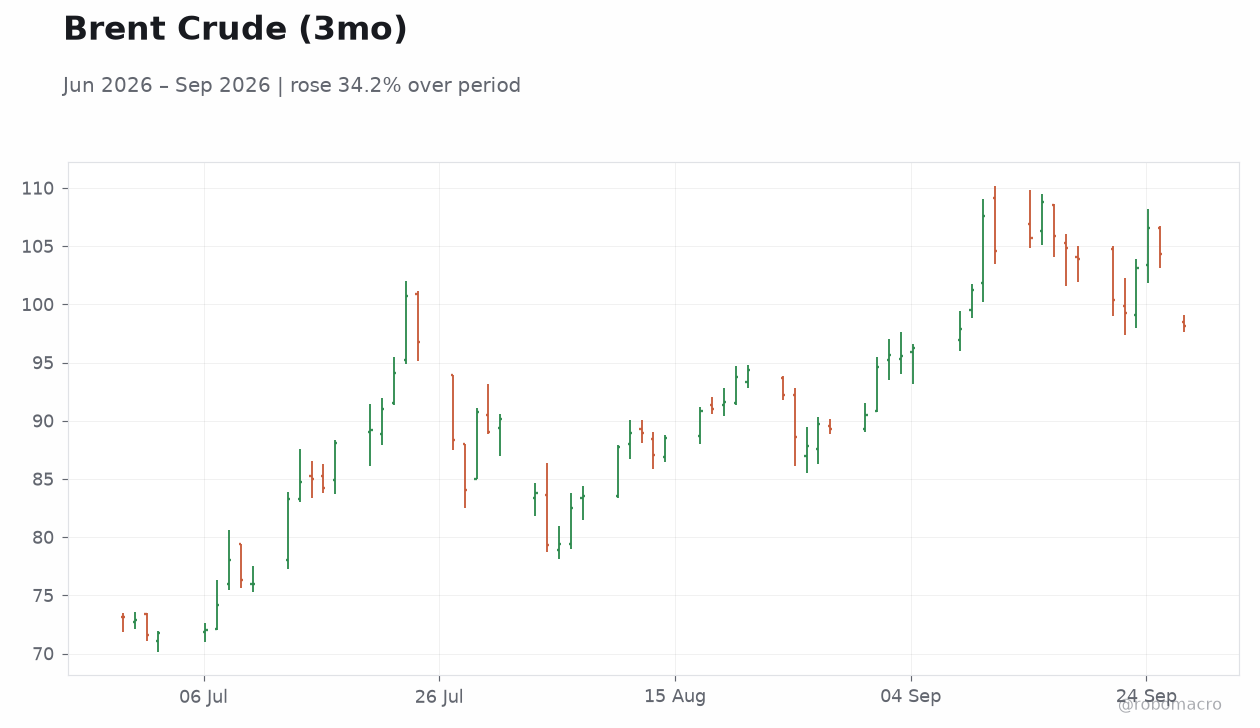 Brent Crude (3mo) | Type: market_hloc | Brent USD/bbl: 98.15 (2026-09-27) | Range: 71.57–108.8 | Trend(5pt): 73.15,94.07,87.07,96.28,98.15
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Houthi attacks on Saudi facilities lifted supply-risk premia, prompting French defensive deployment to Yanbu while Brent settled at 98.21 after a 5.86% decline.
- Saudi Aramco rose 0.55% to 25.78 and MSCI Saudi gained 0.43% to 37.05, whereas MSCI Qatar fell 0.21% to 16.75 and MSCI Kuwait declined 0.62% to 36.80 amid regional tensions.
- No GCC economic data releases occurred; central banks maintained USD pegs with no policy shifts.
Yesterday's Recap
Houthi missile attacks on Saudi cities including Taif and Yanbu triggered immediate supply concerns, lifting oil prices and prompting France to deploy defensive troops and radar systems to protect the Yanbu oil port. Saudi Foreign Minister Prince Faisal bin Farhan urged a comprehensive international framework for regional navigation security. Iran offered mediation between Saudi Arabia and Yemen, noting shared Muslim interests to de-escalate.
Saudi Aramco gained 0.55% to 25.78 and MSCI Saudi rose 0.43% to 37.05, while MSCI UAE edged up 0.25% to 20.24. In contrast, MSCI Qatar fell 0.21% to 16.75 and MSCI Kuwait dropped 0.62% to 36.80. Brent crude settled at 98.21 after a 5.86% move reflecting divergent flows versus WTI at 93.28 (+0.94%).
Gold closed at 4,234.10 (-2.02%). No PMI, CPI, GDP or fiscal data emerged from any GCC member, leaving diversification metrics unchanged. USD/SAR strengthened 3.10% to 3.75 while USD/AED rose 0.04% to 3.67 and USD/KWD eased 0.25% to 0.31.
Bitcoin finished at 83,494.59 (-1.08%).
The Day Ahead
No economic releases, central bank decisions or sovereign auctions are scheduled across Saudi Arabia, UAE, Qatar, Kuwait, Oman or Bahrain for the next two days. Markets will monitor Houthi developments and any OPEC+ signals on production quotas. Regional navigation security statements from GCC foreign ministers may influence CDS spreads.
Equity flows in Aramco and DFM indices remain sensitive to crude volatility. Investors await updates on UAE tourism projects and Saudi blue-economy initiatives amid ongoing Red Sea risks. French military assets at Yanbu will stay under close watch for any escalation signals.
Other Economic Notes
Saudi Arabia’s war economy increasingly pressures Vision 2030 timelines as defense spending crowds out non-oil investment. UAE continues expanding tourism infrastructure in Abu Dhabi and Dubai to support 2026 visitor targets despite flight disruptions from regional tensions. Qatar’s rejection of external accusations highlights efforts to maintain diplomatic neutrality while advancing LNG capacity.
↓ p.2