GCC Macro Daily(Beta Mode)
Saudi Pipeline Restart Offsets Brent Slide
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| Saudi Aramco | 25.18 | -1.41% |
| MSCI Saudi | 36.40 | -1.47% |
| MSCI UAE | 20.14 | -0.27% |
| MSCI Qatar | 16.45 | -0.81% |
| MSCI Kuwait | 36.60 | -0.75% |
| Brent Crude | 96.47 | -8.37% |
| WTI Crude | 89.65 | -3.19% |
| Gold | 4,212.00 | +1.05% |
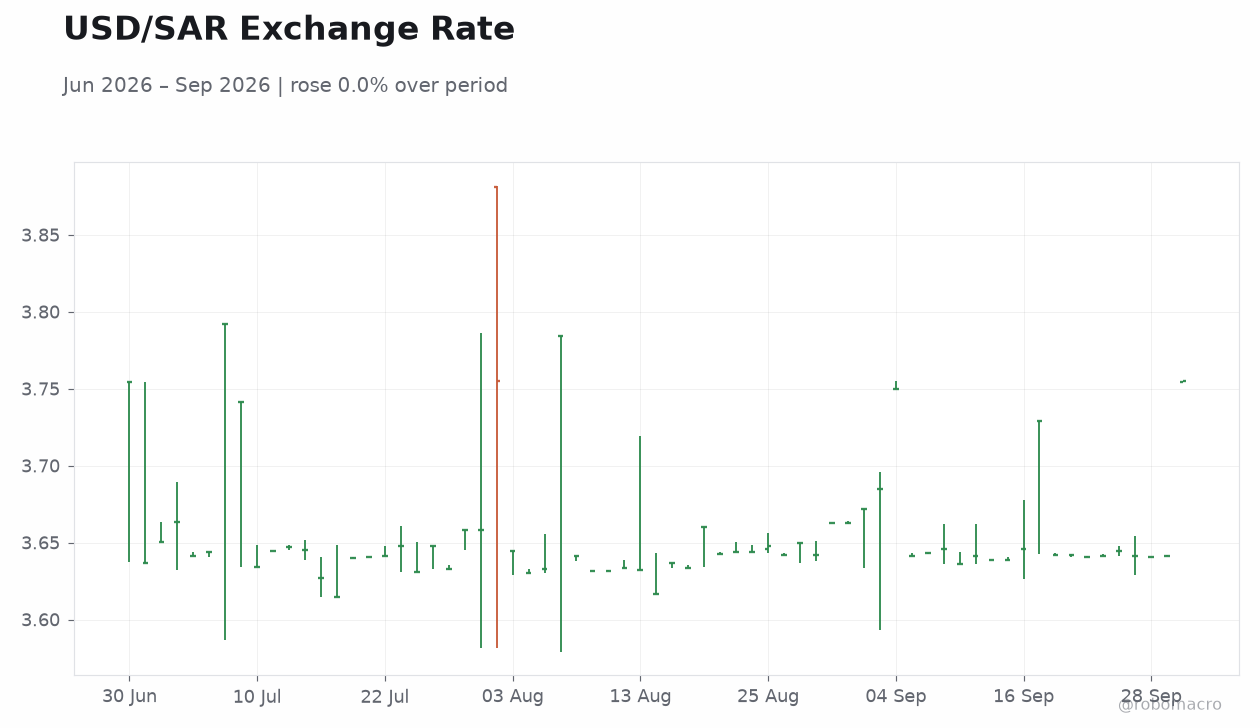
| USD/SAR | 3.75 | +3.11% |
| USD/AED | 3.67 | +0.03% |
| USD/KWD | 0.31 | -0.23% |
| Bitcoin | 83,172.47 | -0.40% |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
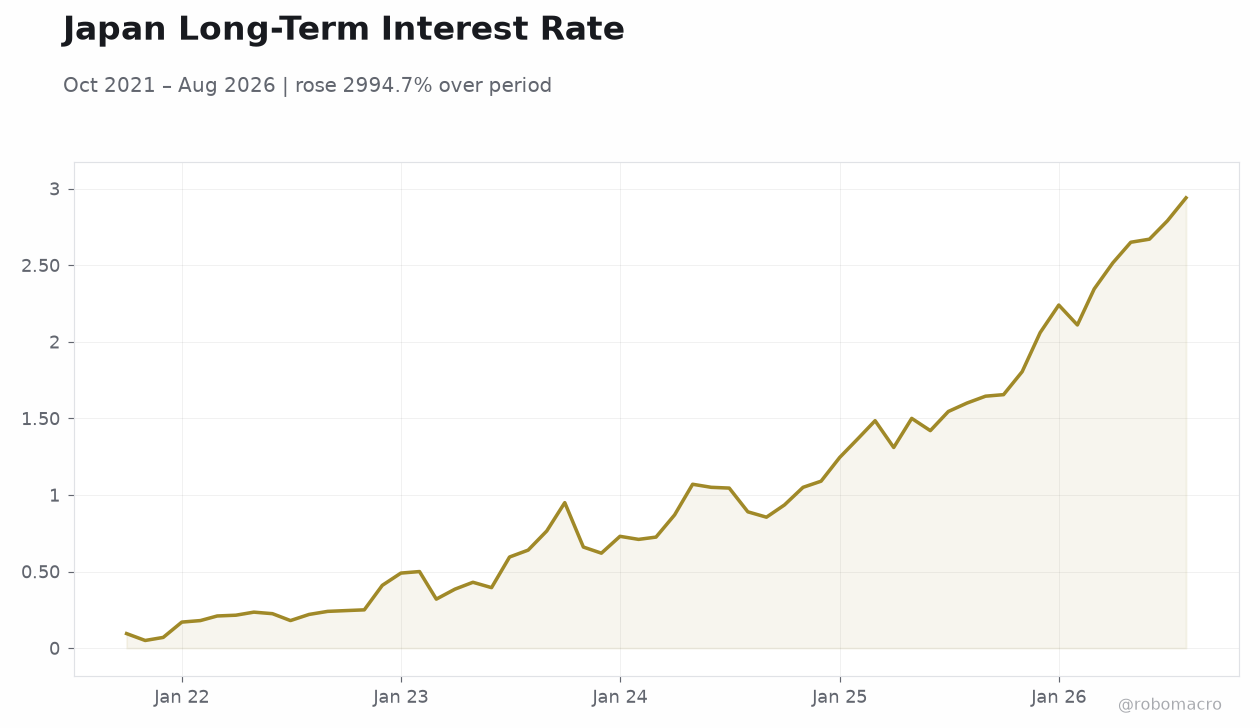 Japan Long-Term Interest Rate | Type: macro_line | Percent: 2.94 (2026-08-01) | Range: 0.05–2.94 | Trend(6pt): 0.095,0.41,0.71,1.31,2.67,2.94
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Saudi Arabia resumes East-West pipeline exports at 3.5 million barrels per day amid Red Sea risks.
- Brent crude drops 8.37% to 96.47 while GCC equities fall across the board.
- No macro data releases reported for any GCC member on September 28.
Yesterday's Recap
Saudi Arabia restarted oil exports through the East-West pipeline at a 3.5 million barrels per day rate to bypass Houthi threats in the Red Sea, a move that directly counters supply disruption risks tied to Iran-backed forces. Saudi Aramco shares fell 1.41% to 25.18 and MSCI Saudi declined 1.47% to 36.40 as energy names weighed on the index. MSCI UAE eased 0.27% to 20.14, MSCI Qatar dropped 0.81% to 16.45, and MSCI Kuwait slipped 0.75% to 36.60.
Brent crude plunged 8.37% to 96.47 while WTI fell 3.19% to 89.65, reflecting market relief from restored Saudi export capacity. Gold rose 1.05% to 4,212.00 as a safe-haven bid emerged. USD/SAR jumped 3.11% to 3.75 while USD/AED ticked up 0.03% to 3.67 and USD/KWD eased 0.23% to 0.31.
No PMI, CPI, GDP or fiscal prints emerged from Saudi Arabia, the UAE, Qatar, Kuwait, Oman or Bahrain, leaving fiscal balance assessments unchanged. Regional security posture stayed elevated after reports of a secret meeting between Israeli Prime Minister Benjamin Netanyahu and UAE President Sheikh Mohamed bin Zayed Al Nahyan in Abu Dhabi.
The Day Ahead
The calendar remains empty of scheduled releases across the six GCC states, shifting attention to geopolitical developments and their oil supply implications. UAE Vice President Mansour bin Zayed is scheduled to meet Saudi officials to coordinate responses to Houthi activity in Yemen. Qatari LNG force majeure extensions continue to affect Asian and European deliveries amid Hormuz concerns.
Traders will monitor Brent price reactions to the pipeline throughput increase and any fresh OPEC+ signals. Sovereign credit spreads and interbank rates such as SAIBOR and EIBOR are expected to stay anchored by USD peg mechanics. Regional equity flows may remain subdued until clearer visibility emerges on Red Sea security.
Saudi Arabia’s defense discussions with Bulgaria and climate talks with Australia add further diplomatic layers without immediate market impact.
Other Economic Notes
Oil price volatility directly pressures fiscal balances in Saudi Arabia and the UAE, where hydrocarbon revenues still dominate budgets despite Vision 2030 and UAE 2050 diversification efforts. Non-oil GDP growth in both economies continues to rely on tourism, logistics and manufacturing expansion, yet remains sensitive to regional security perceptions. ↓ p.2