RoboMacro ResearchAlso todaySee the FI Daily

GCC Macro Daily(Beta Mode)

October 18, 2026 robomacro.com

Houthi Strikes, Oil Slips Test GCC Resilience

Saudi Aramco25.28-0.39%
MSCI Saudi35.10-0.17%
MSCI UAE19.52-0.20%
MSCI Qatar15.60-0.22%

Market Snapshot

AssetLevelChange
Saudi Aramco25.28-0.39%
MSCI Saudi35.10-0.17%
MSCI UAE19.52-0.20%
MSCI Qatar15.60-0.22%
MSCI Kuwait34.90-0.81%
Brent Crude107.94-1.75%
WTI Crude97.51-3.85%
Gold4,199.60+0.44%
USD/SAR3.75+3.21%
USD/AED3.67+0.03%
USD/KWD0.31-0.76%
Bitcoin82,499.91+1.37%

Prior Economic Events

Data Prior Cons Actual
No events available
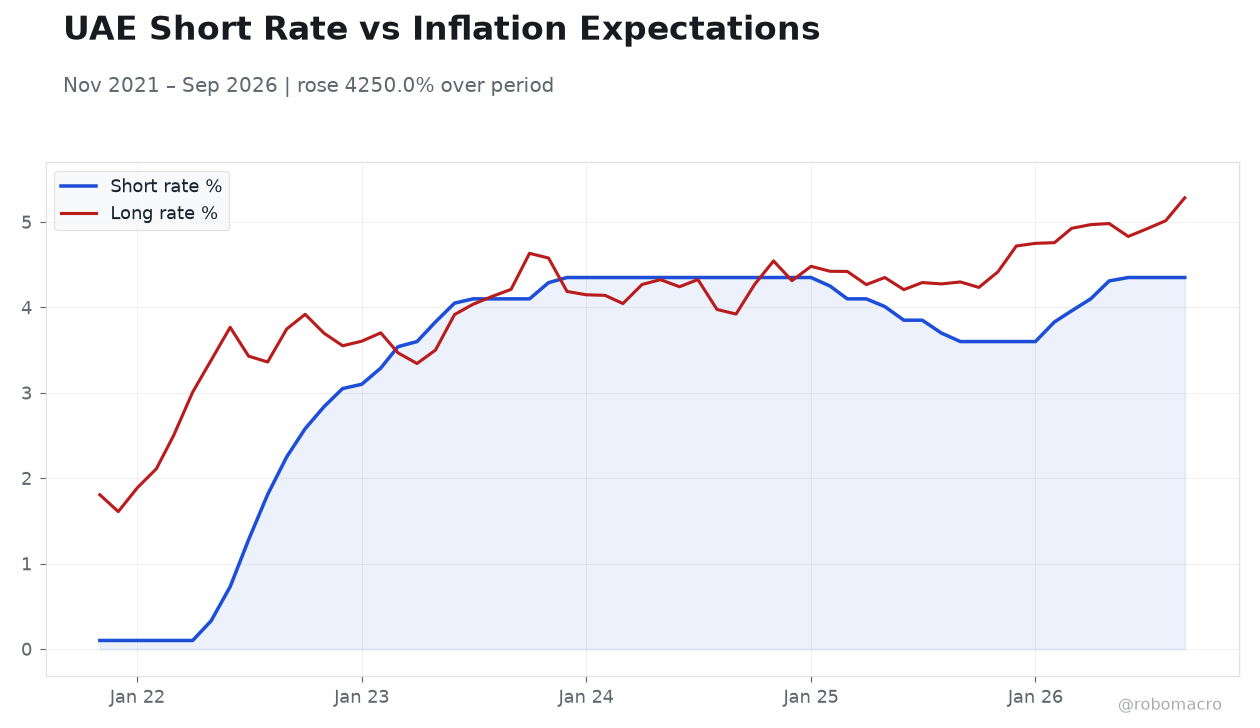
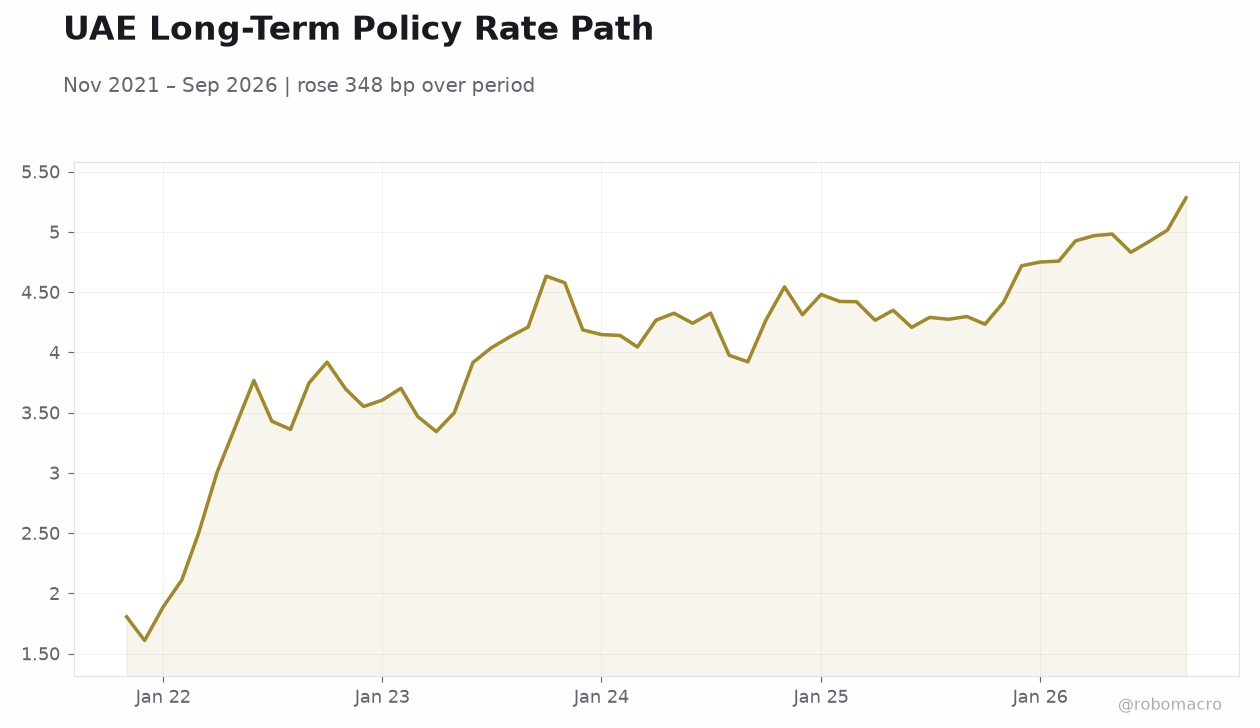
UAE Long-Term Policy Rate PathUAE Long-Term Policy Rate Path | Type: macro_line | Long rate %: 5.283 (2026-09-01) | Range: 1.609–5.283 | Trend(6pt): 1.806,3.604,4.045,4.35,4.919,5.283

Today's Economic Events

Data Prior Cons Time
No events available
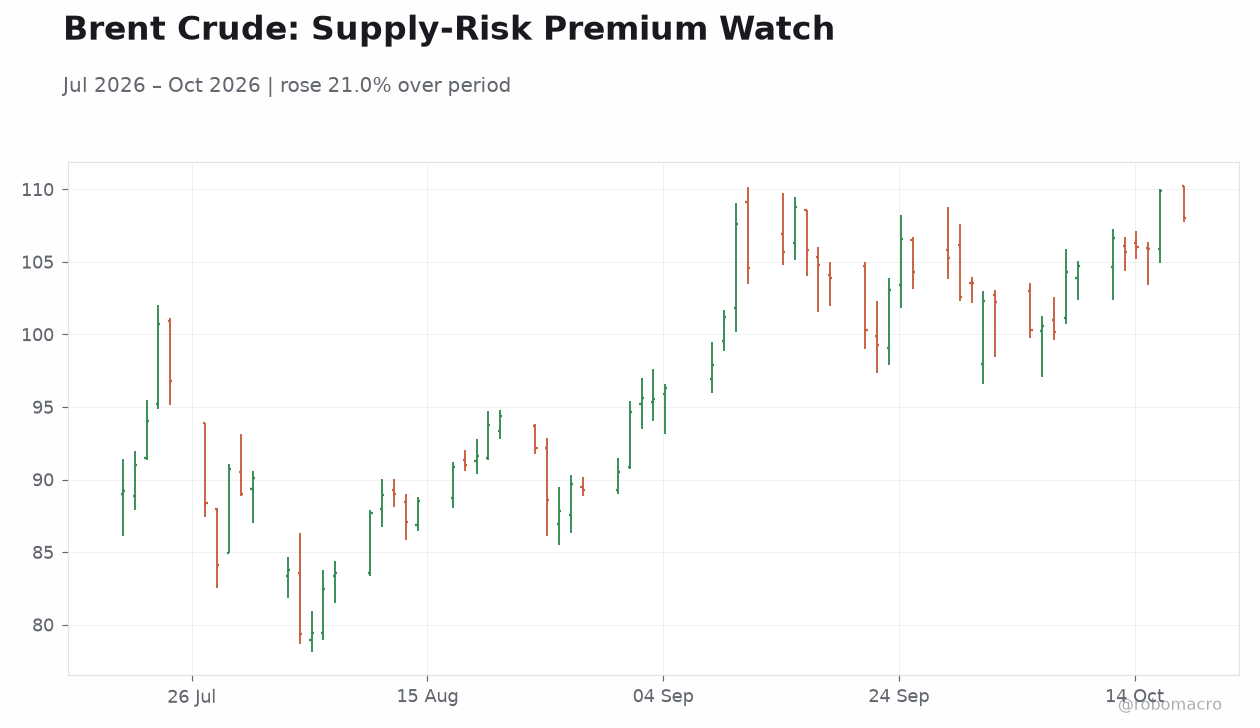
  • Houthi projectile hit a tanker off Saudi Arabia's coast and a helicopter crash killed two officers, keeping supply-risk premia elevated as Brent fell 1.75% to $107.94 and WTI slid 3.85% to $97.51.
  • SAMA Governor and Finance Minister Al-Jadaan publicly defended Saudi Arabia's stabilising role, saying the Kingdom's energy investments cushioned the global economy from the ongoing energy shock.
  • GCC equities closed broadly softer — MSCI Kuwait down 0.81%, MSCI Saudi off 0.17% — while gold gained 0.44% to $4,199.60 and Bitcoin added 1.37% to $82,499.91.

Yesterday's Recap

Saturday's session was dominated by security and logistics headlines rather than data, with no scheduled macro releases across the six-member Gulf Cooperation Council. A projectile struck a tanker off Saudi Arabia's coast, per UKMTO, reinforcing the pattern of episodic shipping disruption that has kept war-risk insurance costs elevated on Gulf routes and sustained a modest risk premium in Brent crude. Separately, a Saudi reconnaissance helicopter crash killed two officers, prompting condolences from Abu Dhabi and a meeting between Sheikh Mansour bin Zayed and Saudi Defence Minister Prince Khalid bin Salman — a signal of tight Saudi-UAE security coordination.

The flight disruption saga continued: Etihad extended Abu Dhabi-Saudi cancellations to October 24, and Australia urged travellers to reroute via UAE and Qatari hubs, underscoring the operational drag on regional aviation and tourism flows. On the policy front, SAMA's governor reiterated that the Saudi economy remains resilient despite the Middle East conflict, while Finance Minister Mohammed Al-Jadaan argued Saudi investments had mitigated the energy shock's global impact — a deliberate narrative aimed at reassuring foreign investors holding GCC sovereign paper. Markets reflected the mixed tone: MSCI Kuwait lagged at -0.81%, MSCI Qatar eased 0.22%, MSCI UAE slipped 0.20%, and MSCI Saudi shed 0.17%, while Saudi Aramco closed at 25.28, down 0.39%.

Brent's 1.75% retreat to $107.94 and WTI's sharper 3.85% drop to $97.51 suggest demand concerns are starting to compete with supply-risk headlines.

The Day Ahead

Sunday opens the trading week with no scheduled macro prints across the GCC, leaving price action hostage to geopolitics and oil. Attention stays on shipping traffic through the Red Sea and Strait of Hormuz after Saturday's tanker strike, with any escalation likely to lift Brent and GCC sovereign CDS in tandem. Watch for follow-through on Etihad's extended Saudi flight cancellations and further advisories from foreign carriers, which would signal prolonged aviation disruption.

Regional equity markets resume after the weekend, and the question is whether Kuwait's outsized Friday decline extends or stabilises as bargain-hunters emerge. ↓ p.2

Page 1

GCC Macro Daily(Beta Mode)

October 18, 2026 robomacro.com
UAE Short Rate vs Inflation Expectations UAE Short Rate vs Inflation Expectations | Type: macro_line | Short rate %: 4.35 (2026-09-01) | Range: 0.1–4.35 | Trend(5pt): 0.1,3.1,4.35,4.01,4.35 | Long rate %: 5.283 (2026-09-01) | Range: 1.609–5.283 | Trend(6pt): 1.806,3.604,4.045,4.35,4.919,5.283
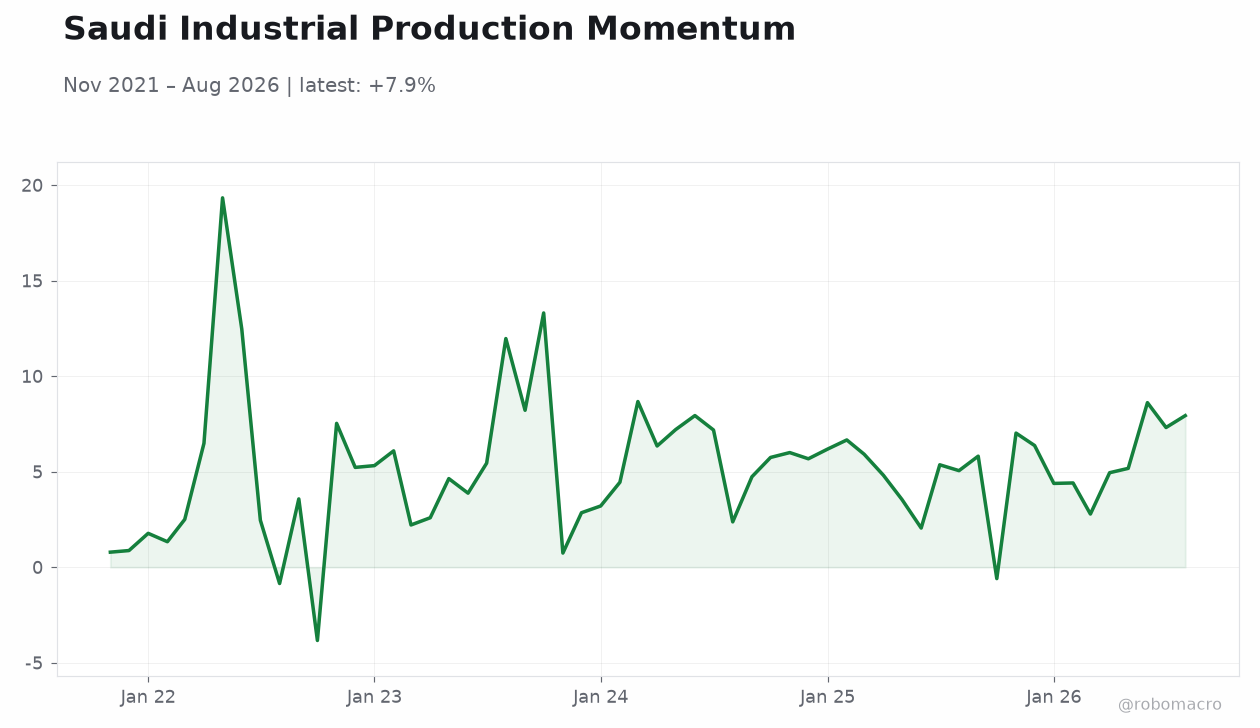
Saudi Industrial Production Momentum Saudi Industrial Production Momentum | Type: macro_line | Index (YoY %): 7.935 (2026-08-01) | Range: -3.835–19.33 | Trend(6pt): 0.7882,5.318,8.671,3.545,7.313,7.935
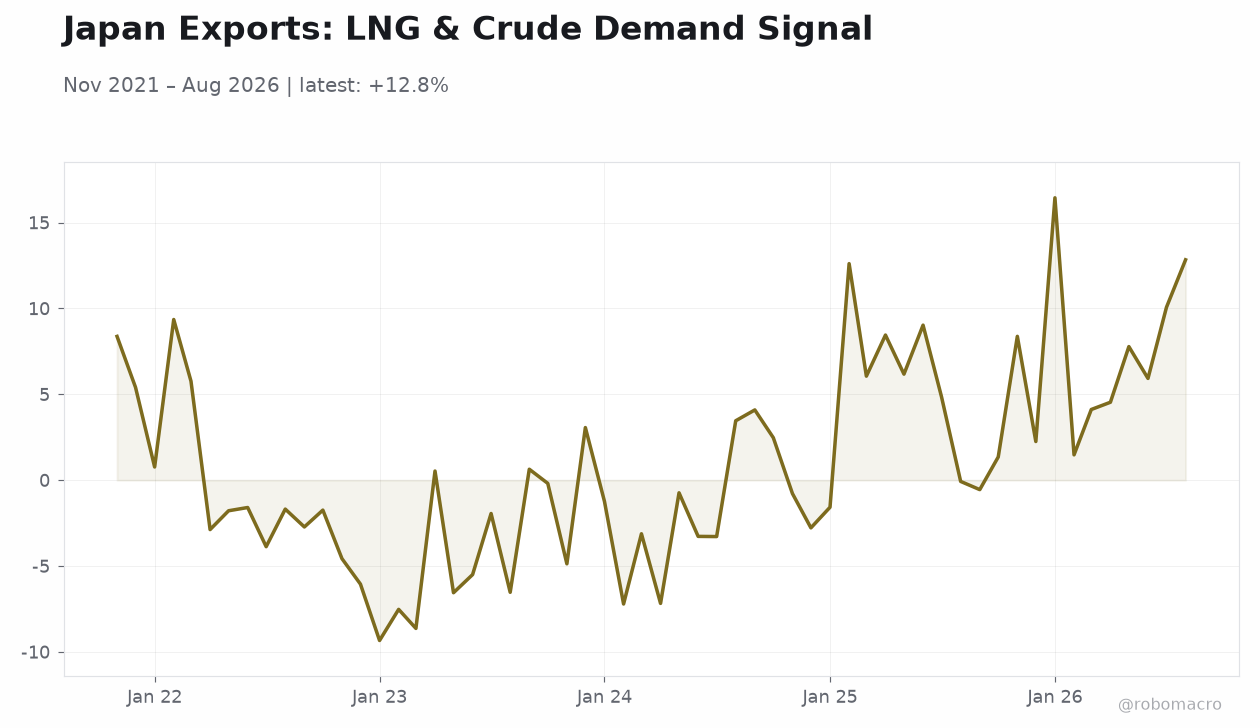
Japan Exports: LNG & Crude Demand Signal Japan Exports: LNG & Crude Demand Signal | Type: macro_line | Exports USD mn: 12.83 (2026-08-01) | Range: -9.335–16.44 | Trend(6pt): 8.371,-9.335,-3.122,6.175,10.07,12.83
Brent Crude: Supply-Risk Premium Watch Brent Crude: Supply-Risk Premium Watch | Type: market_hloc | Brent USD/bbl: 108 (2026-10-18) | Range: 79.36–109.9 | Trend(5pt): 89.22,88.91,95.63,104.3,108

The Day Ahead (continued)

Any OPEC+ commentary or jawboning from Gulf energy ministers would move the complex, given WTI's sharp Friday slide. Qatari and UAE diplomatic channels remain active after high-level talks, with the Qatar-UAE relationship a quiet positive for cross-border investment flows.

Other Economic Notes

Saudi Arabia's cybersecurity market grew 10.7% to $4.35bn, a datapoint underscoring how Vision 2030's digital-economy push is generating tangible non-oil activity even as hydrocarbon revenues dominate the fiscal picture. The Qatari and UAE foreign ministries' engagement on regional de-escalation supports the investment-climate narrative both sovereigns have cultivated. Qatar's offer of a comprehensive plan to ease Lebanon's electricity crisis illustrates how Gulf surplus countries are converting energy wealth into regional influence and export opportunities.

Meanwhile, Chinese firms' willingness to build rail tunnels in Qatar despite the Iran conflict signals continued foreign direct investment appetite in Gulf infrastructure, a key pillar of diversification strategies.

Global Macro News

The IMF's projection that Japan will fall to sixth in world GDP rankings behind India and Britain highlights the shifting global growth mix that Gulf exporters are recalibrating toward — Asia's rising share of crude demand remains the structural anchor for GCC terms of trade. ↓ p.3

Sponsored by Arbitrage Search
Page 2

GCC Macro Daily(Beta Mode)

October 18, 2026 robomacro.com

Continuation

Global Macro News (continued)

Iran's warning that it would retaliate swiftly if the US targets its energy facilities keeps the Strait of Hormuz risk premium alive; roughly a fifth of global oil transits the strait, making Tehran's rhetoric a direct input into Brent's forward curve and GCC fiscal breakevens. QNB's observation that Poland's reclassification as a developed market reflects economic progress is a reminder that emerging-market index flows are fluid, with GCC markets still lobbying for upgraded status in global benchmarks. The energy shock's global footprint — acknowledged by Al-Jadaan — cuts both ways for the Gulf: higher prices boost export receipts but complicate inflation dynamics in import-dependent sectors.

Bitcoin's 1.37% gain to $82,499.91 and gold's rise to $4,199.60 suggest investors retain appetite for alternative stores of value amid geopolitical noise, a pattern that has historically correlated with GCC sovereign wealth fund allocation shifts.

GCC Central Banks Watch

No policy decisions are scheduled at SAMA, CBUAE, QCB, CBK, CBO, or CBB this week, leaving the six central banks in observation mode as they track the Fed's next move under their respective dollar pegs. The sharp 3.21% move in USD/SAR to 3.75 merits scrutiny — the riyal's peg has been stable for decades, and any sustained deviation from 3.75 would signal funding pressures or speculative positioning, though a single-day print likely reflects data timing rather than regime change. SAMA's governor used the weekend to reinforce confidence in the Kingdom's macro framework, implicitly defending the peg's credibility amid conflict-related outflows.

USD/AED held at 3.6735, consistent with the dirham's tight band, while USD/KWD eased 0.76% to 0.3055 — Kuwait's basket peg gives CBK modest flexibility, and the dinar's firmness against a softer dollar backdrop is mechanically supportive. Interbank rates across the region should track the Fed's pause; watch SAIBOR and EIBOR for signs of liquidity tightening if oil receipts slow with WTI below $100. With all six currencies anchored to the dollar, the ECB-Fed divergence debate is largely academic for GCC policymakers — their mandate is to shadow the Fed, and the current consensus that the Fed is on hold through year-end allows the region's banks to maintain ample liquidity.

Reserve adequacy remains a strength across the six, with Saudi Arabia's net foreign assets and the UAE's and Qatar's large sovereign buffers providing ample cover against any speculative attack scenarios that Middle East escalation could provoke. The key watch item this week is whether the tanker strike prompts CBK or SAMA to comment on funding conditions, a signal that would move the forwards market.
Sponsored by Arbitrage Search
Page 3