GCC Macro Daily(Beta Mode)
Houthi Escalation Hits Saudi Assets, FII Delayed
Market Snapshot
| Asset | Level | Change |
|---|---|---|
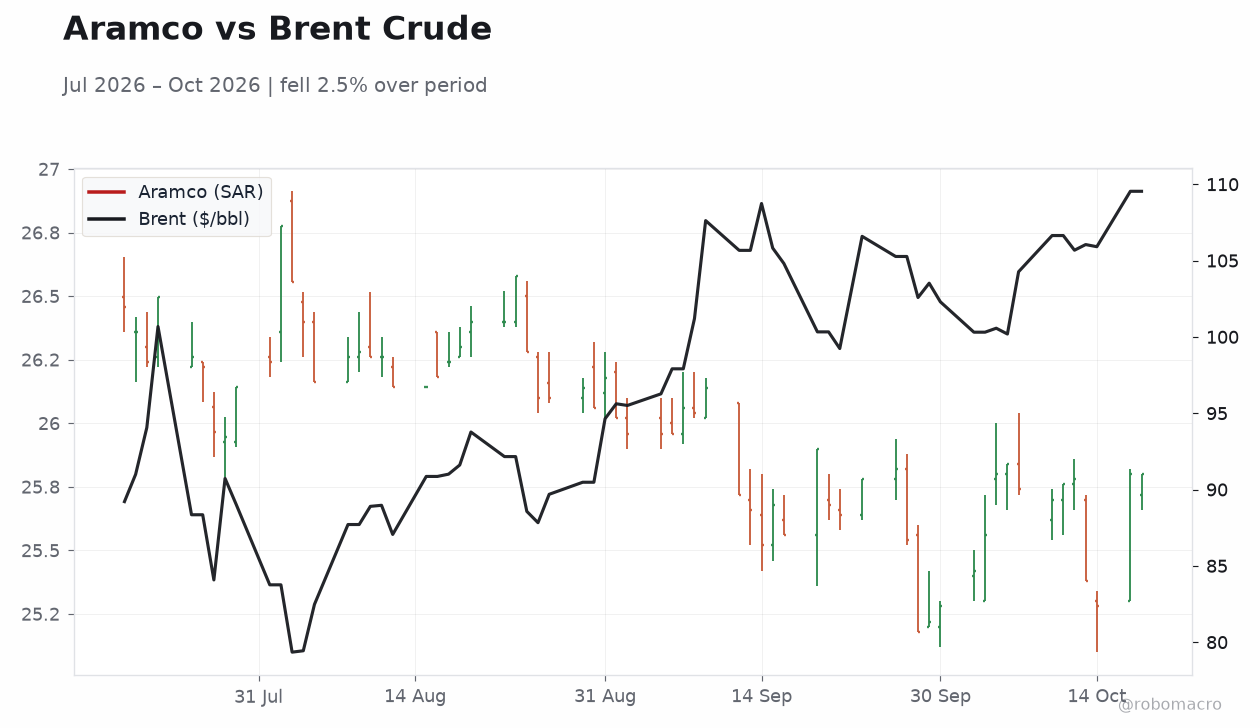
| Saudi Aramco | 25.48 | -1.24% |
| MSCI Saudi | 34.78 | -1.02% |
| MSCI UAE | 19.68 | +0.36% |
| MSCI Qatar | 15.29 | -0.16% |
| MSCI Kuwait | 35.04 | +0.44% |
| Brent Crude | 110.47 | +0.84% |
| WTI Crude | 99.26 | -4.24% |
| Gold | 4,135.10 | -0.60% |
| USD/SAR | 3.75 | +2.86% |
| USD/AED | 3.67 | +0.03% |
| USD/KWD | 0.31 | -0.82% |
| Bitcoin | 82,670.65 | +1.00% |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
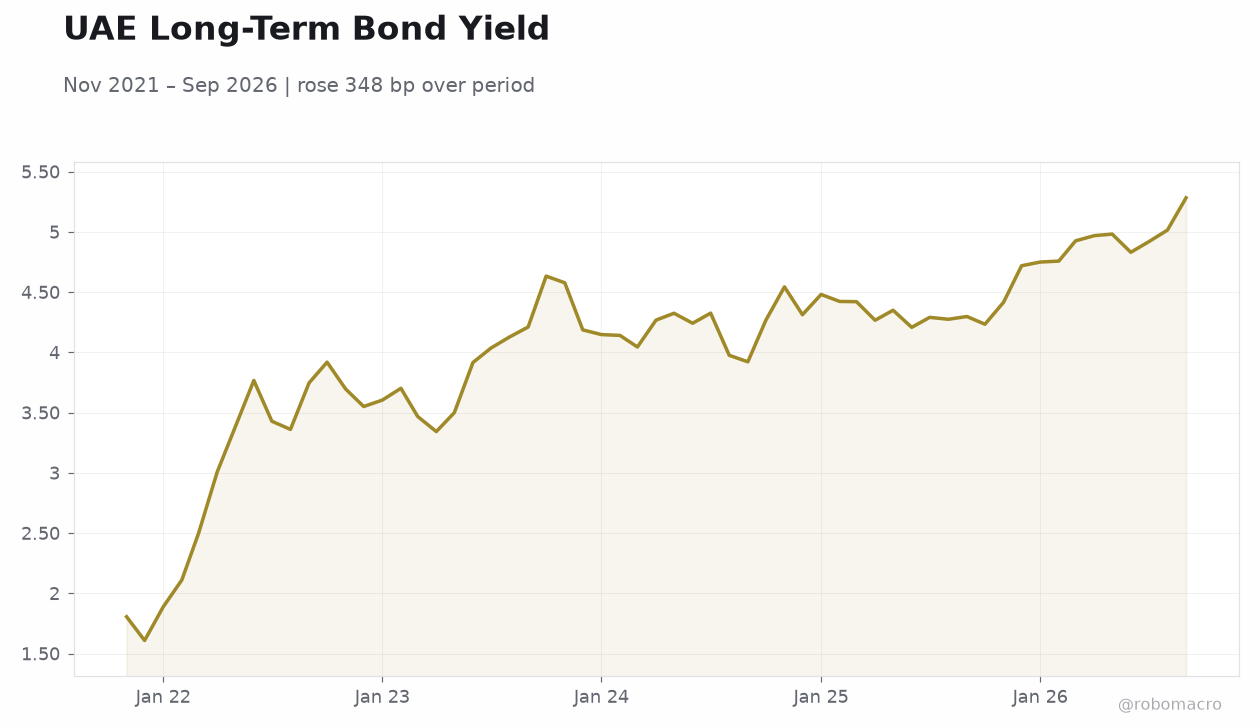 UAE Long-Term Bond Yield | Type: macro_line | UAE 10Y Yield (%): 5.283 (2026-09-01) | Range: 1.609–5.283 | Trend(6pt): 1.806,3.604,4.045,4.35,4.919,5.283
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Houthi attacks force Saudi Arabia to postpone its flagship FII investment conference to 2027, weighing on Saudi equities and Aramco
- Brent crude firms above $110/bbl on supply-risk premium, though WTI's 4.2% drop signals unusual divergence
- UAE markets outperform (MSCI UAE +0.36%, Kuwait +0.44%) as Dubai IPO activity signals continued non-oil momentum
Yesterday's Recap
Saudi Arabia dominated the macro narrative as escalating Houthi attacks prompted Riyadh to postpone its flagship Future Investment Initiative ("Davos in the Desert") conference to 2027, a significant reputational and FDI signal. Saudi equities bore the brunt: MSCI Saudi fell 1.02% and Saudi Aramco dropped 1.24% to SAR 25.48. Finance Minister Mohammed Al-Jadaan noted the Kingdom's economy remains resilient despite regional uncertainty, while the UK announced additional defensive military support to Saudi Arabia.
By contrast, UAE and Kuwait markets posted modest gains — MSCI UAE +0.36% and MSCI Kuwait +0.44% — with Dubai's DIP Holding IPO framed as the UAE's first listing of 2026 and a confidence signal. Qatar was roughly flat (MSCI Qatar -0.16%). Regional carriers extended disruptions: Etihad cancelled Abu Dhabi–Saudi flights through October 24, and Qatar Airways cut Jeddah flights while extending Riyadh and Dammam cancellations.
No official GCC macro data releases printed on the calendar.
The Day Ahead
The calendar is empty for October 20, with no scheduled GCC statistical releases across the six member states. Market attention will therefore center on oil price direction and any further Houthi-related headlines affecting Red Sea shipping and Saudi infrastructure risk. Investors will watch whether Brent's supply-risk premium holds above $110/bbl and whether the unusual Brent–WTI divergence narrows.
Qatar's planned two power plants for Lebanon and a 20-year LNG deal will draw energy-sector scrutiny. French President Macron's Gulf tour — now in Kuwait after the UAE — keeps energy and investment diplomacy in focus. Regional airline schedule updates remain a live indicator of security conditions.
Other Economic Notes
Fitch analysis highlighted that Egypt, the UAE, and Saudi Arabia are drawing on different buffers to weather regional war fallout, underscoring divergent fiscal cushions across the region. Saudi Arabia's energy investments were credited by its finance minister with helping cushion the global economy from shocks. The UAE continued deepening non-oil ties, concluding a China visit focused on energy, advanced technologies, and sustainable transport, while Emirates NBD became the first MENA bank to run OpenAI models locally.
↓ p.2