GCC Macro Daily(Beta Mode)
Houthi Strike Hits Aramco Pipeline; Markets Diverge
Market Snapshot
| Asset | Level | Change |
|---|---|---|
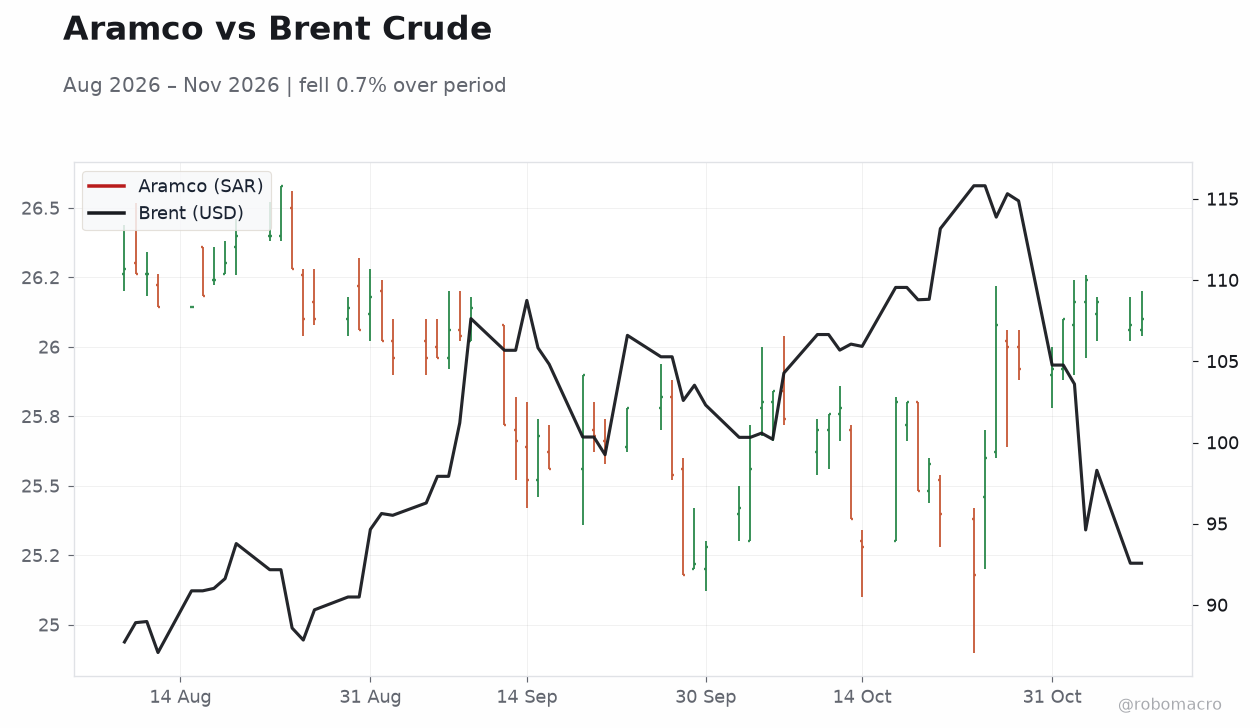
| Saudi Aramco | 25.60 | -1.92% |
| MSCI Saudi | 35.58 | +0.35% |
| MSCI UAE | 20.34 | +0.25% |
| MSCI Qatar | 17.82 | -0.61% |
| MSCI Kuwait | 36.08 | -0.92% |
| Brent Crude | 91.93 | -0.69% |
| WTI Crude | 86.28 | -0.66% |
| Gold | 4,052.00 | -1.52% |
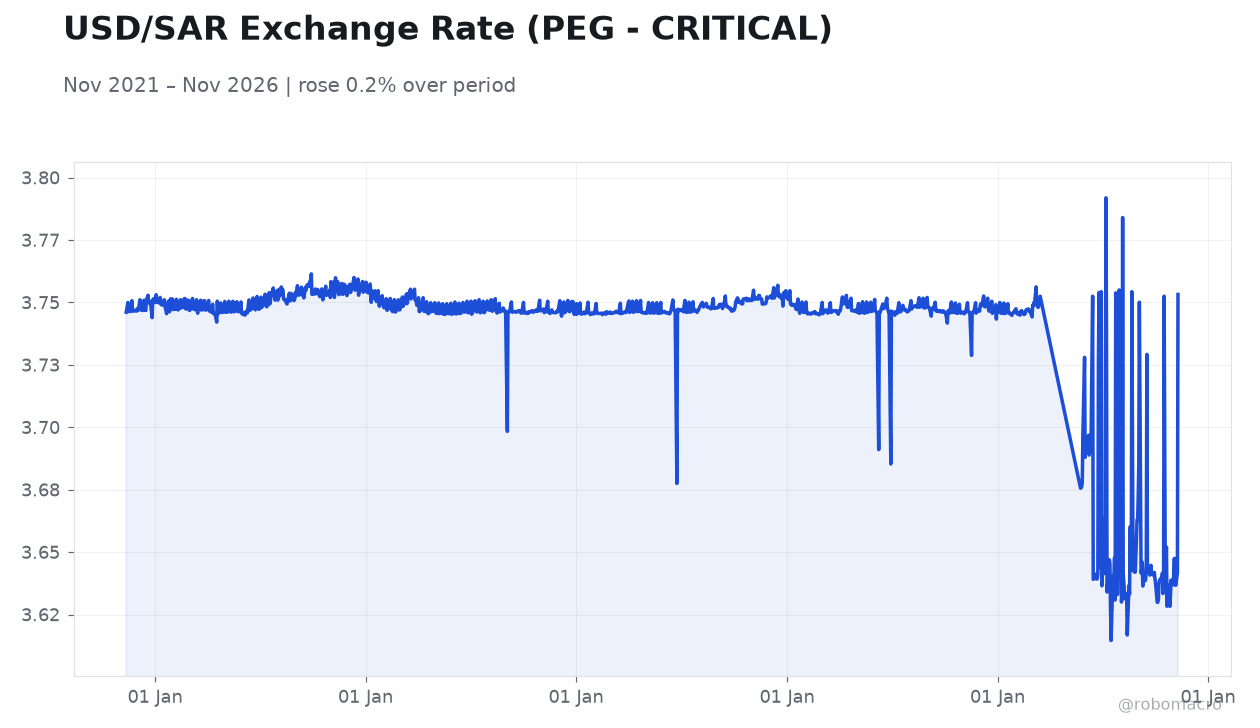
| USD/SAR | 3.75 | +3.00% |
| USD/AED | 3.67 | +0.03% |
| USD/KWD | 0.31 | -0.05% |
| Bitcoin | 73,488.16 | -2.31% |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
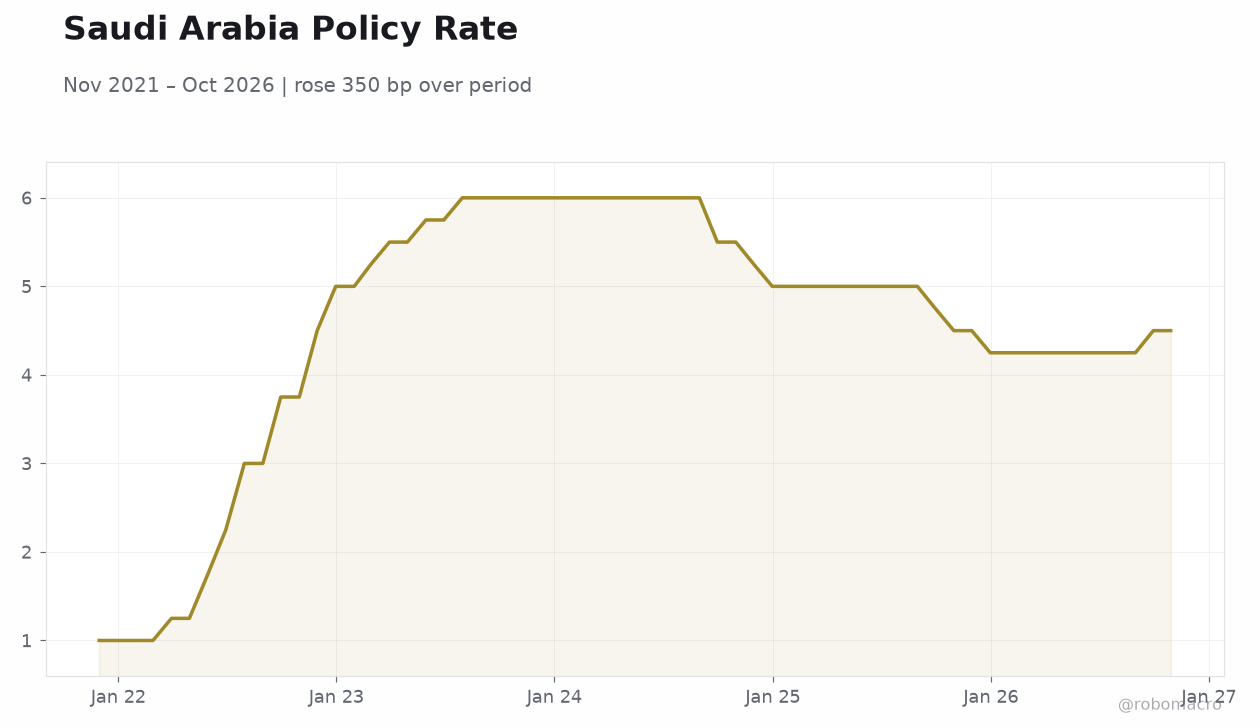 Saudi Arabia Policy Rate | Type: macro_line | Saudi policy rate (%): 4.5 (2026-10-29) | Range: 1–6 | Trend(5pt): 1,5.25,6,5,4.5
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Houthi missile attack targets Saudi East-West pipeline and Aramco facility; operations reported unaffected but security risk premium persists
- Saudi equities outperform (+0.35%) while Kuwait (-0.92%) and Qatar (-0.61%) lag; Brent softens 0.69% to $91.93 despite supply-risk headlines
- Qatar PM briefs G7 and Riyadh on Iran mediation; GCC Secretary-General welcomes Russia-Ukraine-US talks in Abu Dhabi
Yesterday's Recap
Saudi Arabia dominated the macro and security narrative as Houthi forces targeted the Kingdom's East-West pipeline and an Aramco building in Riyadh, with missiles intercepted over Saudi territory and emergency measures activated. Saudi authorities confirmed pipeline operations were unaffected, though the attack briefly stoked supply-risk concerns. Saudi equities were resilient, with the MSCI Saudi index gaining 0.35% even as Saudi Aramco shares fell 1.92% to SAR 25.60.
Regional bourses diverged: the MSCI UAE rose 0.25% on record non-oil trade of $802bn, while Kuwait's MSCI index dropped 0.92% and Qatar's fell 0.61%. Brent crude eased 0.69% to $91.93 and WTI slipped 0.66% to $86.28, suggesting markets judged the pipeline disruption contained. Gold retreated 1.52% to $4,052/oz, and Bitcoin fell 2.31% to $73,488.
The USD/SAR printed at 3.75 with a 3.00% daily change reflecting the conventional peg quotation convention rather than a true riyal move.
The Day Ahead
No scheduled GCC macro data releases appear on the calendar for November 10, leaving markets to trade on geopolitical headlines and oil price direction. Investors will watch for any official Saudi statement on pipeline integrity and Aramco export flows through the Red Sea and Gulf terminals. Qatar's Prime Minister continues his briefing tour to the G7 and Saudi leadership on Iran mediation progress, a diplomatic thread that could sway regional risk sentiment.
UAE flight operations remain disrupted, with Emirates, Etihad, flydubai and Air Arabia reporting cancellations and delays, a modest drag on tourism and logistics activity. Regional equity desks will also monitor whether the Kuwait and Qatar underperformance extends or reverses.
Other Economic Notes
The UAE's non-oil foreign trade reached $802bn with record exports, reinforcing the diversification narrative underpinning Abu Dhabi and Dubai's growth trajectory. Saudi Arabia climbed three places in financial inclusion rankings, a quiet but meaningful marker of Vision 2030's financial deepening. The UAE property boom accelerated as IREIS 2026 opened in Abu Dhabi, with real estate remaining a key non-oil growth engine.
↓ p.2