GCC Macro Daily(Beta Mode)
Gulf Markets Slip as Brent Eases, Risks Linger
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| Saudi Aramco | 26.40 | +1.46% |
| MSCI Saudi | 36.01 | -0.33% |
| MSCI UAE | 20.92 | -0.90% |
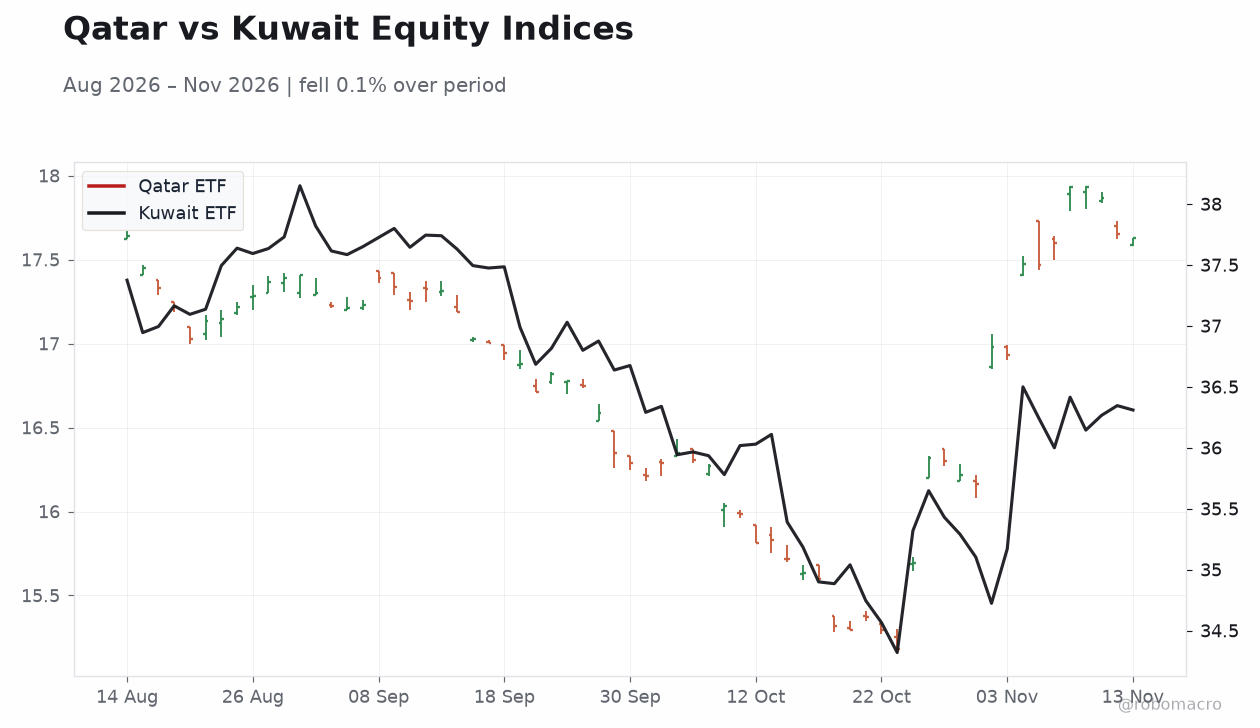
| MSCI Qatar | 17.63 | -0.11% |
| MSCI Kuwait | 36.31 | -0.10% |
| Brent Crude | 95.20 | -0.67% |
| WTI Crude | 88.13 | -0.49% |
| Gold | 3,888.20 | +0.05% |
| USD/SAR | 3.75 | +2.03% |
| USD/AED | 3.67 | +0.03% |
| USD/KWD | 0.31 | -0.20% |
| Bitcoin | 65,044.24 | +1.43% |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
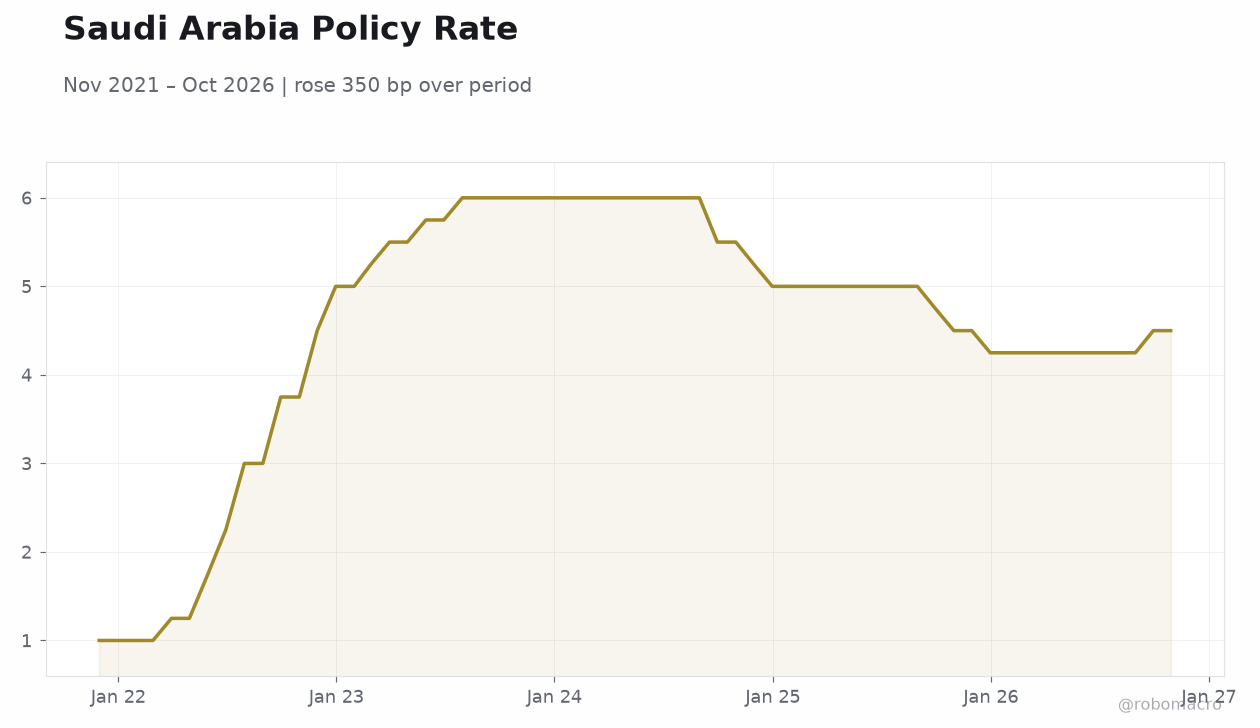 Saudi Arabia Policy Rate | Type: macro_line | Policy Rate (%): 4.5 (2026-10-29) | Range: 1–6 | Trend(5pt): 1,5.25,6,5,4.5
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Saudi equities diverged as Aramco gained 1.46% while the MSCI Saudi index fell 0.33%, with Brent crude softening 0.67% to $95.20.
- Regional bourses were broadly lower — UAE off 0.90%, Qatar down 0.11%, Kuwait down 0.10% — as geopolitical risk premia persisted.
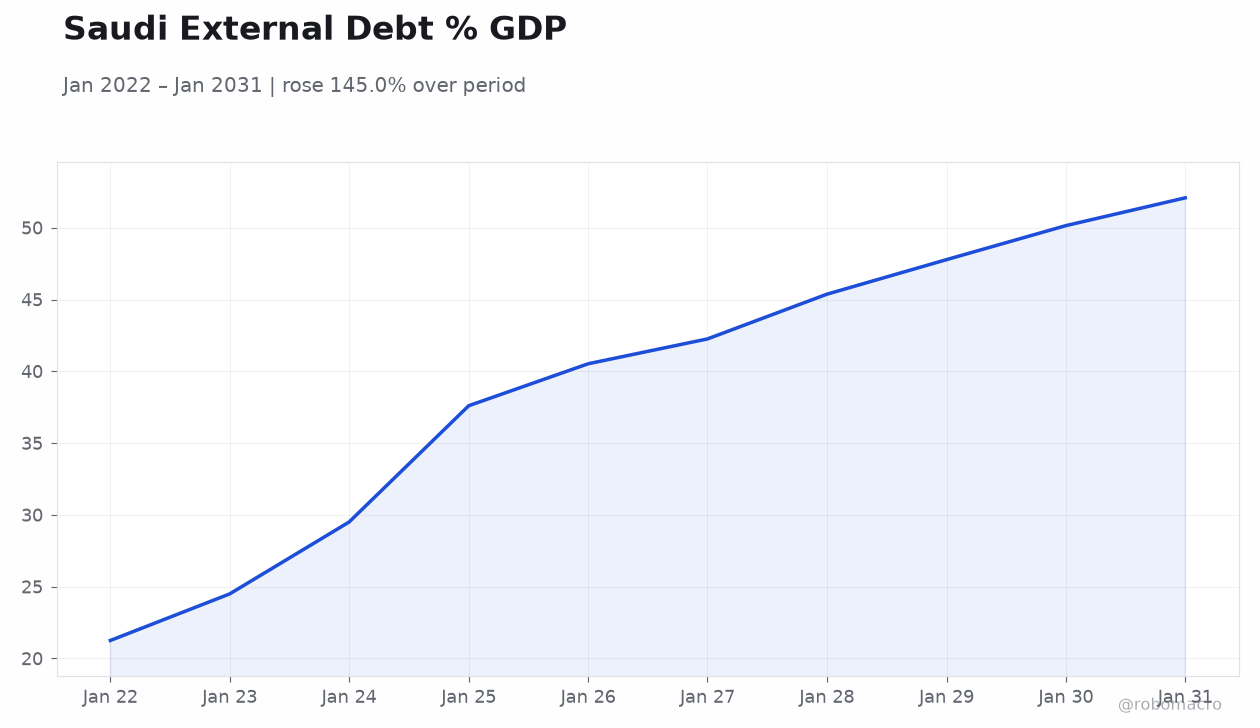
- Moody's expects Saudi real GDP to rebound in 2027 on recovering oil output, while Riyadh confirmed new FII dates and launched a foreign-investor platform.
Yesterday's Recap
Gulf markets closed mixed-to-lower on November 14, with the MSCI UAE index the weakest performer at -0.90% and Qatar and Kuwait each easing roughly 0.1%. Saudi Arabia's equity complex diverged internally: Saudi Aramco rose 1.46% to SAR 26.40, but the MSCI Saudi gauge slipped 0.33%, suggesting profit-taking in non-energy names. Brent crude settled 0.67% lower at $95.20 and WTI fell 0.49% to $88.13, trimming the fiscal tailwind that underpins GCC budget math.
Gold was essentially flat at $3,888.20, while Bitcoin gained 1.43%. On the FX side, USD/SAR printed at 3.75 with a 2.03% move — a reading that reflects quote convention rather than any peg stress, as the riyal remains firmly anchored. News flow was dominated by Saudi Arabia: Moody's projected a 2027 rebound in the Kingdom's economy as oil output recovers, Riyadh confirmed new dates for the Future Investment Initiative, and the government launched a business platform aimed at foreign investors.
The Day Ahead
The calendar is empty across all six GCC markets for November 15, with no scheduled statistical releases in Saudi Arabia, the UAE, Qatar, Kuwait, Oman, or Bahrain. Attention therefore shifts to secondary market flows and oil price direction, with Brent's hold above $95 the key variable for regional sentiment. Traders will watch whether the UAE's underperformance extends or stabilizes, and whether Aramco's relative strength signals rotation into defensive energy names.
With no domestic prints to anchor positioning, GCC desks will take their cue from global risk appetite and any headlines on Strait of Hormuz security. Monday's session should bring a fuller regional agenda.
Other Economic Notes
Saudi Arabia's non-oil diversification push continues to draw institutional attention, with the new foreign-investor platform and confirmed FII dates signaling a renewed push for FDI. In the UAE, presidential-level discussions on national growth plans and trade ties point to continued emphasis on non-hydrocarbon partnerships. Qatar signed a mutual defense agreement with Türkiye, a development that reinforces Doha's security alignment amid regional tensions.
Across the Gulf, gold flows remain a quiet theme, with the UAE cited as the main destination for bullion smuggled out of Sudan and other conflict zones. ↓ p.2