GCC Macro Daily(Beta Mode)
Oil Slump Tests GCC Fiscal Math
Market Snapshot
| Asset | Level | Change |
|---|---|---|
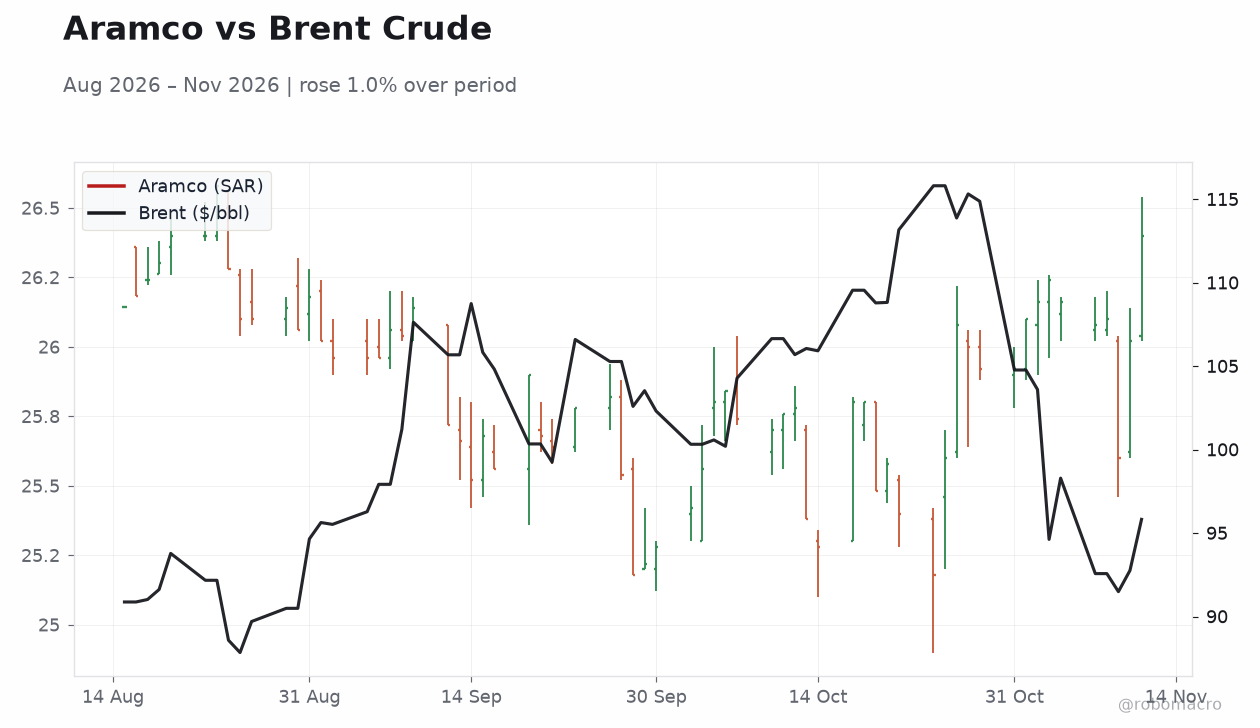
| Saudi Aramco | 26.40 | +1.46% |
| MSCI Saudi | 36.01 | -0.33% |
| MSCI UAE | 20.92 | -0.90% |
| MSCI Qatar | 17.63 | -0.11% |
| MSCI Kuwait | 36.31 | -0.10% |
| Brent Crude | 91.75 | -4.27% |
| WTI Crude | 85.09 | -3.92% |
| Gold | 3,863.50 | -0.59% |
| USD/SAR | 3.75 | -0.00% |
| USD/AED | 3.67 | +0.03% |
| USD/KWD | 0.31 | -0.70% |
| Bitcoin | 64,754.47 | -0.84% |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
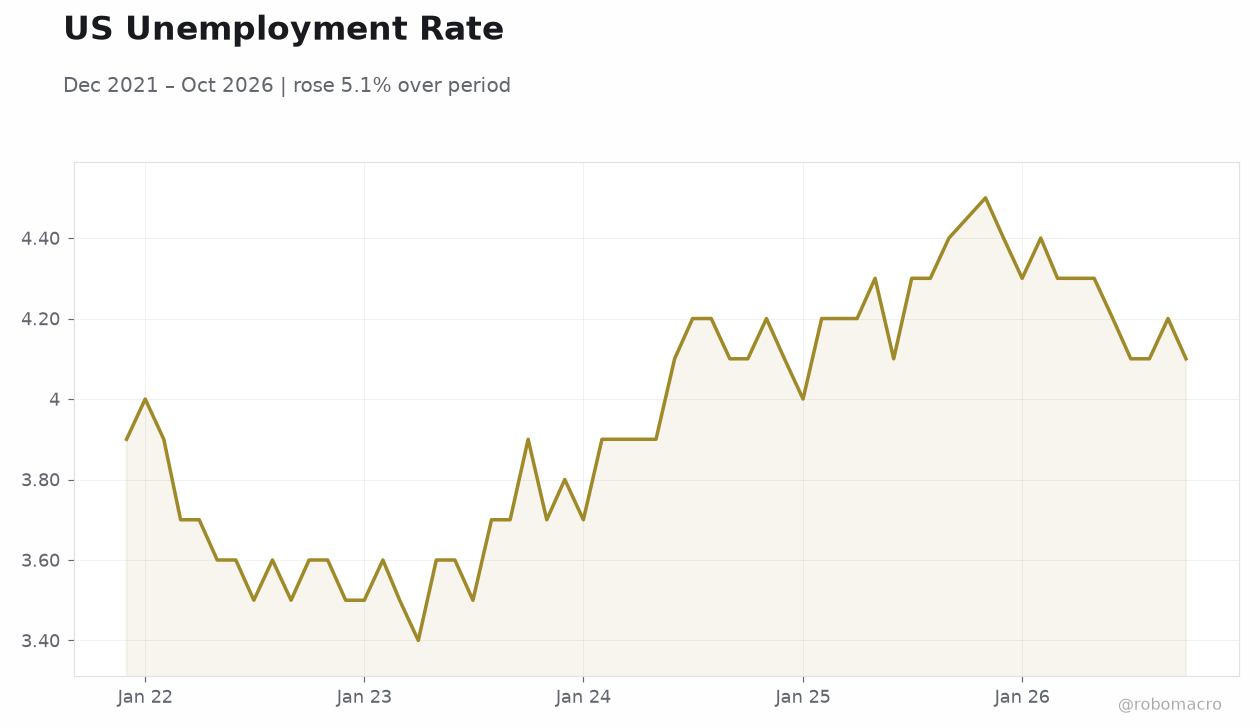 US Unemployment Rate | Type: macro_line | Unemployment rate (%): 4.1 (2026-10-01) | Range: 3.4–4.5 | Trend(6pt): 3.9,3.6,3.9,4.1,4.2,4.1
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Brent's 4.3% single-day slide to $91.75 is the dominant macro shock for all six GCC sovereigns, pressuring fiscal breakevens and equity sentiment simultaneously.
- Saudi October CPI printed at 1.7% y/y, keeping real policy rates deeply restrictive given the SAR peg to a Fed on hold.
- Qatar's GDP contraction eased to 12% as gas output recovers, while Moody's projects a 2027 Saudi rebound on oil output normalization.
Yesterday's Recap
Saudi Arabia's October CPI came in at 1.7% y/y, a benign print that keeps SAMA's real policy stance firmly restrictive with the riyal pinned at 3.75. Brent collapsed 4.27% to $91.75 and WTI fell 3.92% to $85.09, the sharpest one-day crude move of the month, dragging GCC risk assets lower across the board. MSCI Saudi slipped 0.33% to 36.01, MSCI UAE dropped 0.90% to 20.92, MSCI Qatar eased 0.11% to 17.63 and MSCI Kuwait lost 0.10% to 36.31, a broad but shallow equity drawdown.
Saudi Aramco bucked the trend, rising 1.46% to SAR 26.40, likely on defensive positioning and dividend yield appeal. Qatar's GDP contraction eased to 12% as gas production recovered, per AGBI, a meaningful inflection for the region's second-largest economy. The Kuwaiti dinar strengthened 0.70% against the dollar to 0.31, reflecting the basket peg's composition and oil-linked flows.
Regional headlines remained dominated by de-escalation diplomacy, with Saudi and Qatari foreign ministers conferring on reducing regional tensions.
The Day Ahead
The calendar is empty across all six GCC markets for November 16, with no scheduled statistical releases in Saudi Arabia, the UAE, Qatar, Kuwait, Oman or Bahrain. With no domestic prints to anchor sentiment, GCC desks will trade the crude tape and global risk appetite, making Brent's follow-through the single most watched variable. Watch for any unscheduled Saudi or UAE official commentary on fiscal strategy given the oil slide, and monitor TAQA, ADNOC and Aramco secondary-market flows for sovereign wealth fund signals.
Qatar's gas recovery narrative and any follow-up on the Türkiye-Qatar defense pact will be in focus for Doha positioning. Kuwait's interbank market bears watching after the dinar's 0.70% move, which may prompt CBK liquidity management. Tuesday brings the first opportunity for regional PMI and credit commentary to reset the narrative.
Other Economic Notes
Saudi Arabia confirmed new dates for its Future Investment Initiative, signaling continued commitment to the foreign-capital pipeline despite regional uncertainty. Riyadh also launched a new business platform aimed at streamlining foreign investor entry, a concrete Vision 2030 delivery step. Moody's projects the Saudi economy rebounding in 2027 as oil output recovers, implying the current soft patch is viewed as cyclical rather than structural.
↓ p.2