GCC Macro Daily(Beta Mode)
War Risk Lifts Brent; Saudi CPI at 1.7%
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| Saudi Aramco | 26.38 | -1.35% |
| MSCI Saudi | 35.90 | +0.20% |
| MSCI UAE | 21.14 | +1.25% |
| MSCI Qatar | 17.78 | -0.08% |
| MSCI Kuwait | 36.22 | +0.00% |
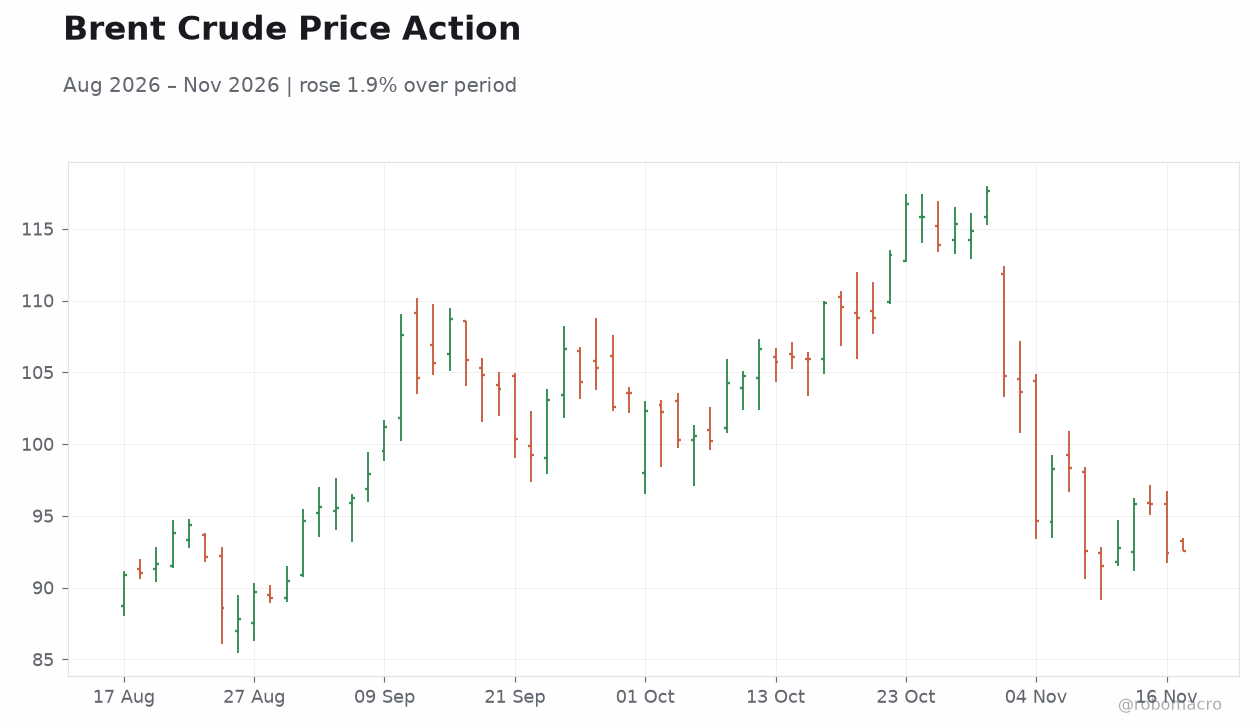
| Brent Crude | 92.73 | +0.31% |
| WTI Crude | 85.20 | -0.61% |
| Gold | 3,803.90 | -1.27% |
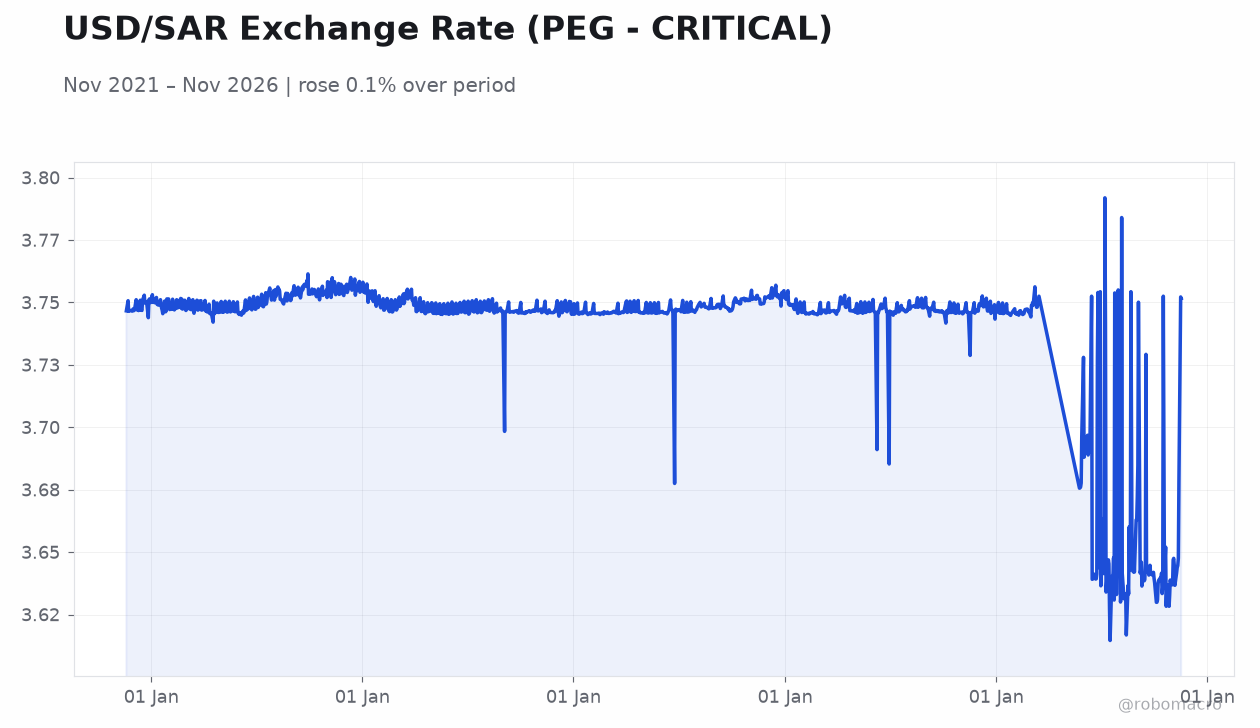
| USD/SAR | 3.75 | +2.92% |
| USD/AED | 3.67 | +0.02% |
| USD/KWD | 0.31 | -0.78% |
| Bitcoin | 64,358.14 | -0.77% |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
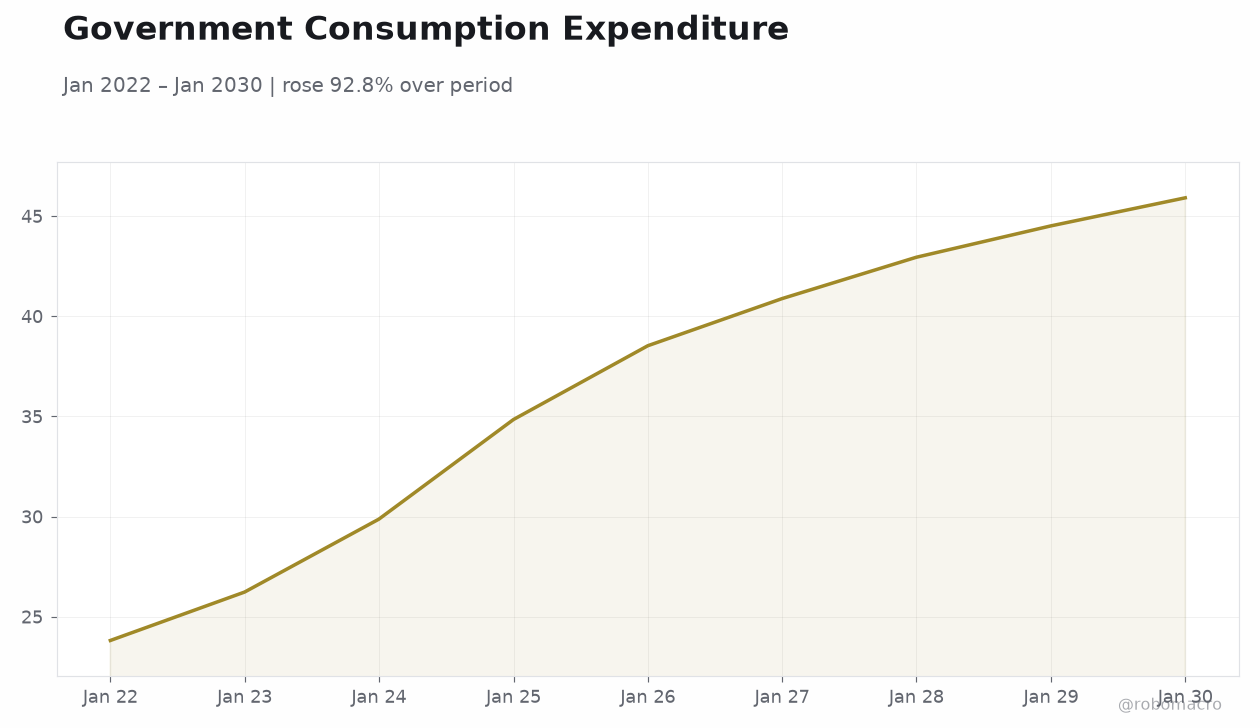 Government Consumption Expenditure | Type: macro_line | Government Consumption Expenditure: 45.92 (2030-01-01) | Range: 23.82–45.92 | Trend(5pt): 23.82,29.87,38.53,42.95,45.92
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Two tankers struck mines in the Strait of Hormuz; Kuwait air defences engaged hostile drones, keeping Gulf supply-risk premium elevated.
- Saudi October inflation printed 1.7%, while Moody's projects a 2027 Saudi rebound on recovering oil output.
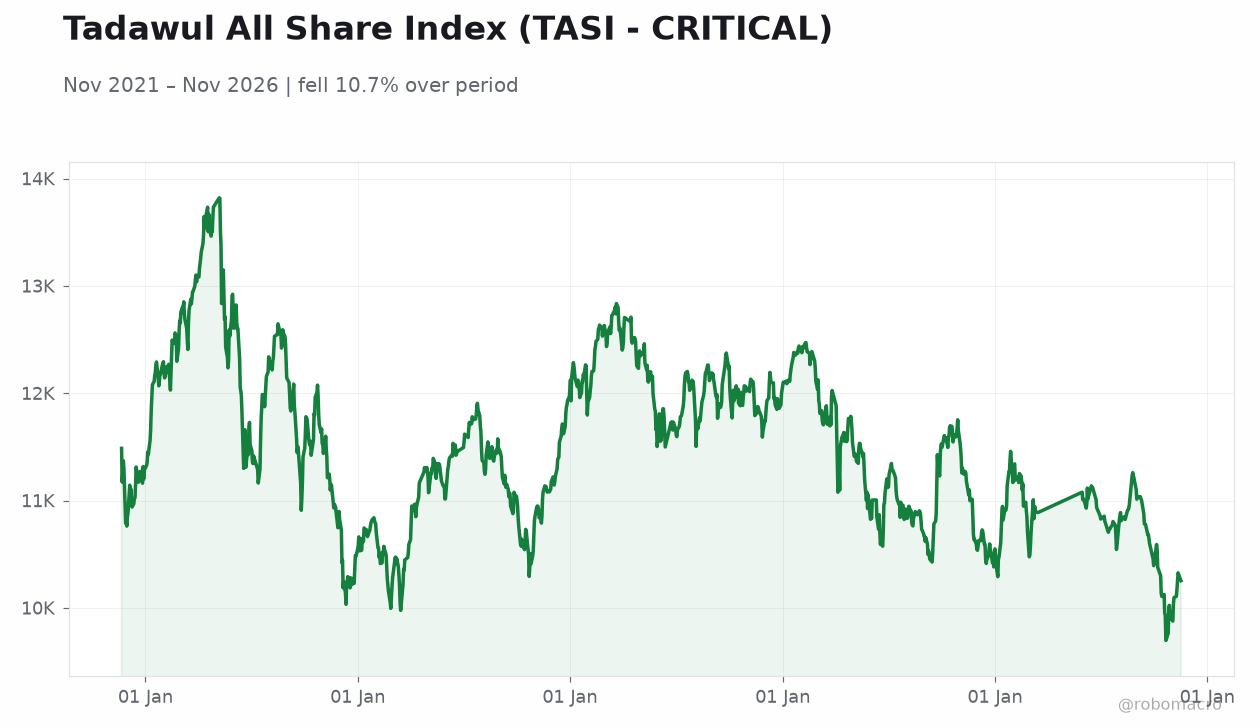
- Regional equities diverged: MSCI UAE rose 1.25% while Aramco fell 1.35%; USD/SAR ticked to 3.75.
Yesterday's Recap
Saudi Arabia's October CPI inflation reached 1.7%, a print that keeps real policy rates deeply positive and reinforces SAMA's comfortable hold posture. Moody's issued a forward-looking call that the Saudi economy will rebound in 2027 as oil output recovers, framing the current softness as cyclical rather than structural. Saudi Arabia issued 9,851 investment licences in Q3, with construction leading — a tangible non-oil diversification signal supporting the Vision 2030 narrative.
Regional equity performance diverged sharply: MSCI UAE gained 1.25% while MSCI Saudi added just 0.20% and Aramco fell 1.35%, with MSCI Qatar off 0.08% and MSCI Kuwait flat. Brent crude firmed 0.31% to $92.73, though WTI slipped 0.61% to $85.20, a split that partly reflects the Hormuz risk premium embedded in the waterborne benchmark. Qatar GDP contraction eased to 12% as gas output recovered, pointing to a shallow trough in the Qatari cycle.
Gold fell 1.27% to $3,803.90, and the USD/SAR quote at 3.75 reflected the peg holding firm despite the headline percentage move.
The Day Ahead
The calendar is empty across all three days, so flow will be driven by geopolitics and oil price action rather than scheduled data. Markets will watch whether the Strait of Hormuz mine incidents escalate into sustained shipping disruption, which would transmit directly into Brent and GCC sovereign CDS. Any further Kuwaiti air-defence activity will be monitored for spillover into Kuwaiti interbank and FX sentiment.
Qatar's mediation track with Iran remains the key diplomatic channel to watch for de-escalation signals. With no regional prints due, attention turns to global risk sentiment and the Fed backdrop as the dominant driver of GCC asset prices.
Other Economic Notes
The Strait of Hormuz mine strikes are the single most consequential macro variable for the Gulf right now, given that the waterway carries the bulk of Qatari LNG and much of the region's crude exports. Kuwait's air defences countering hostile drones adds a second front of security risk, and the UAE's National Day holiday will thin liquidity into early next week. Saudi Arabia's 9,851 Q3 investment licences, led by construction, suggest capex momentum is intact even as headline growth softens.
↓ p.2