GCC Macro Daily(Beta Mode)
Oil Jumps on Houthi Strikes; Gulf Equities Slip
Market Snapshot
| Asset | Level | Change |
|---|---|---|
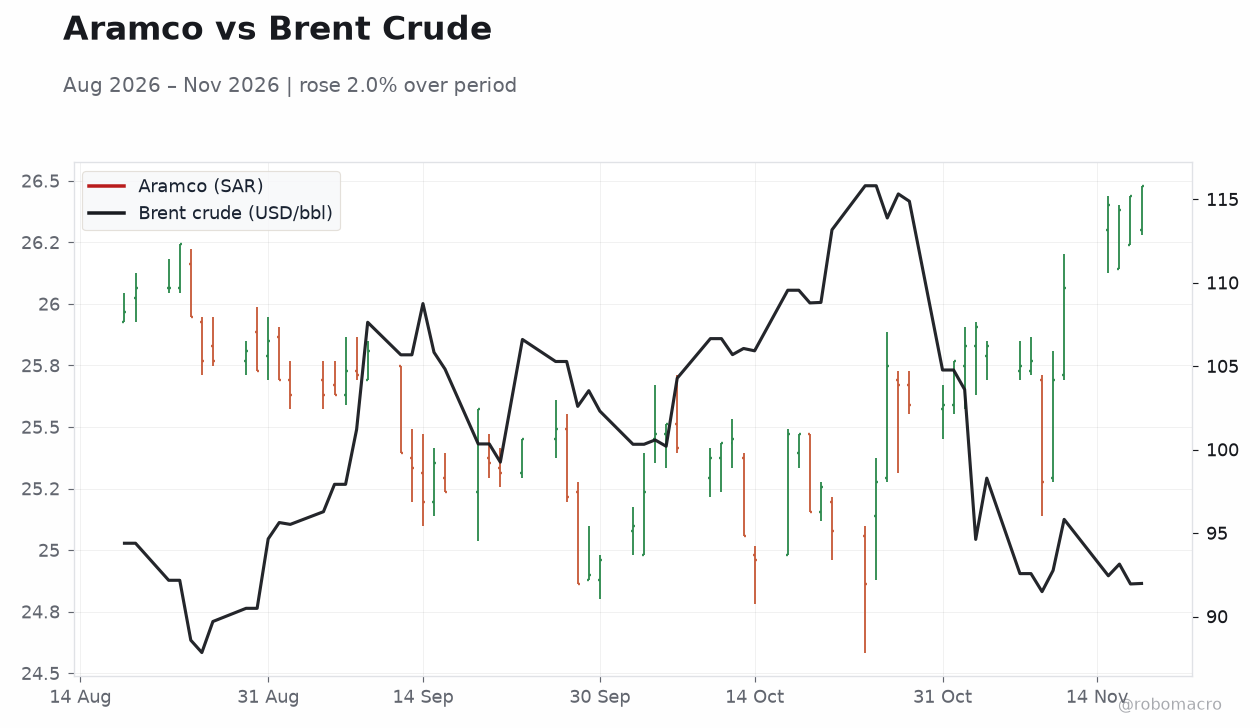
| Saudi Aramco | 26.48 | +0.15% |
| MSCI Saudi | 34.96 | -0.54% |
| MSCI UAE | 20.81 | -0.38% |
| MSCI Qatar | 17.57 | -0.48% |
| MSCI Kuwait | 35.27 | -0.91% |
| Brent Crude | 92.57 | +0.64% |
| WTI Crude | 83.98 | +0.93% |
| Gold | 3,515.40 | -4.62% |
| USD/SAR | 3.63 | +0.07% |
| USD/AED | 3.67 | +0.04% |
| USD/KWD | 0.31 | +0.08% |
| Bitcoin | 59,917.03 | +1.90% |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
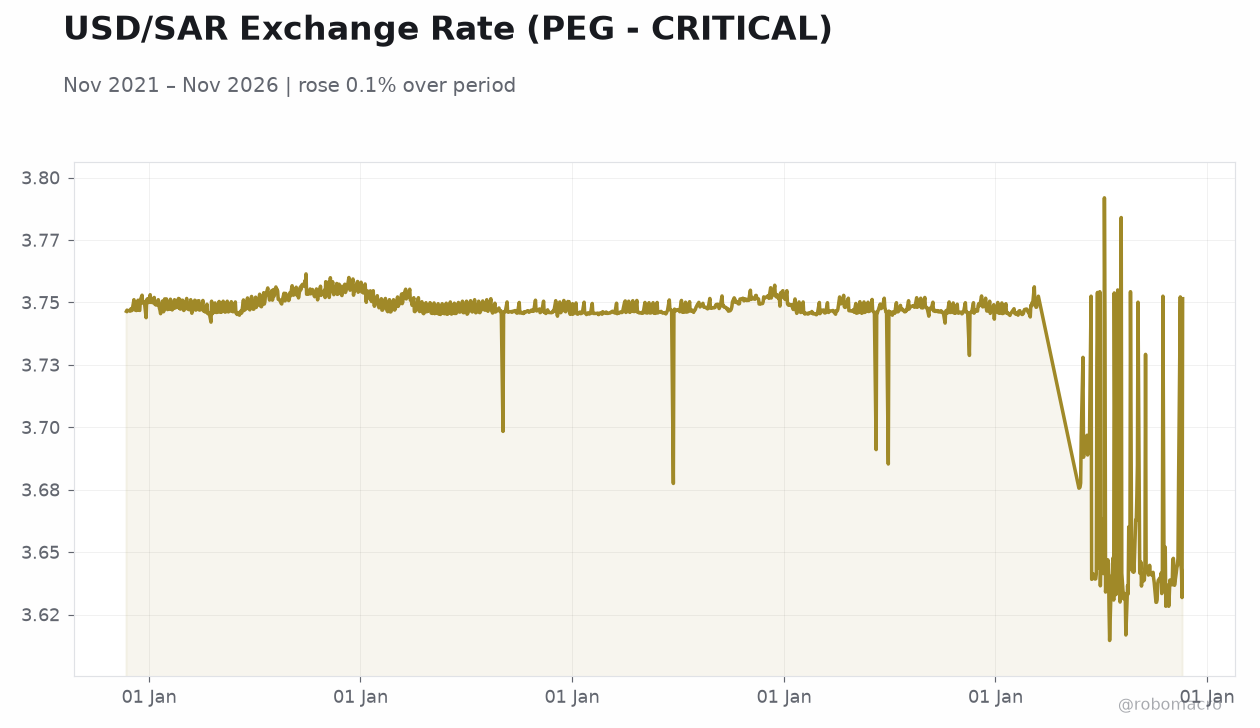 USD/SAR Exchange Rate (PEG - CRITICAL) | Type: macro_line | USD/SAR Exchange Rate (PEG - CRITICAL): 3.752 (2026-11-20) | Range: 3.615–3.792 | Trend(5pt): 3.746,3.748,3.746,3.746,3.752
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Brent crude rose 0.64% to $92.57 and WTI gained 0.93% to $83.98 after Houthi missile strikes on Saudi Arabia, lifting Gulf sovereign risk premia.
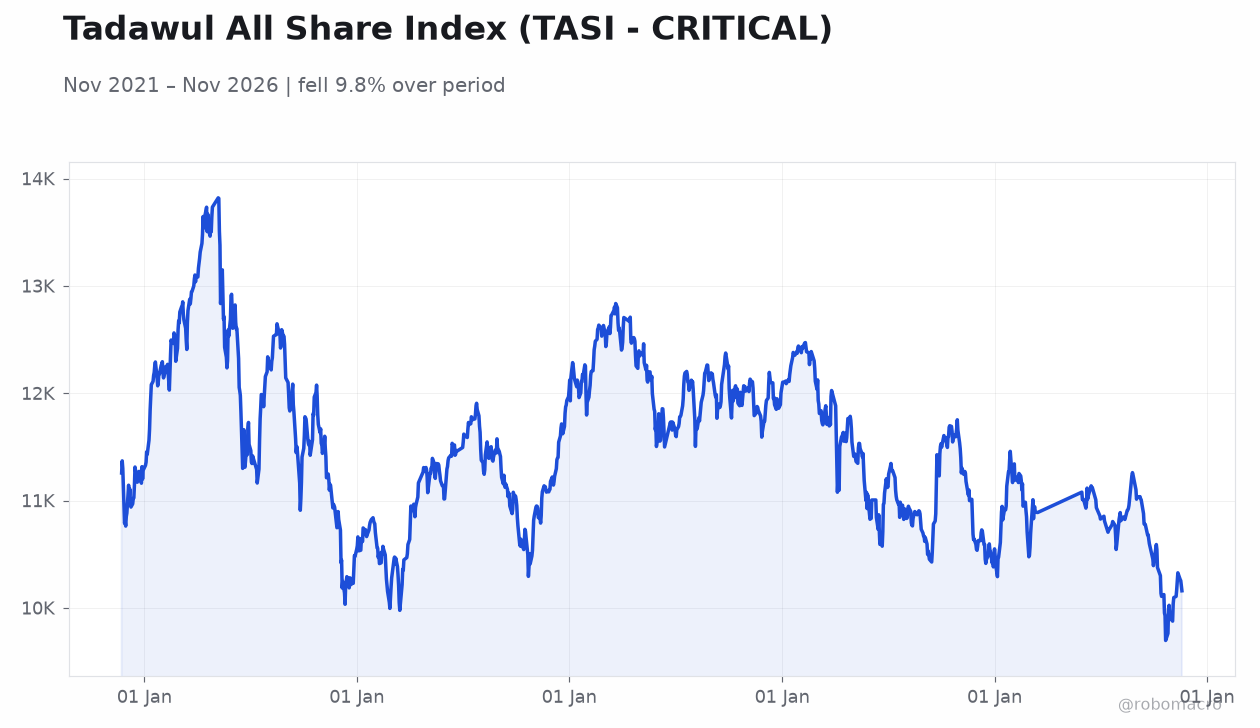
- GCC equity benchmarks sold off broadly: MSCI Kuwait fell 0.91%, MSCI Saudi 0.54%, MSCI Qatar 0.48%, and MSCI UAE 0.38%, while Saudi Aramco edged up 0.15%.
- Gold plunged 4.62% to $3,515.40/oz, a sharp risk-on rotation into oil and equities; USD pegs held firm across SAR, AED, and KWD.
Yesterday's Recap
GCC markets on Thursday were dominated by renewed geopolitical risk after Houthi missile strikes on Saudi Arabia, which pushed Brent crude up 0.64% to $92.57 and WTI up 0.93% to $83.98. The Houthi military spokesman, Yahya Saree, denied any threat to Mecca, tempering the initial risk-off impulse, but the supply-risk premium nonetheless widened. Gulf equity markets reflected the tension: MSCI Kuwait led losses at -0.91%, MSCI Saudi fell 0.54%, MSCI Qatar -0.48%, and MSCI UAE -0.38%, while Saudi Aramco bucked the trend with a modest +0.15% gain.
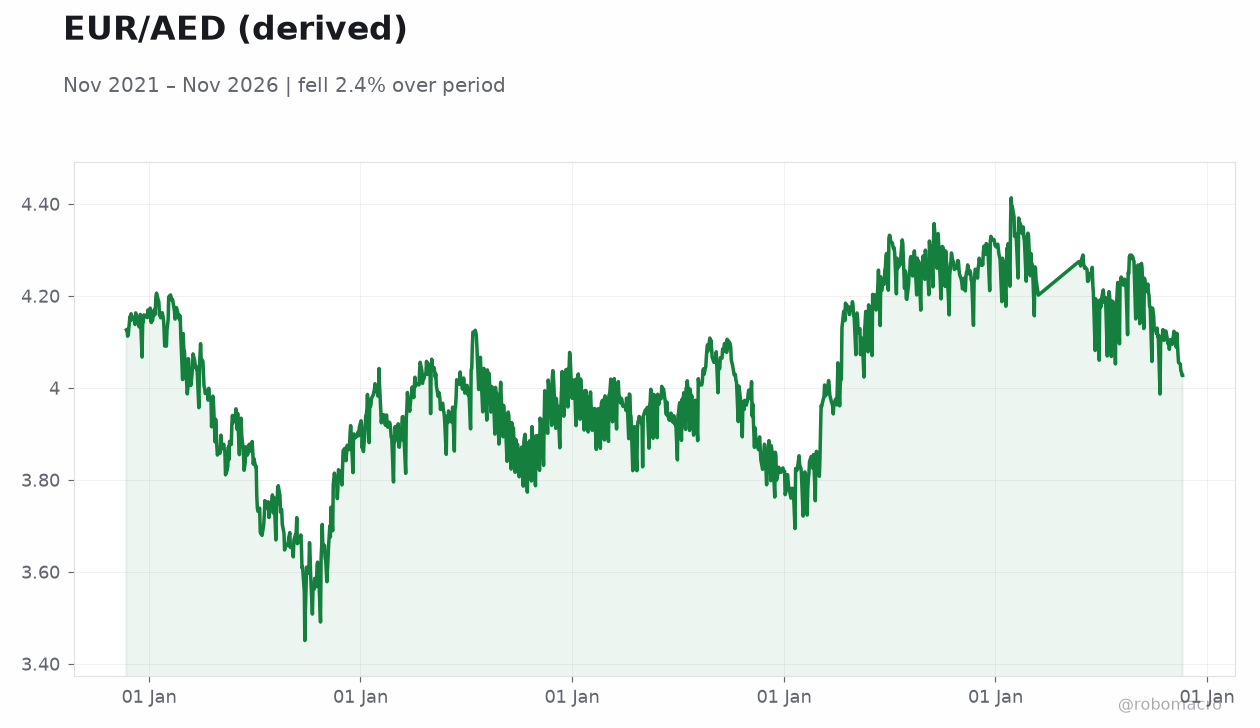
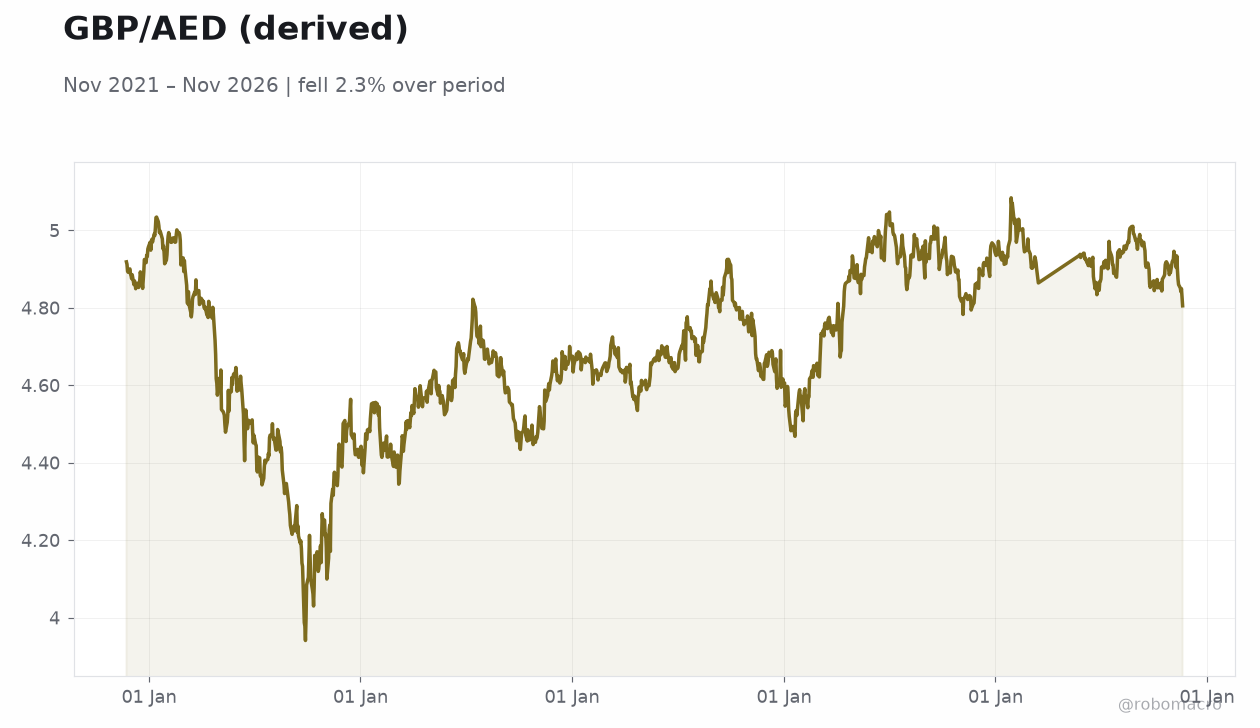
Currency pegs remained rock-solid, with USD/SAR at 3.63 (+0.07%), USD/AED at 3.67 (+0.04%), and USD/KWD at 0.31 (+0.08%). Gold's 4.62% collapse to $3,515.40 signaled rotation out of havens into energy and risk assets. No scheduled GCC macro data releases printed on Thursday, leaving price action to geopolitics and oil.
Bitcoin's 1.90% rise to $59,917 underscored a broader risk-appetite recovery despite the Gulf equity softness.
The Day Ahead
Friday's GCC calendar is empty of scheduled tier-one releases, so markets will trade on oil-price momentum and headline flow around Yemen and the Red Sea. Traders will watch whether Brent sustains above $92, a level that materially improves Saudi and Kuwaiti fiscal breakevens. Saudi Arabia's 15% minimum tax on multinationals, effective 2027, remains a structural theme for foreign direct investment flows.
Qatar's diplomatic delegation to Tehran bears watching for any de-escalation signal that could compress regional CDS spreads. With no data catalysts, interbank rates (SAIBOR, EIBOR) and Fed-speak will be the primary drivers of short-end pricing. Liquidity is likely to thin into the weekend, amplifying headline-driven volatility.
Other Economic Notes
Saudi Arabia's push to bring social security beneficiaries into the workforce signals continued labor-market formalization under Vision 2030, supporting non-oil consumption. The Kingdom's first-place global ranking in digital government services reinforces the diversification narrative underpinning sovereign credit strength. Japan's agreement to store and purchase up to 8 million barrels of Saudi crude strengthens Asia-Gulf energy ties and provides demand visibility for Saudi Aramco.
↓ p.2