Greater China Macro Daily(Beta Mode)
China Data Loom as Equities Slip
Market Snapshot
| Asset | Level | Change |
|---|---|---|
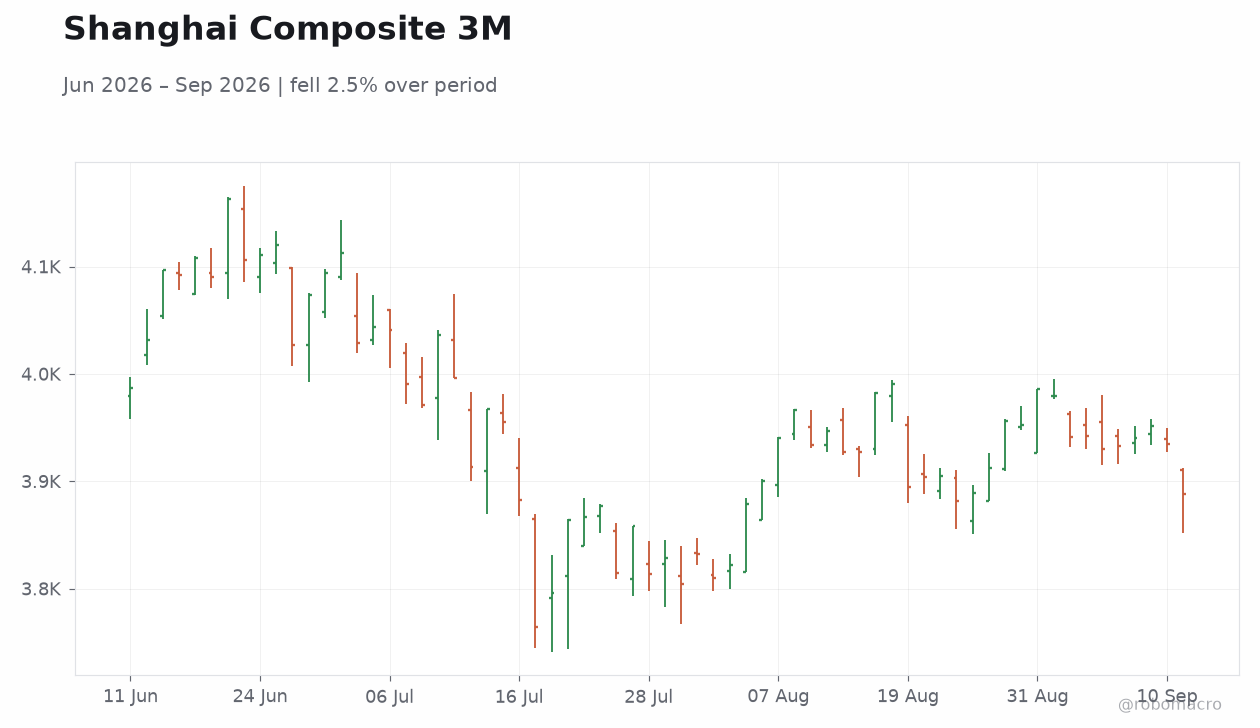
| Shanghai Composite | 3,888.11 | -1.18% |
| CSI 300 | 4,510.16 | -0.84% |
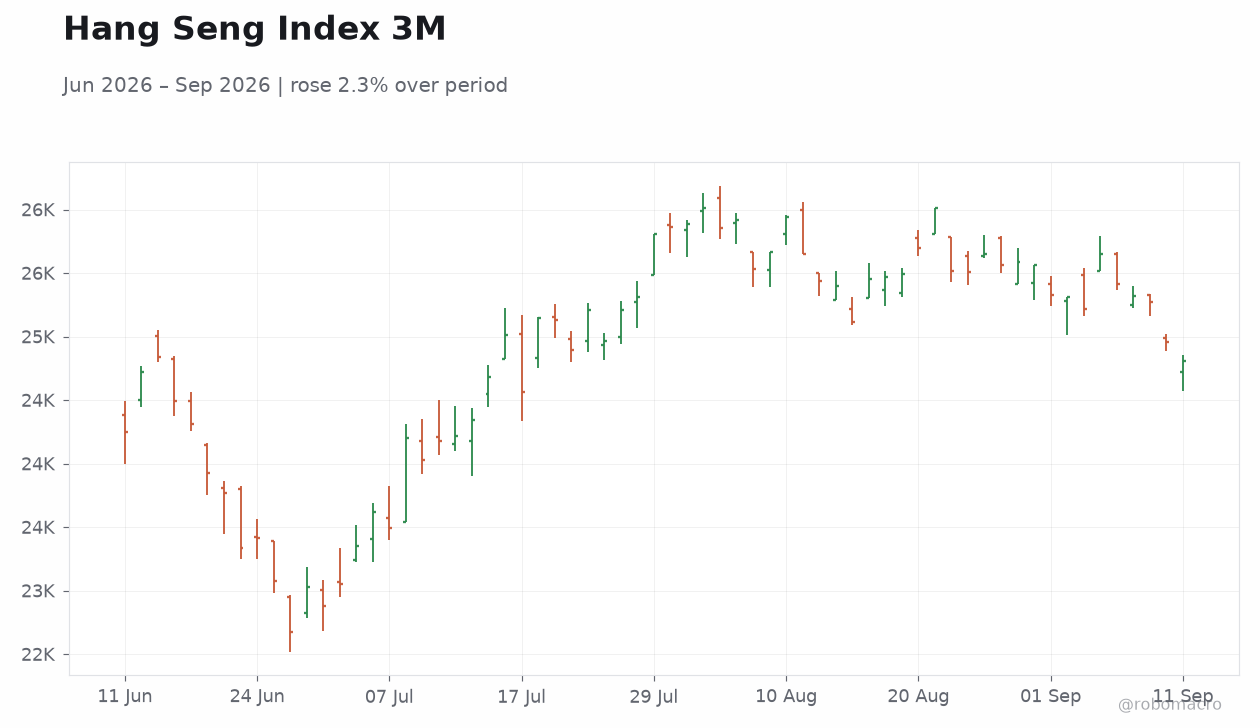
| Hang Seng | 24,805.63 | -0.60% |
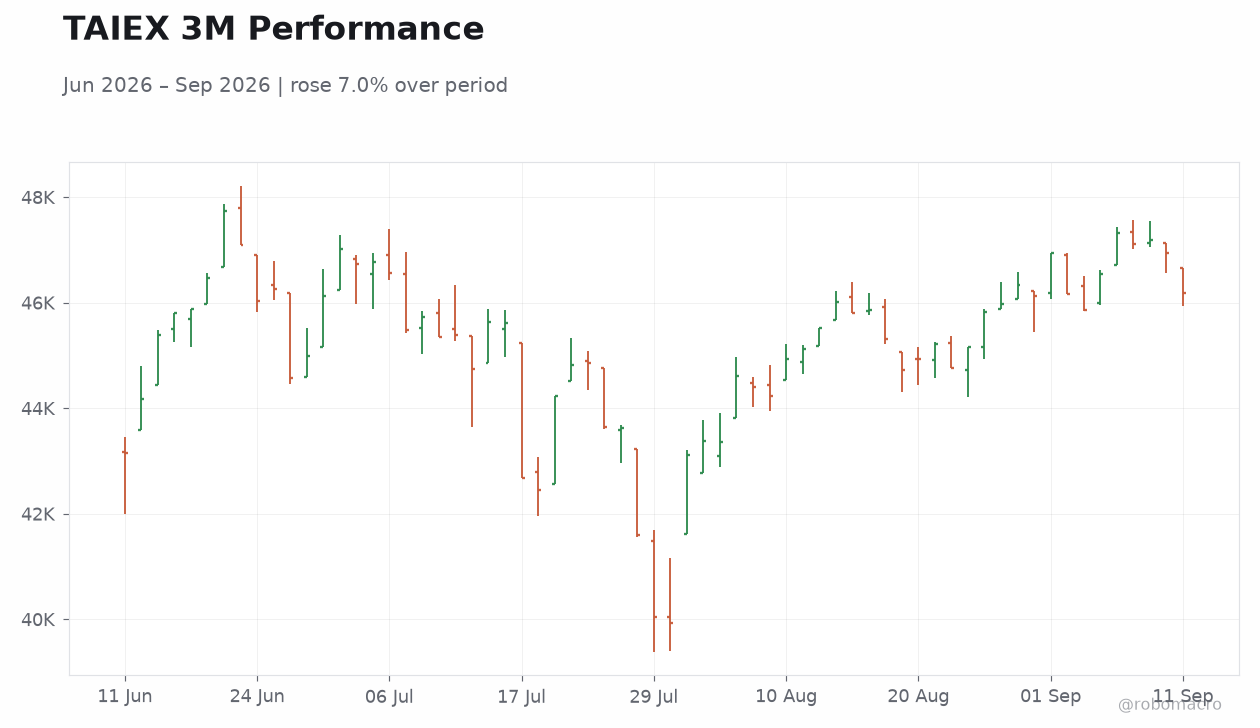
| TAIEX | 46,184.85 | -1.61% |
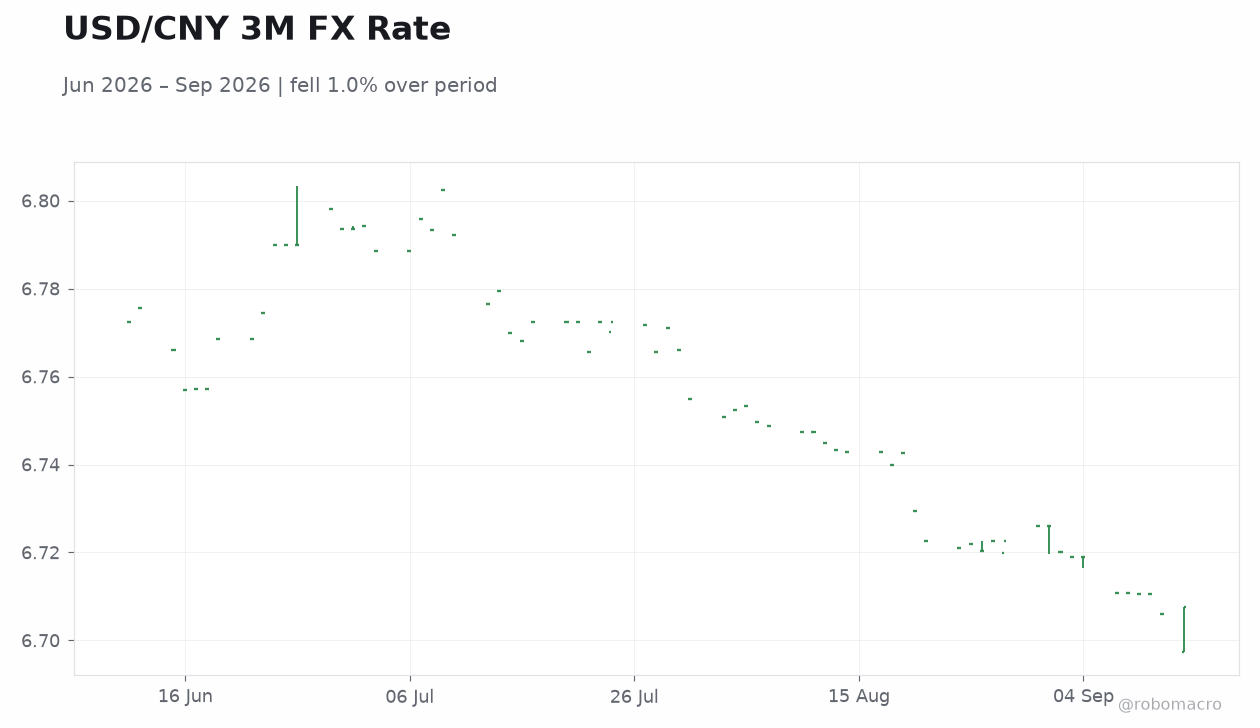
| USD/CNY | 6.70 | -0.13% |
| USD/HKD | 7.84 | +0.01% |
| Copper | 6.55 | +1.25% |
| Brent Crude | 104.61 | -2.81% |
| Gold | 4,408.90 | +1.02% |
| Bitcoin | 77,105.62 | -0.21% |
| China 2Y Govt Yield | - | - |
| China 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
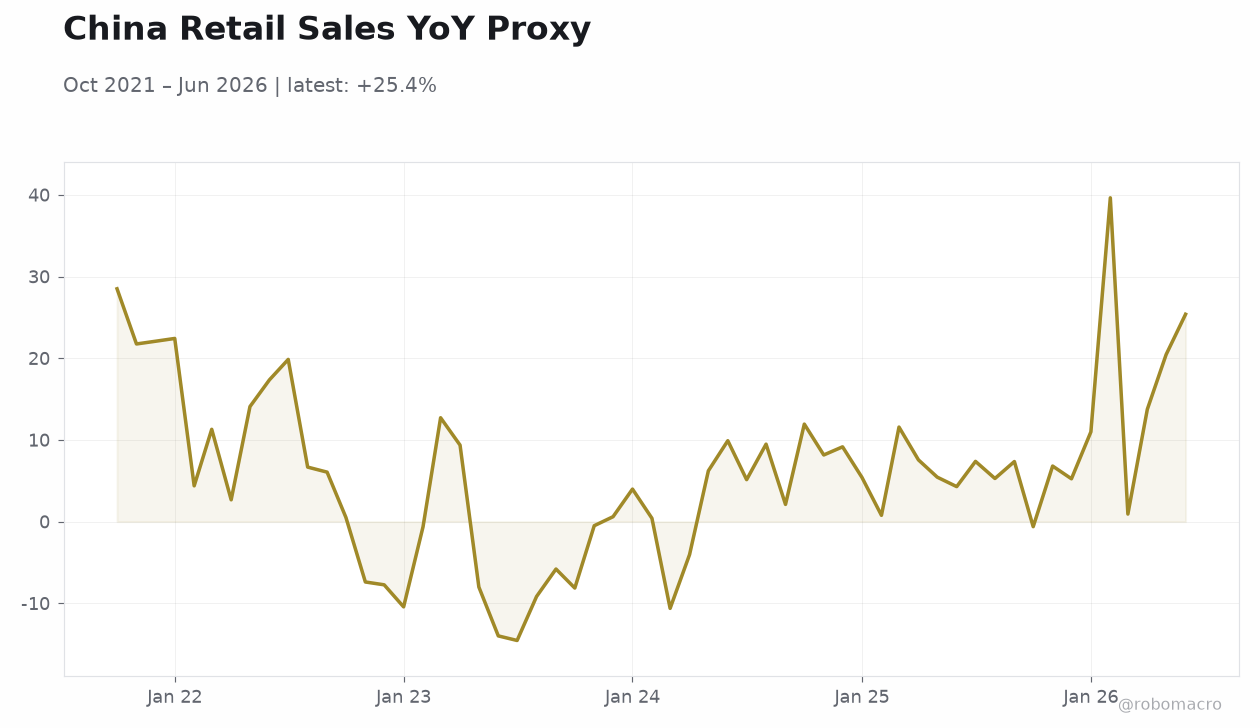 China Retail Sales YoY Proxy | Type: macro_line | Exports YoY %: 25.39 (2026-06-01) | Range: -14.55–39.64 | Trend(5pt): 28.5,-7.732,0.4113,7.56,25.39
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| House Price Index Year-over-Year | -3.20 | - | 21:30 |
| Industrial Production Year-over-Year | 4.50 | 4.80 | 22:00 |
| Retail Sales Year-over-Year | 0.60 | 0.80 | 22:00 |
| Fixed Asset Investment (Year-to-Date) Year-over-Year | -6.70 | -7.10 | 22:00 |
- Mainland China activity data including industrial production and retail sales due tomorrow will test growth momentum.
- Equities fell across Greater China, led by TAIEX decline of 1.61% on rate-hike concerns.
- USD/CNY eased to 6.70 while PBOC reference rate expected at 6.7174.
Yesterday's Recap
No macroeconomic releases emerged from mainland China, Hong Kong or Taiwan on September 12. Mainland equities retreated, with the Shanghai Composite falling 1.18% to 3,888.11 and the CSI 300 declining 0.84% to 4,510.16. Hong Kong’s Hang Seng Index slipped 0.60% to 24,805.63 while Taiwan’s TAIEX dropped 1.61% to 46,184.85 amid semiconductor sector weakness.
USD/CNY moved lower to 6.70, aligning with the Reuters-estimated PBOC fixing of 6.7174, and USD/HKD held steady at 7.84. Copper advanced 1.25% to 6.55 as a China demand proxy while Brent crude fell 2.81% to 104.61. Gold rose 1.02% to 4,408.90 and Bitcoin eased 0.21% to 77,105.62.
TSMC posted record August revenue growth of 53.3% year-on-year, yet Taiwan equities still declined on expectations of tighter global policy. HKMA’s 2026 Green Fintech Symposium highlighted efforts to channel finance toward net-zero goals without altering near-term liquidity settings. China’s August CPI at 0.80% year-on-year continues to signal contained price pressures.
The Day Ahead
Four mainland China releases are scheduled for September 14 at 21:30-22:00 ET. Industrial production is expected to rise 4.8% year-on-year while retail sales are forecast to increase 0.8%. Fixed-asset investment year-to-date is projected to contract 7.1% and the house-price index will update property-sector trends.
No PBoC liquidity operations, HKMA interventions or CBC policy meetings are flagged. Markets will parse the prints for signals on whether recent equity weakness reflects softening domestic demand. Copper and Brent price moves will also influence sentiment ahead of the data.
Hong Kong’s first five-year plan and green-finance initiatives aim to bolster long-term competitiveness without immediate monetary impact.
Other Economic Notes
Property-sector data tomorrow will clarify whether price declines have stabilized after earlier contraction. TSMC’s revenue surge underscores resilient semiconductor export linkages despite Taiwan equity weakness. Cross-strait trade flows remain steady, with no new policy shifts reported.
Tesla reported continued double-digit sales growth in China, albeit at a slower pace. The PBOC is expected to set the USD/CNY reference rate at 6.7174, providing a near-term anchor for currency markets.