Greater China Macro Daily(Beta Mode)
Weak China Loans Weigh on Equities
Market Snapshot
| Asset | Level | Change |
|---|---|---|
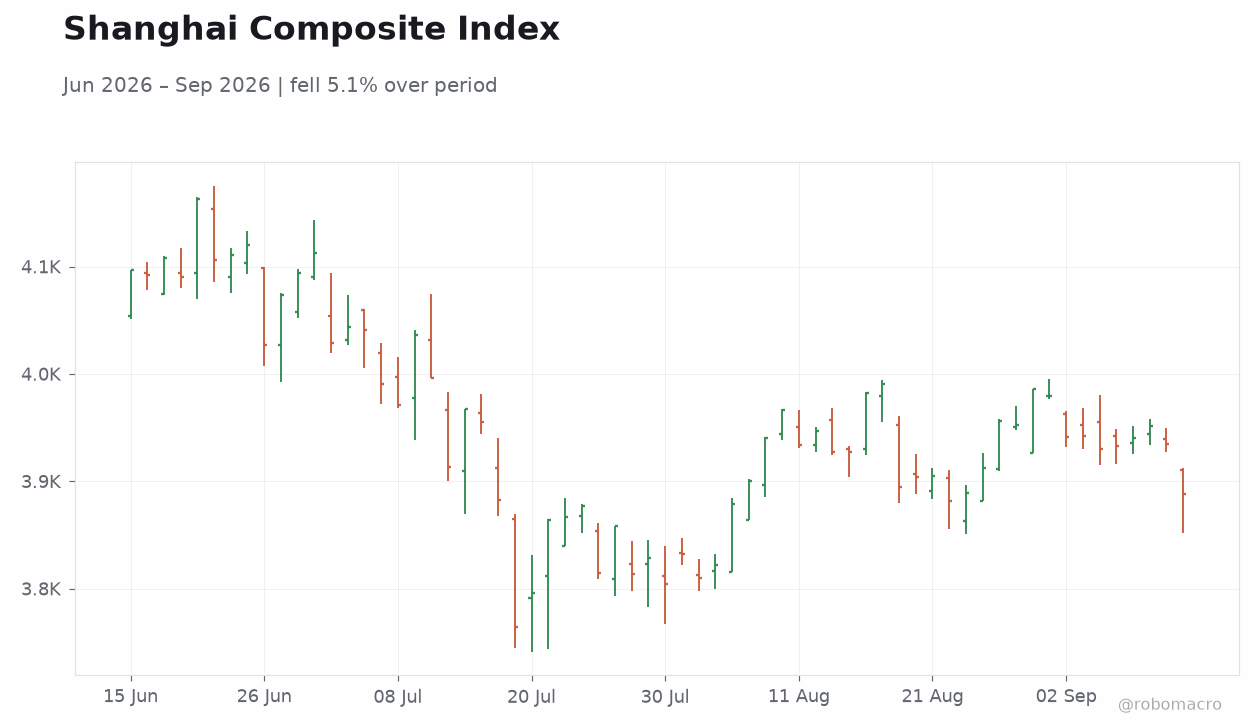
| Shanghai Composite | 3,888.11 | -1.18% |
| CSI 300 | 4,510.16 | -0.84% |
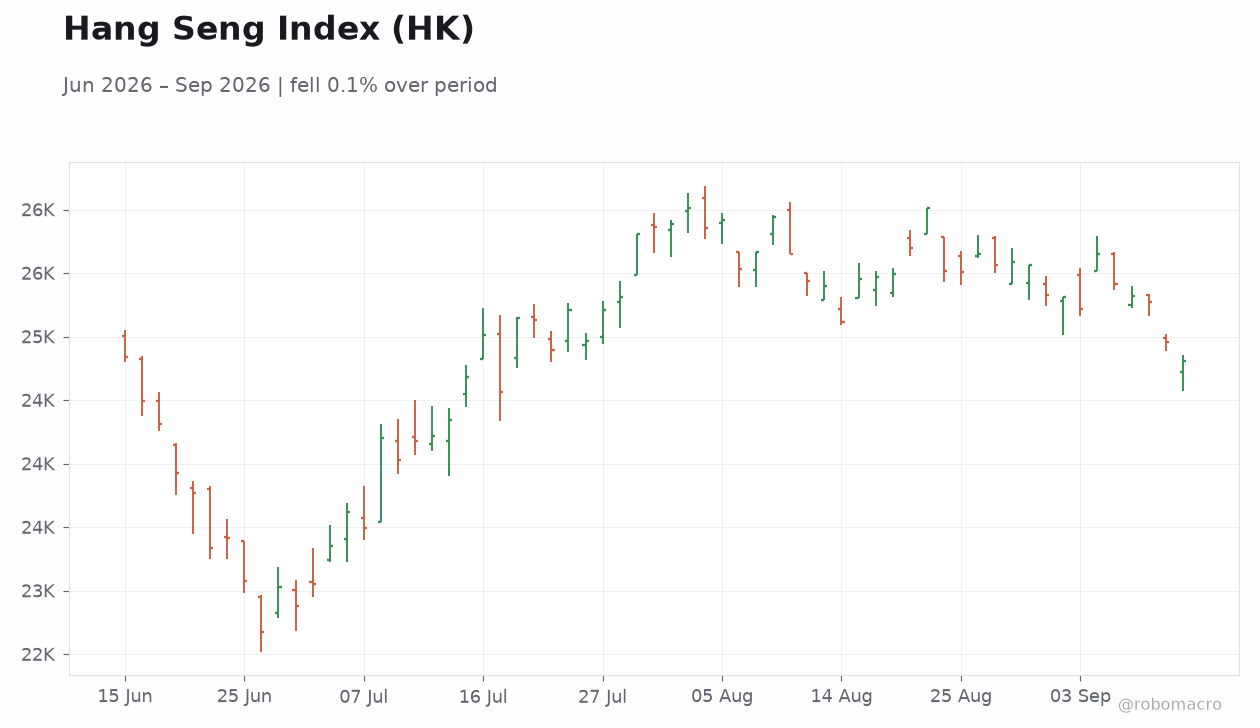
| Hang Seng | 24,805.63 | -0.60% |
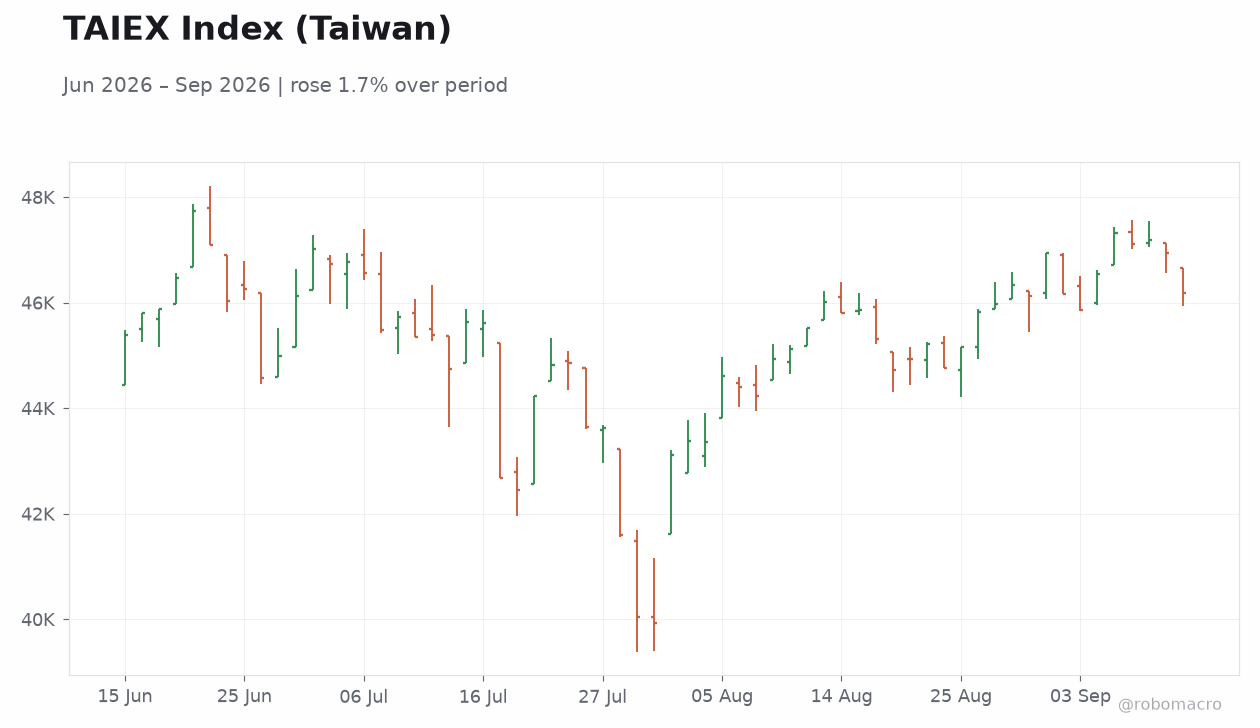
| TAIEX | 46,184.85 | -1.61% |
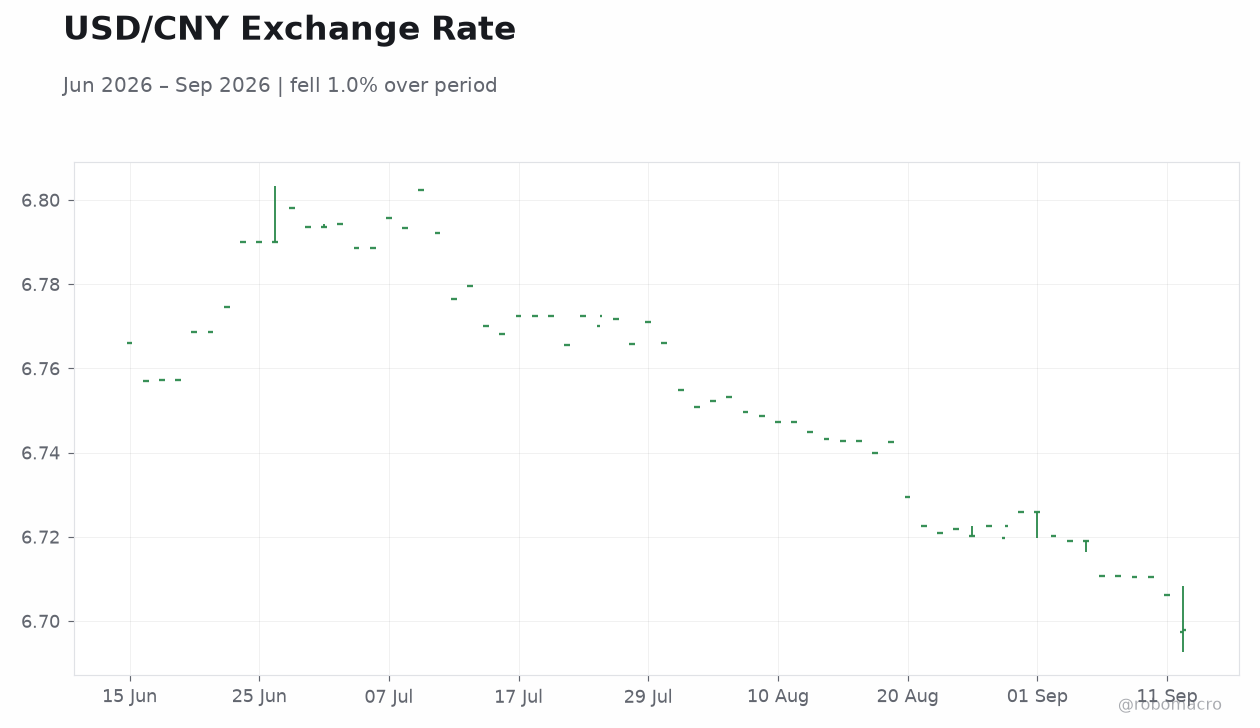
| USD/CNY | 6.70 | -0.12% |
| USD/HKD | 7.84 | +0.01% |
| Copper | 6.40 | -1.11% |
| Brent Crude | 106.15 | +1.47% |
| Gold | 4,340.00 | -1.56% |
| Bitcoin | 78,722.81 | +2.45% |
| China 2Y Govt Yield | - | - |
| China 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| New Yuan Loans Level | -340,000m | 400,000m | 60,000m |
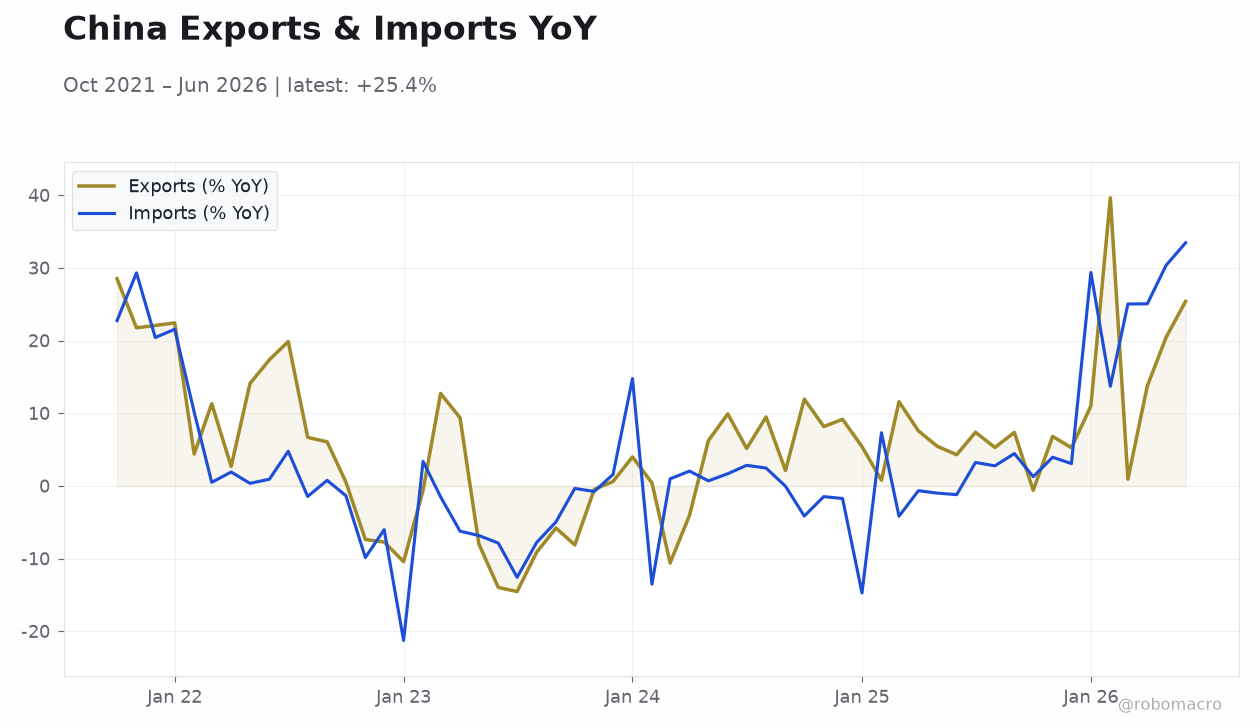 China Exports & Imports YoY | Type: macro_line | Exports (% YoY): 25.39 (2026-06-01) | Range: -14.55–39.64 | Trend(5pt): 28.5,-7.732,0.4113,7.56,25.39 | Imports (% YoY): 33.45 (2026-06-01) | Range: -21.28–33.45 | Trend(5pt): 22.74,-6.027,-13.53,-0.665,33.45
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| House Price Index Year-over-Year | -3.20 | - | 17:30 |
| Industrial Production Year-over-Year | 4.50 | 4.80 | 18:00 |
| Retail Sales Year-over-Year | 0.60 | 0.80 | 18:00 |
| Fixed Asset Investment (Year-to-Date) Year-over-Year | -6.70 | -7.20 | 18:00 |
| Central Bank Interest Rate Decision | 2 | - | 00:30 |
- New Yuan Loans print CNY 60bn, missing consensus by wide margin.
- Shanghai Composite falls 1.18% while TAIEX drops 1.61%.
- Brent climbs 1.47% as copper declines 1.11% amid growth concerns.
Yesterday's Recap
New Yuan Loans printed at CNY 60 billion, far below the CNY 400 billion consensus and reversing the prior CNY -340 billion contraction. The soft reading signals persistent weak credit demand across mainland China and reinforces expectations for further PBoC support. Mainland equities led the declines, with the Shanghai Composite closing at 3,888.11 (-1.18%) and the CSI 300 at 4,510.16 (-0.84%).
Hong Kong’s Hang Seng fell 0.60% to 24,805.63 while Taiwan’s TAIEX dropped 1.61% to 46,184.85. USD/CNY eased 0.12% to 6.70, reflecting modest yuan strength that has already generated roughly 70 billion yuan in FX losses for Chinese exporters in the first half. TSMC posted record August revenue, up 53.3% year-on-year on AI and smartphone demand, providing a bright spot for Taiwan’s semiconductor supply chain.
Brent Crude rose 1.47% to 106.15 while copper slipped 1.11% to 6.40, underscoring mixed commodity signals for mainland growth.
The Day Ahead
Today’s key mainland China releases at 17:30-18:00 ET include the House Price Index YoY, Industrial Production YoY (consensus 4.8%, prior 4.5%), Retail Sales YoY (consensus 0.8%, prior 0.6%), and Fixed Asset Investment YTD YoY (consensus -7.2%, prior -6.7%). Any shortfall versus consensus would heighten calls for additional policy easing from the PBoC. The central bank will also announce its daily USD/CNY reference rate, with Reuters estimating 6.7174.
No HKMA liquidity operations or CBC policy moves are scheduled. Taiwan’s Central Bank interest rate decision follows on September 17, where the committee is expected to hold the policy rate steady amid solid semiconductor export momentum. Market participants will watch for any signals on FX intervention or cross-strait trade flows.
Other Economic Notes
Mainland China’s property sector remains under pressure, with the upcoming House Price Index likely to show continued weakness that could prompt further targeted stimulus. Semiconductor strength in Taiwan contrasts with broader equity weakness, highlighting the sector’s resilience to global rate-hike fears. Reports of manufacturers returning to mainland China after earlier tariff-driven exits suggest some reversal of supply-chain diversification trends.
A new 0.5 MTPA LNG supply agreement between Venture Global and China Gas underscores Beijing’s push to secure energy imports amid elevated Brent prices. Yuan strength this year has prompted authorities to encourage stronger hedging among exporters to limit further losses.