Greater China Macro Daily(Beta Mode)
China Retail Miss Offsets IP Beat
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| Shanghai Composite | 3,864.28 | -0.54% |
| CSI 300 | 4,450.04 | -1.33% |
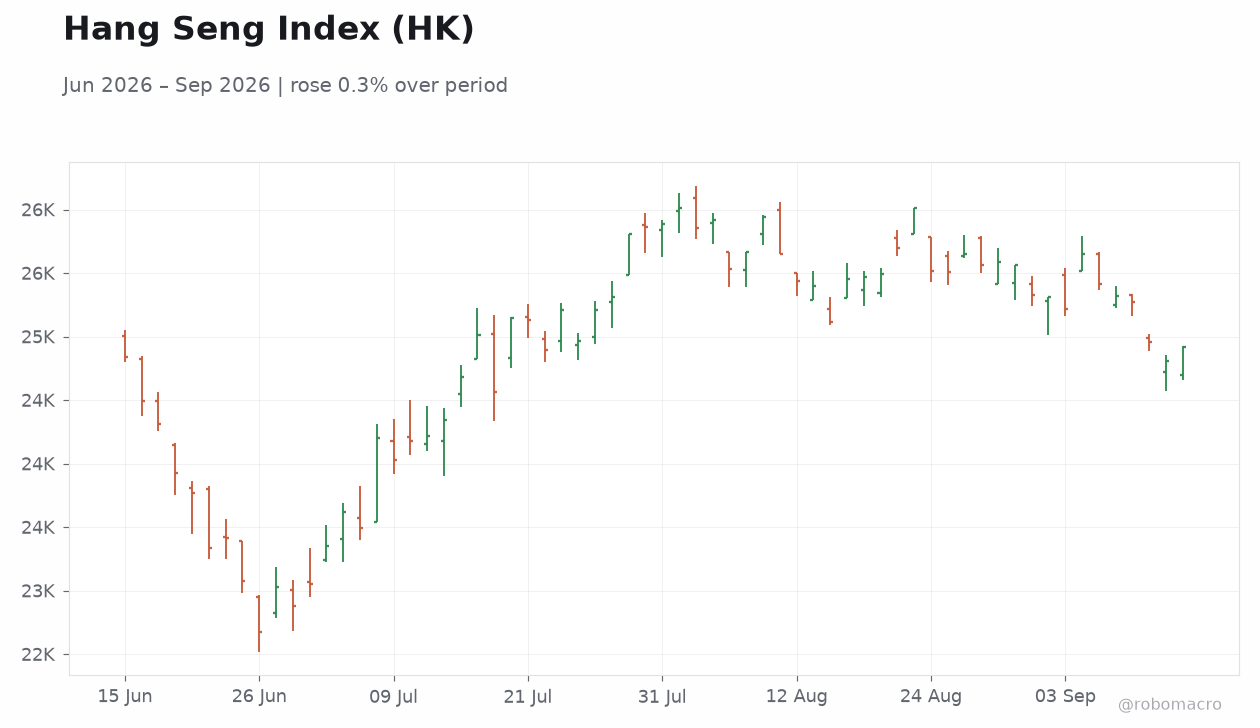
| Hang Seng | 24,917.60 | +0.45% |
| TAIEX | 45,862.52 | -0.70% |
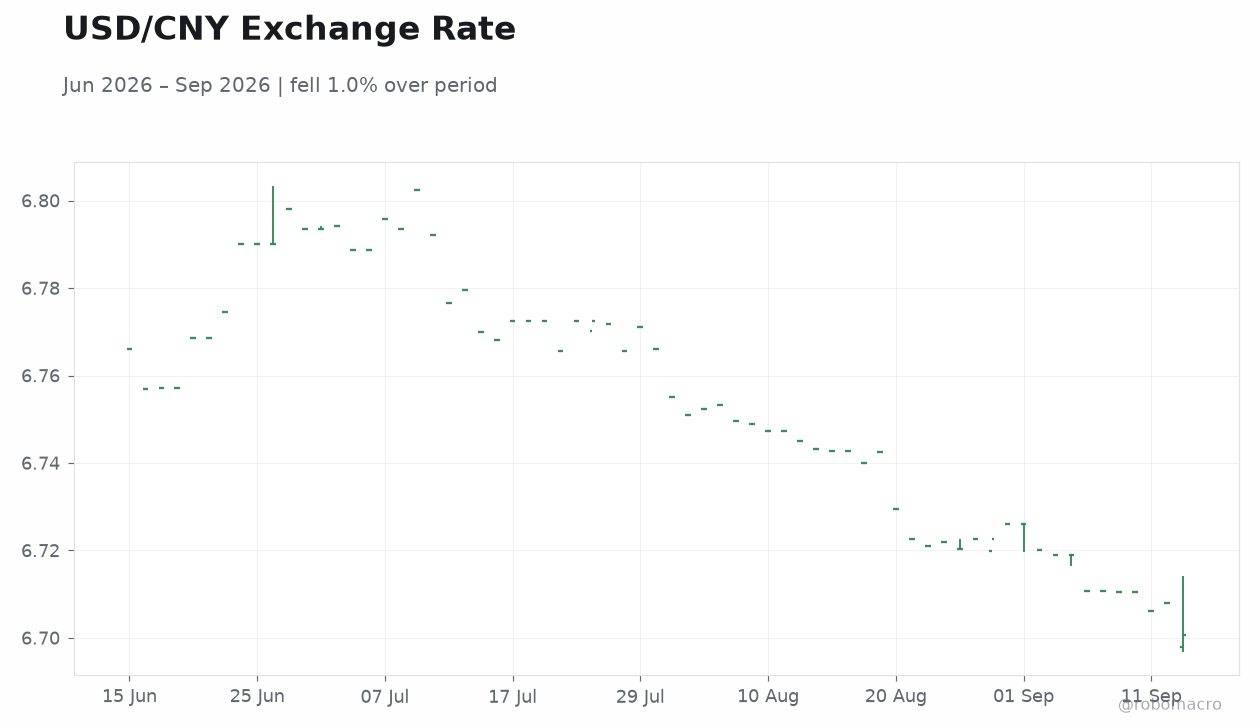
| USD/CNY | 6.70 | -0.11% |
| USD/HKD | 7.84 | +0.03% |
| Copper | 6.46 | +2.04% |
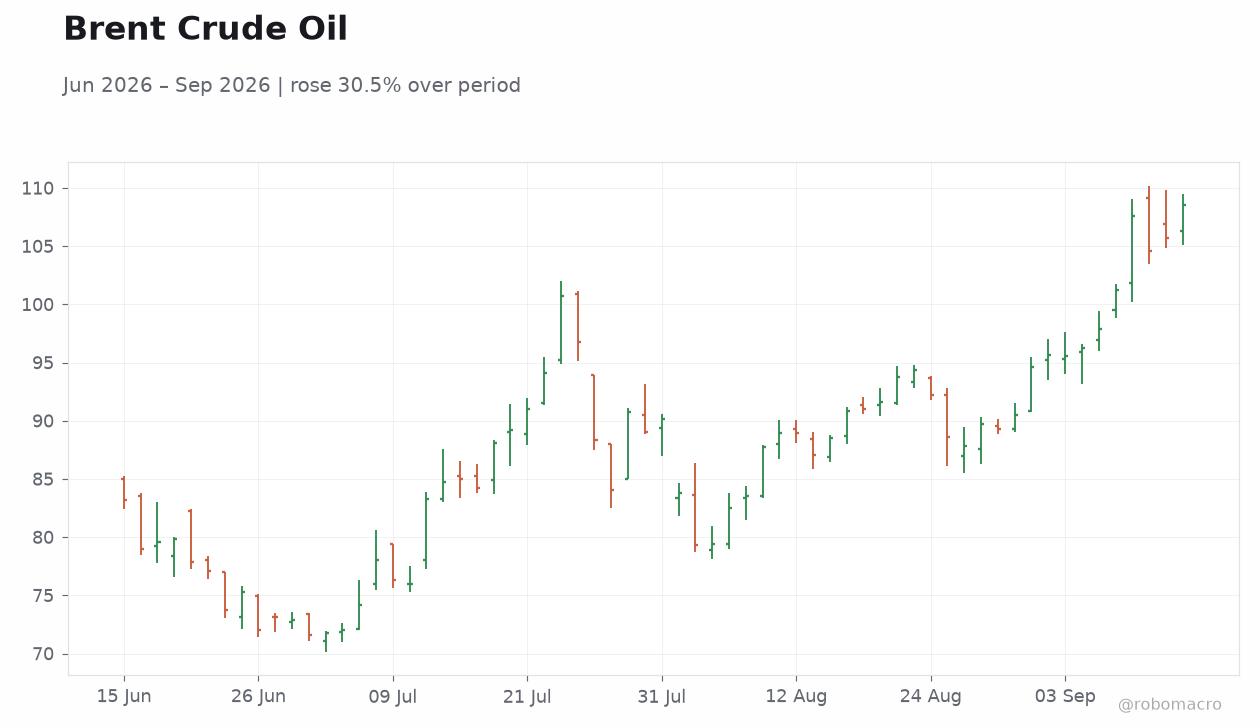
| Brent Crude | 108.50 | +2.67% |
| Gold | 4,333.40 | -0.43% |
| Bitcoin | 75,351.50 | -3.60% |
| China 2Y Govt Yield | - | - |
| China 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| New Yuan Loans Level | -340,000m | 400,000m | 60,000m |
| House Price Index Year-over-Year | -3.20 | - | -3 |
| Industrial Production Year-over-Year | 4.50 | 4.80 | 5.20 |
| Retail Sales Year-over-Year | 0.60 | 0.80 | 0.40 |
| Fixed Asset Investment (Year-to-Date) Year-over-Year | -6.70 | -7.20 | -7.20 |
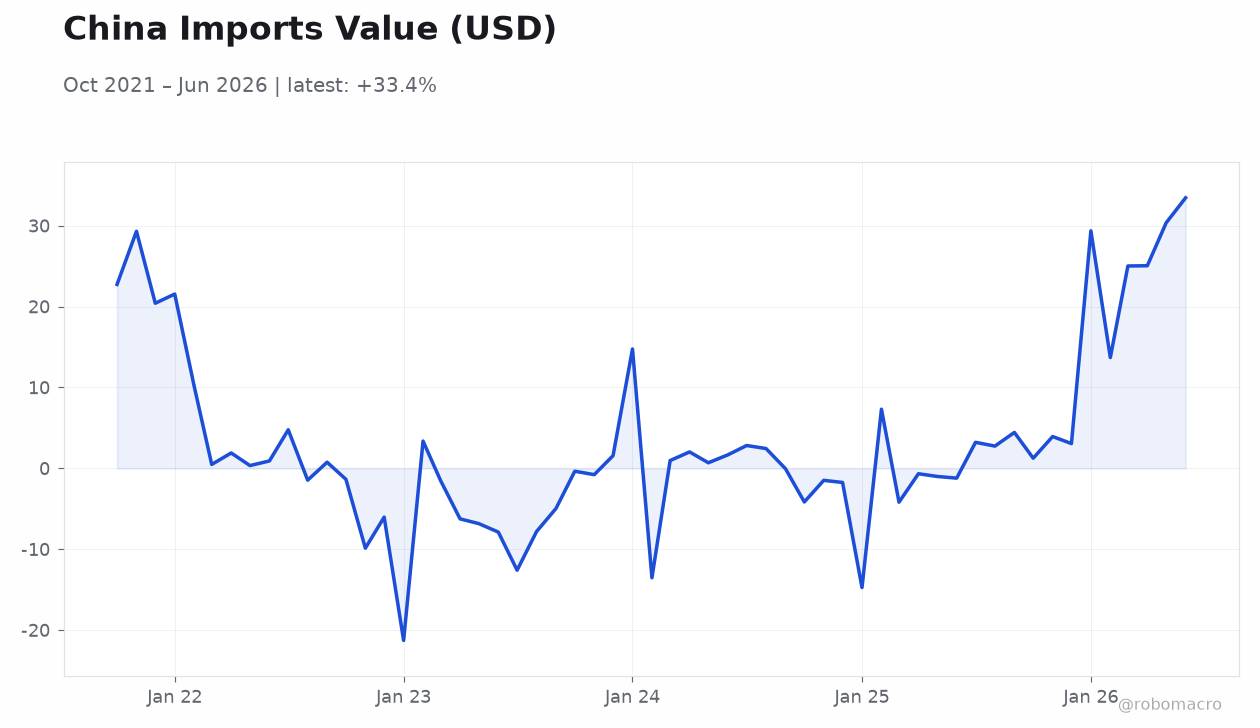
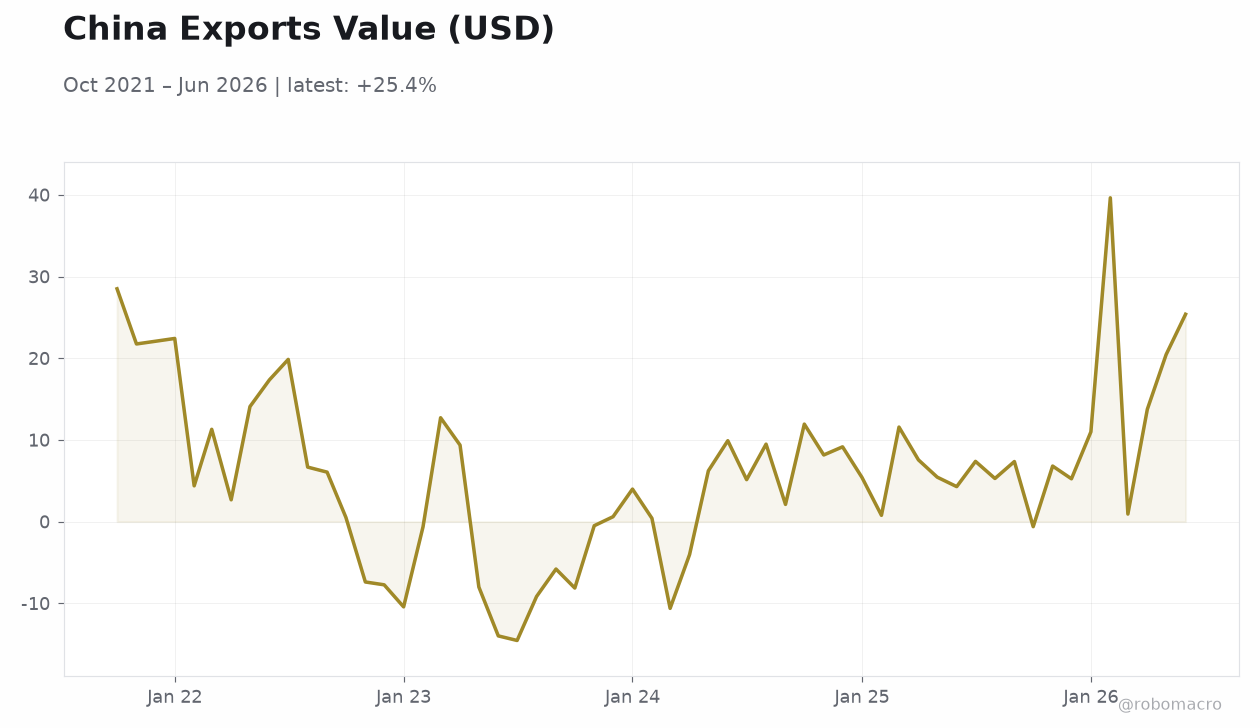 China Exports Value (USD) | Type: macro_line | USD mn: 25.39 (2026-06-01) | Range: -14.55–39.64 | Trend(5pt): 28.5,-7.732,0.4113,7.56,25.39
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Central Bank Interest Rate Decision | 2 | - | 00:30 |
- China’s September industrial production rose 5.2% YoY, beating consensus, while retail sales fell short at 0.4% YoY and new yuan loans printed only CNY 60 billion.
- Mainland equities declined with CSI 300 down 1.33%, though Hong Kong’s Hang Seng gained 0.45%; USD/CNY eased 0.11% to 6.70.
- Taiwan’s central bank meets today amid persistent inflation above target, while fixed-asset investment remained weak at -7.2% YoY.
Yesterday's Recap
China’s September 14 data releases delivered mixed signals. Industrial production expanded 5.2% YoY, above the 4.8% consensus, while retail sales rose just 0.4% YoY against an 0.8% forecast. New yuan loans reached only CNY 60 billion versus CNY 400 billion expected, and fixed-asset investment stayed at -7.2% YoY.
House prices improved modestly to -3.0% YoY. Shanghai Composite fell 0.54% to 3,864.28 and CSI 300 dropped 1.33% to 4,450.04 on the retail miss. Hong Kong’s Hang Seng rose 0.45% to 24,917.60 while TAIEX slipped 0.70%.
USD/CNY eased 0.11% to 6.70 inside the managed band. Copper gained 2.04% to 6.46 and Brent crude rose 2.67% to 108.50 amid supply concerns. Gold slipped 0.43% to 4,333.40; Bitcoin dropped 3.60% to 75,351.50.
Chinese government bond yields were not reported.
The Day Ahead
Taiwan’s central bank holds its quarterly policy meeting at 00:30 ET with inflation still above the 2% alert level. Markets expect the CBC to hold the benchmark rate at 2.00% given semiconductor export resilience. No major mainland data are scheduled, though PBoC liquidity operations and any State Council stimulus signals will be watched closely.
Hong Kong aggregate balance and USD/HKD peg dynamics remain stable near 7.84. Copper and Brent crude price moves will continue to serve as proxies for China demand outlook.
Other Economic Notes
Persistent investment weakness and the retail shortfall increase pressure on Beijing for additional fiscal and monetary support. Yuan appreciation of 4.3% year-to-date has already generated roughly 70 billion yuan in exporter losses, prompting authorities to encourage hedging. Property prices remain soft despite the marginal improvement in the latest reading.
LNG supply agreements between Venture Global and China Gas underscore continued energy import needs. Some manufacturers that earlier shifted production out of China are now returning, citing supply-chain reliability. China’s economy continues to show weakness, with investment slumping and adding urgency for policymakers to step up stimulus.