Greater China Macro Daily(Beta Mode)
China Loan Miss Offsets IP Beat, HKMA RMB Boost
Market Snapshot
| Asset | Level | Change |
|---|---|---|
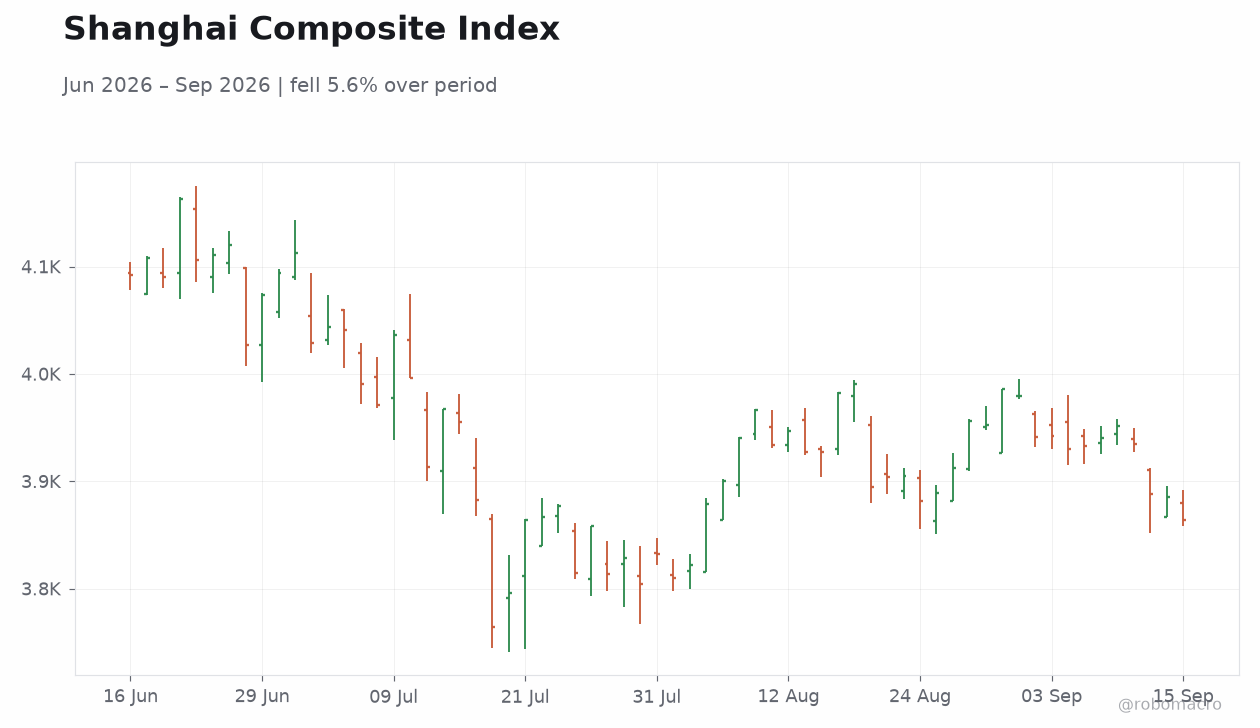
| Shanghai Composite | 3,891.60 | +0.71% |
| CSI 300 | 4,480.27 | +0.68% |
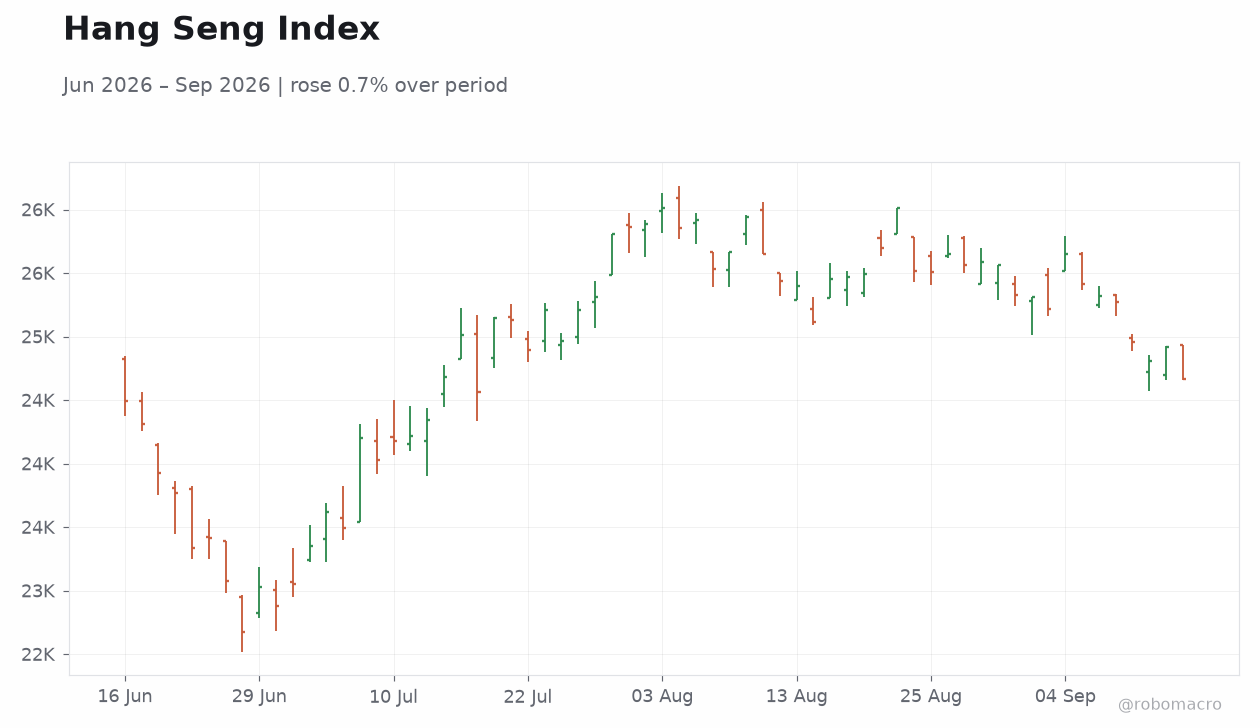
| Hang Seng | 24,667.24 | -1.00% |
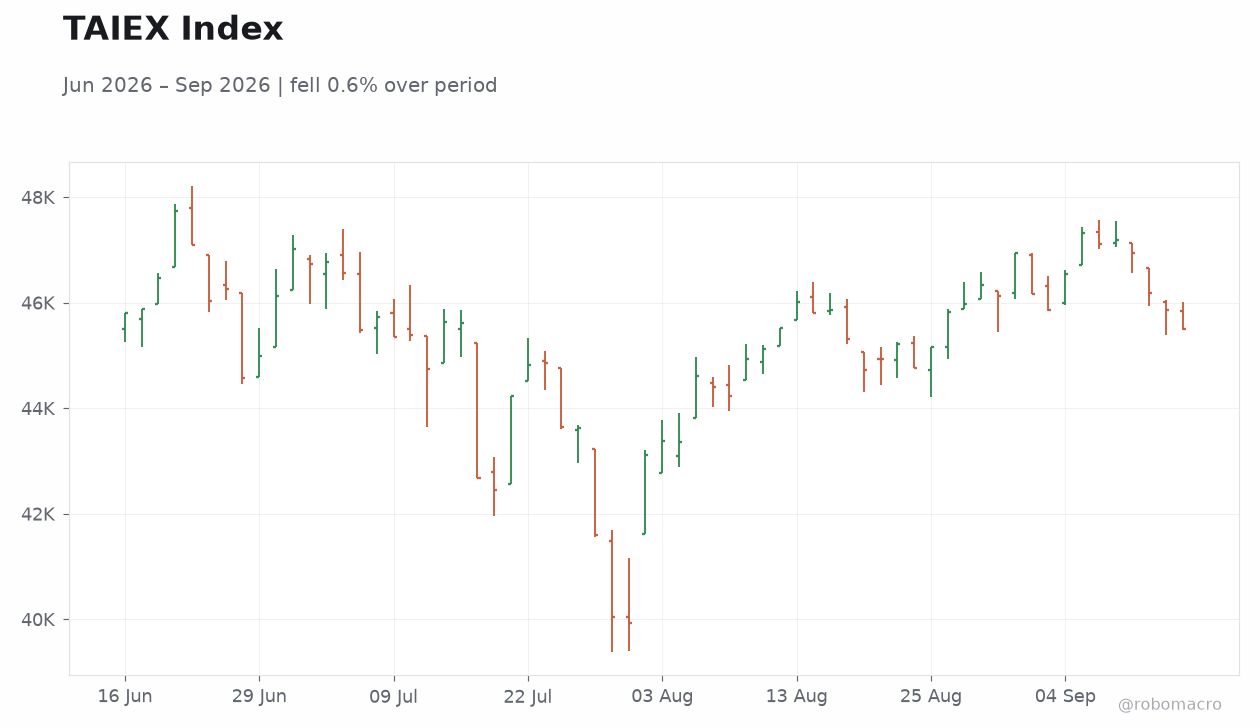
| TAIEX | 45,511.49 | -0.77% |
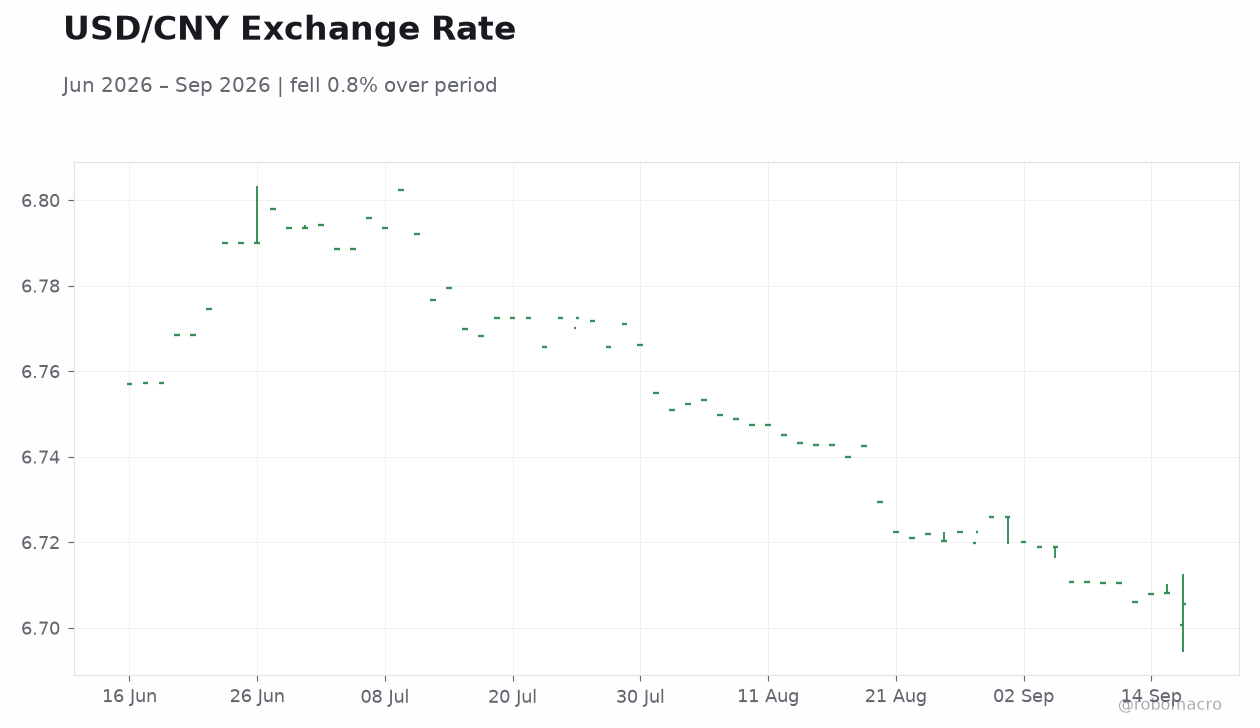
| USD/CNY | 6.71 | -0.04% |
| USD/HKD | 7.84 | +0.01% |
| Copper | 6.44 | +1.15% |
| Brent Crude | 105.60 | -2.90% |
| Gold | 4,302.50 | -0.70% |
| Bitcoin | 75,831.95 | +0.29% |
| China 2Y Govt Yield | - | - |
| China 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| New Yuan Loans Level | -340,000m | 400,000m | 60,000m |
| House Price Index Year-over-Year | -3.20 | - | -3 |
| Industrial Production Year-over-Year | 4.50 | 4.80 | 5.20 |
| Retail Sales Year-over-Year | 0.60 | 0.80 | 0.40 |
| Fixed Asset Investment (Year-to-Date) Year-over-Year | -6.70 | -7.20 | -7.20 |
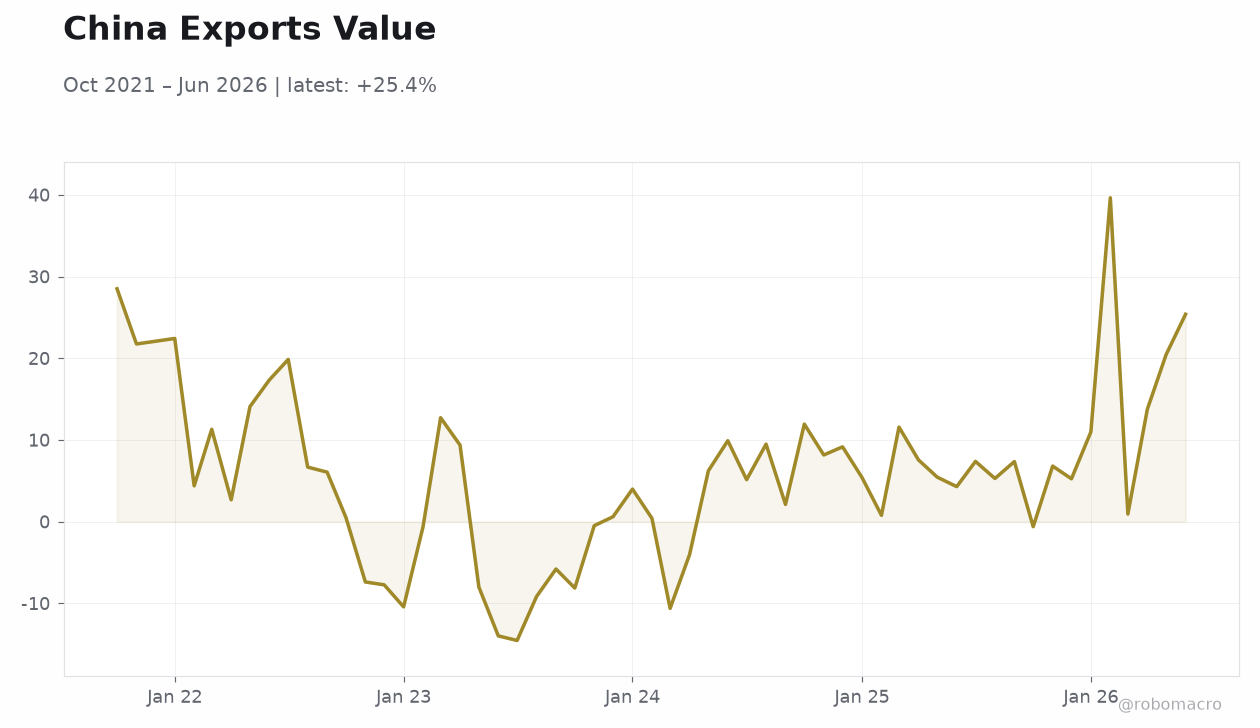 China Exports Value | Type: macro_line | USD mn: 25.39 (2026-06-01) | Range: -14.55–39.64 | Trend(5pt): 28.5,-7.732,0.4113,7.56,25.39
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Central Bank Interest Rate Decision | 2 | 2 | 00:30 |
| Central Bank Interest Rate Decision | 4 | - | 15:59 |
| Thursday (2026-09-17) | |||
| Central Bank Interest Rate Decision | 2 | 2 | 00:30 |
| Central Bank Interest Rate Decision | 4 | - | 15:59 |
- China New Yuan Loans at CNY 60 billion missed consensus by wide margin while Industrial Production beat expectations at 5.2% YoY.
- HKMA announced 7-day offshore yuan tender and expanded RMB funding facility to CNY 500 billion to bolster liquidity.
- Taiwan and Hong Kong central banks scheduled to announce policy rates today with consensus for no change.
Yesterday's Recap
Mainland China data released on September 14 showed uneven momentum. New Yuan Loans printed CNY 60 billion, far below the CNY 400 billion consensus, signaling subdued credit demand. Industrial Production rose 5.2% YoY, exceeding the 4.8% forecast and providing a modest positive.
Retail Sales grew only 0.4% YoY against an 0.8% expectation, while Fixed Asset Investment YTD contracted 7.2% YoY in line with forecasts. House prices fell 3.0% YoY, easing from the prior 3.2% decline. Equity markets diverged: Shanghai Composite rose 0.71% to 3,891.60 and CSI 300 gained 0.68% to 4,480.27, while Hang Seng dropped 1.00% to 24,667.24 and TAIEX fell 0.77% to 45,511.49.
USD/CNY eased 0.04% to 6.71 amid the mixed domestic signals. Copper gained 1.15% to 6.44 while Brent Crude fell 2.90% to 105.60, reflecting divergent commodity signals tied to China’s industrial outlook.
The Day Ahead
Taiwan’s Central Bank will announce its policy rate at 00:30 ET with consensus unchanged at 2.00%. Hong Kong’s Monetary Authority is due to release its rate decision at 15:59 ET, with the pegged rate expected to remain at 4.0%. No PBoC MLF operations or State Council policy signals are flagged.
Markets will monitor any commentary on semiconductor export trends from the CBC meeting given Taiwan’s critical role in global supply chains. Offshore yuan liquidity conditions may also draw attention following yesterday’s HKMA facility expansion. Broader Asian shares wavered ahead of Fed and BOJ meetings, with yen movements adding volatility to regional flows.
Other Economic Notes
Persistent weakness in fixed-asset investment and retail sales continues to pressure policymakers for additional stimulus measures. The HKMA’s new 7-day offshore yuan tender and CNY 500 billion facility expansion aim to deepen RMB liquidity in Hong Kong and support the currency’s offshore market. China’s August CPI at 0.80% YoY remains contained, leaving room for further easing if credit growth stays soft.
Property sector stabilization remains a key focus, with the modest improvement in house-price declines offering limited relief. LNG demand recovery in China remains contingent on easing Middle East supply constraints.