Greater China Macro Daily(Beta Mode)
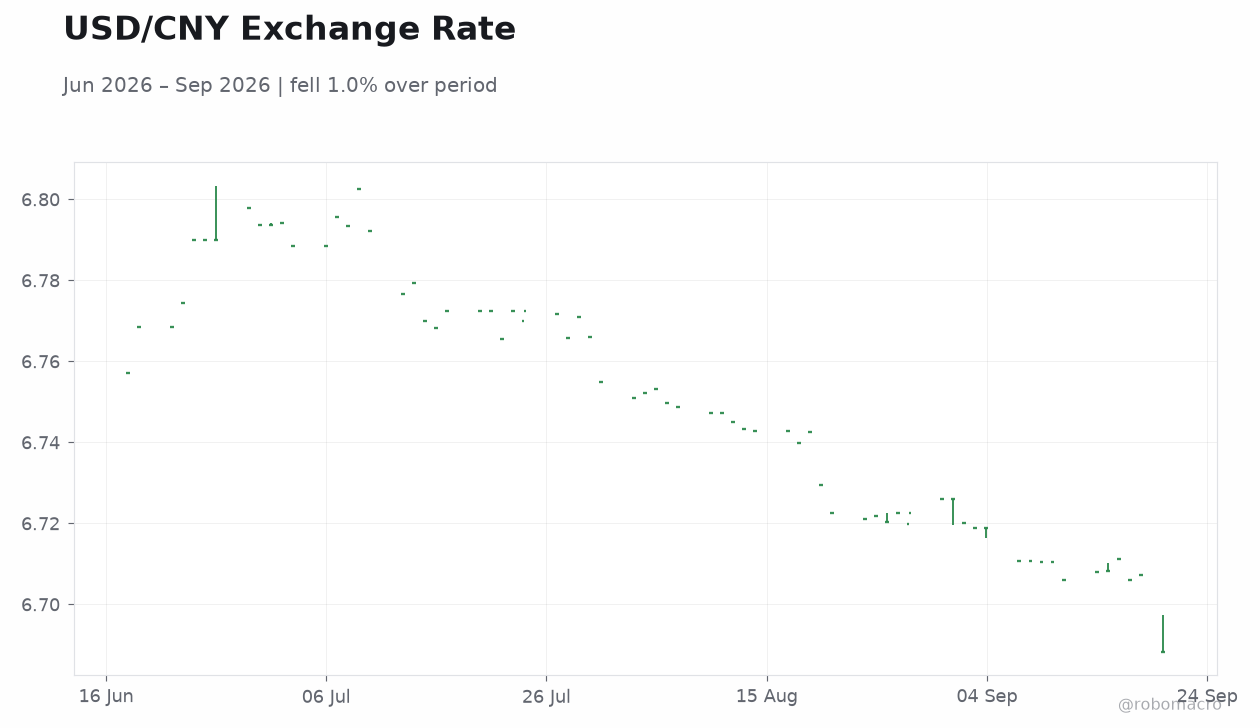
Yuan Hits Four-Year High Before Trump-Xi Summit
Market Snapshot
| Asset | Level | Change |
|---|---|---|
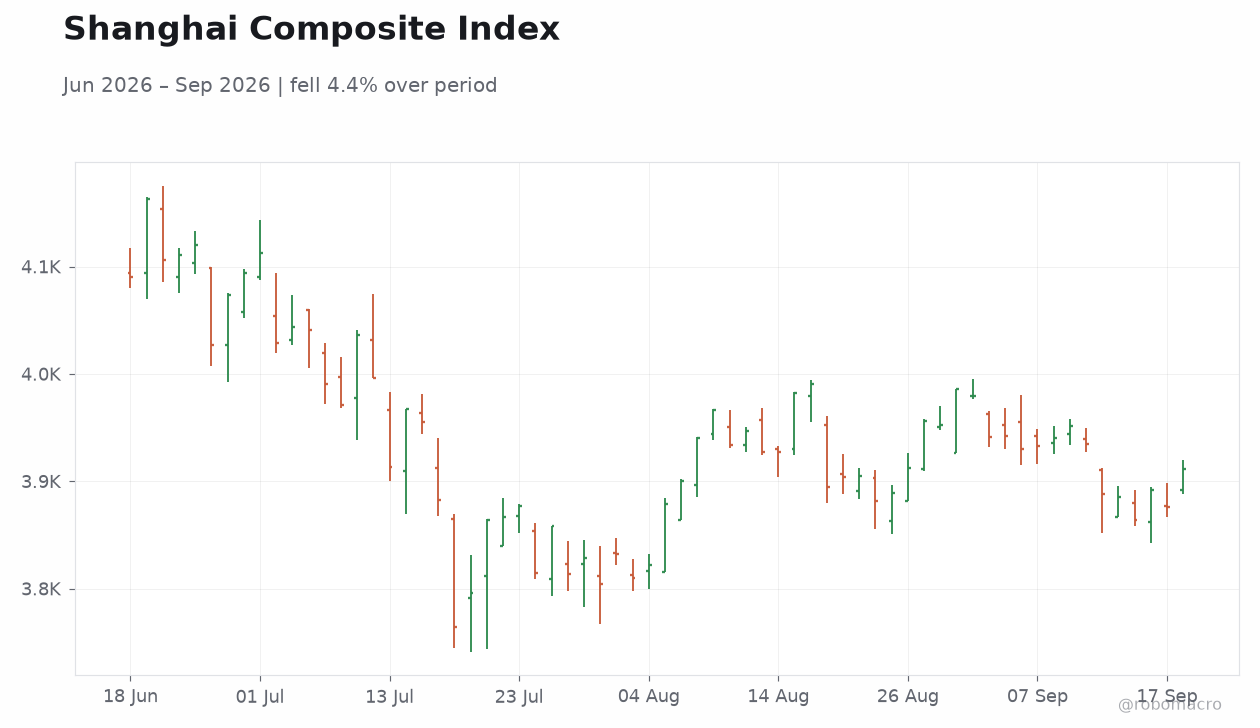
| Shanghai Composite | 3,911.87 | +0.94% |
| CSI 300 | 4,507.39 | +1.06% |
| Hang Seng | 24,750.78 | +0.60% |
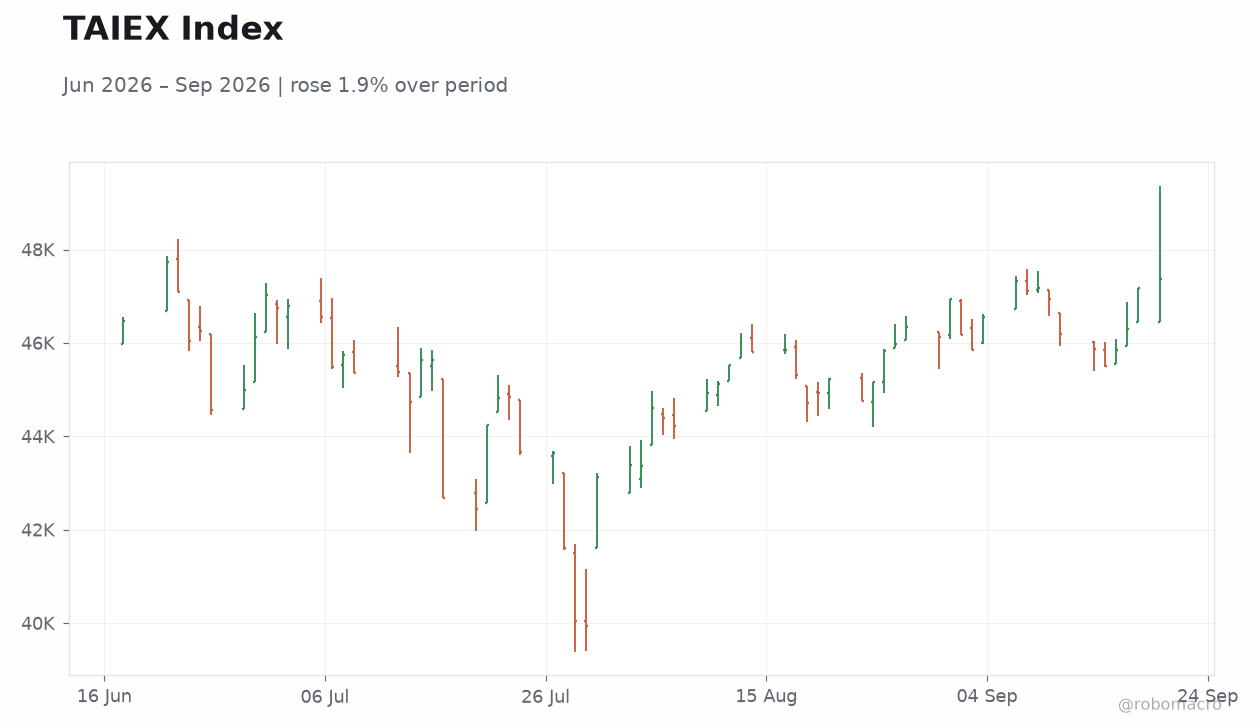
| TAIEX | 47,368.04 | +0.40% |
| USD/CNY | 6.69 | -0.28% |
| USD/HKD | 7.84 | -0.01% |
| Copper | 6.69 | +1.59% |
| Brent Crude | 99.29 | -5.28% |
| Gold | 4,424.90 | +0.57% |
| Bitcoin | 80,933.20 | -0.37% |
| China 2Y Govt Yield | - | - |
| China 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
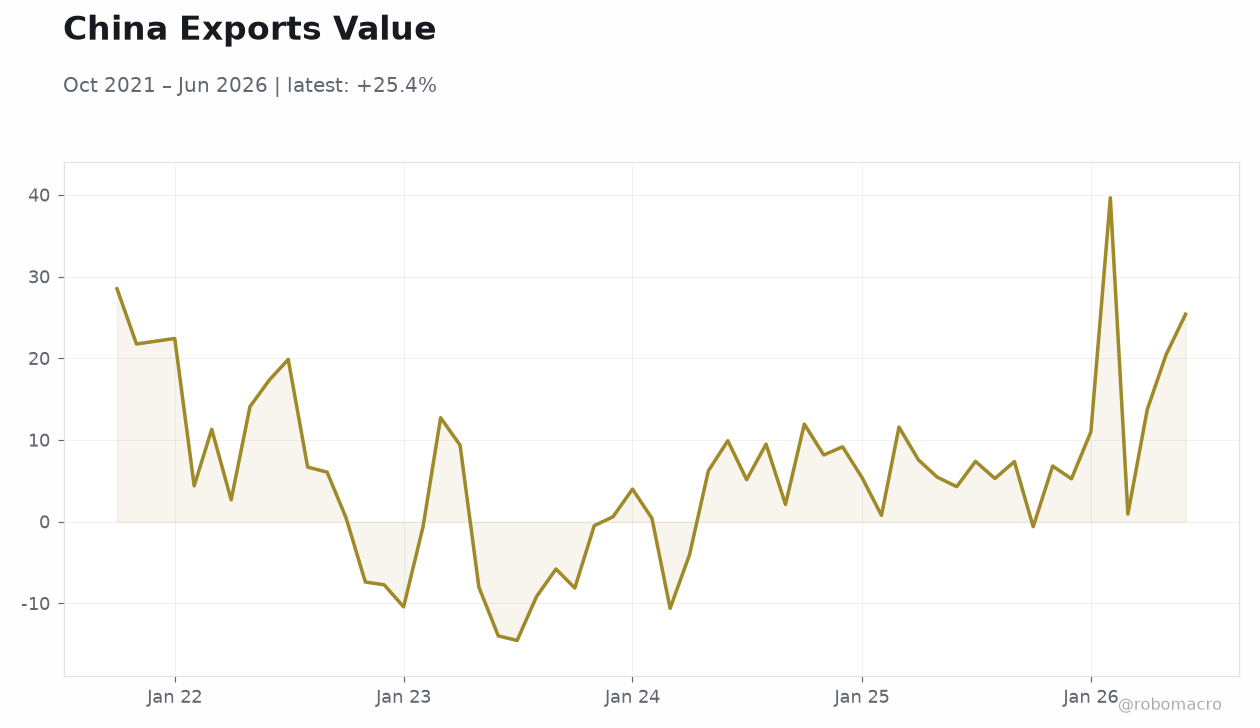 China Exports Value | Type: macro_line | USD mn: 25.39 (2026-06-01) | Range: -14.55–39.64 | Trend(5pt): 28.5,-7.732,0.4113,7.56,25.39
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Loan Prime Rate 1Y | 3 | 3 | 21:15 |
| Loan Prime Rate 5Y | 3.50 | 3.50 | 21:15 |
| Monday (2026-09-21) | |||
| Loan Prime Rate 1Y | 3 | 3 | 21:15 |
| Loan Prime Rate 5Y | 3.50 | 3.50 | 21:15 |
- Yuan strengthens to strongest level since 2022 ahead of Trump-Xi summit amid US-China tariff talks.
- Mainland equities lead regional gains with Shanghai Composite up 0.94% and CSI 300 up 1.06%.
- China’s LPR 1Y and 5Y rates set for decision tonight with consensus for no change.
Yesterday's Recap
Mainland China equities posted solid gains as the Shanghai Composite rose 0.94% to 3,911.87 and the CSI 300 advanced 1.06% to 4,507.39. Hong Kong’s Hang Seng Index climbed 0.60% to 24,750.78 while Taiwan’s TAIEX gained 0.40% to 47,368.04. The yuan strengthened sharply, with USD/CNY falling 0.28% to 6.69, reaching its strongest level since 2022 and a four-year high ahead of the Trump-Xi summit.
No major data releases occurred across mainland China, Hong Kong or Taiwan. US Treasury Secretary Bessent and China’s He prepared for Sunday talks at JPMorgan headquarters covering tariffs, LNG, AI and critical minerals, with the US deferring new tariff moves until after the summit. HKMA data showed a surge in Hong Kong credit-card usage for Q2 2026.
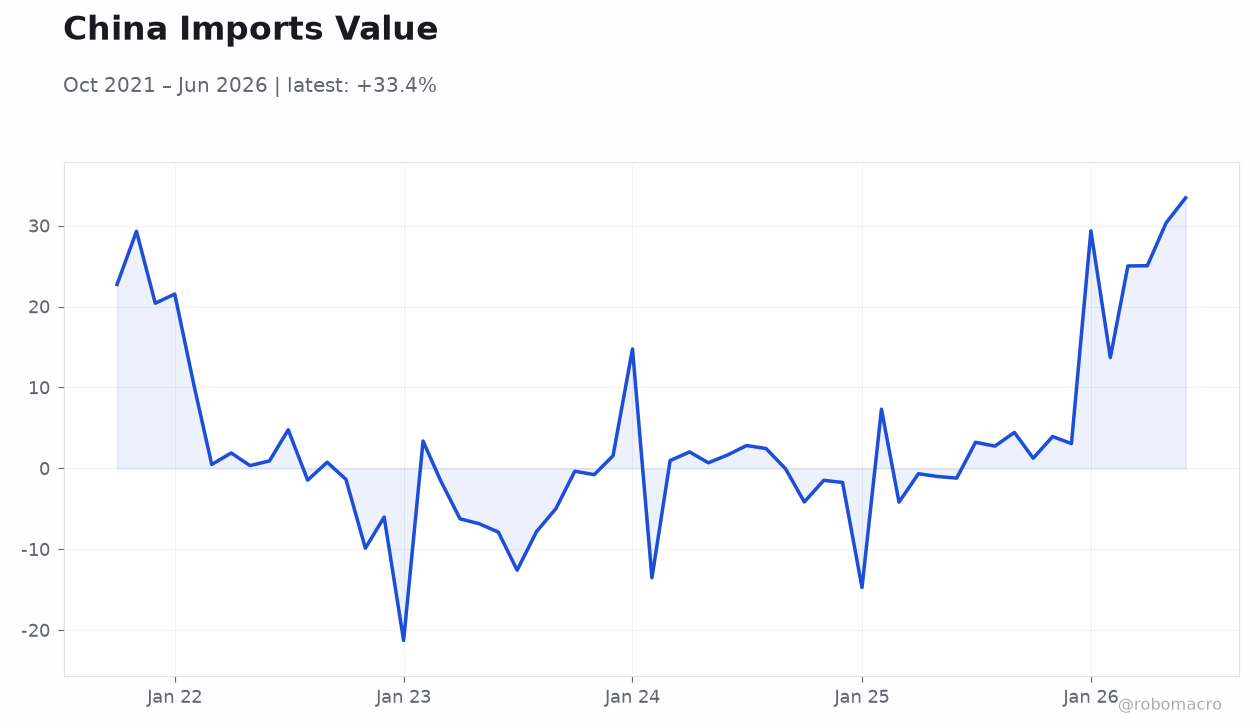
Copper advanced 1.59% to 6.69 while Brent crude fell 5.28% to 99.29, offering a modest tailwind for China’s import bill. Gold rose 0.57% to 4,424.90 and Bitcoin eased 0.37% to 80,933.20. USD/HKD held steady at 7.84.
The Day Ahead
China’s Loan Prime Rate 1Y and 5Y decisions are scheduled for release at 21:15 ET, with consensus pointing to unchanged prints at 3.0% and 3.5% respectively. No PBoC open-market operations or liquidity injections are flagged for today. HKMA is expected to maintain its mechanical defense of the USD/HKD peg near 7.84 following the recent base-rate increase to 4.25%.
CBC has no policy meetings or FX intervention signals on the calendar. State Council policy announcements are also absent. Markets will focus on any signals around yuan policy management ahead of next week’s summit.
The mechanical link between HKMA and Fed policy continues to anchor Hong Kong borrowing costs, while Taiwan’s central bank remains focused on semiconductor export performance as the key growth driver.
Other Economic Notes
Beijing appears to be slow-walking further yuan appreciation despite the recent rally, responding to US and European calls for trade rebalancing. The upcoming Bessent-He discussions on tariffs and LNG could ease bilateral tensions and support commodity flows into mainland China. Copper’s advance reinforces the view that industrial demand remains resilient despite global growth concerns.
↓ p.2