Greater China Macro Daily(Beta Mode)
Yuan Peaks Ahead of Trump-Xi Summit
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| Shanghai Composite | 3,911.87 | +0.94% |
| CSI 300 | 4,507.39 | +1.06% |
| Hang Seng | 24,750.78 | +0.60% |
| TAIEX | 47,180.75 | +1.93% |
| USD/CNY | 6.69 | -0.19% |
| USD/HKD | 7.84 | -0.01% |
| Copper | 6.79 | +2.68% |
| Brent Crude | 95.96 | -7.62% |
| Gold | 4,381.00 | -0.99% |
| Bitcoin | 86,564.02 | +6.68% |
| China 2Y Govt Yield | - | - |
| China 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
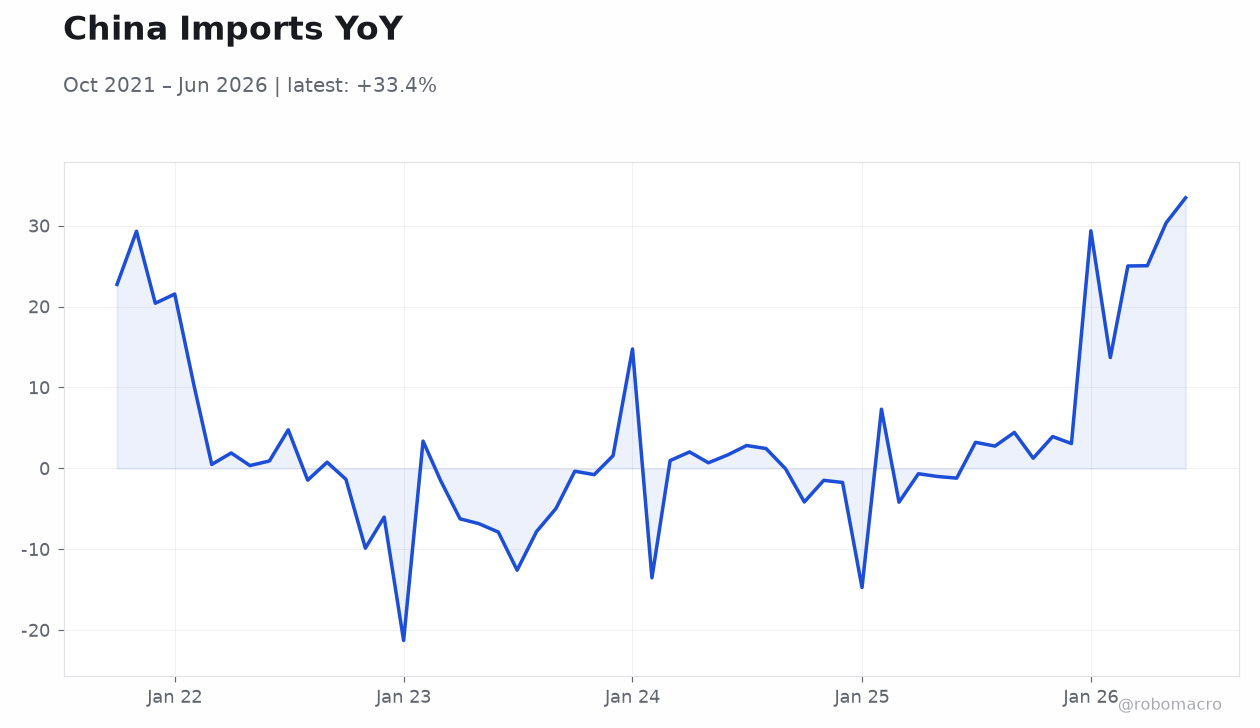
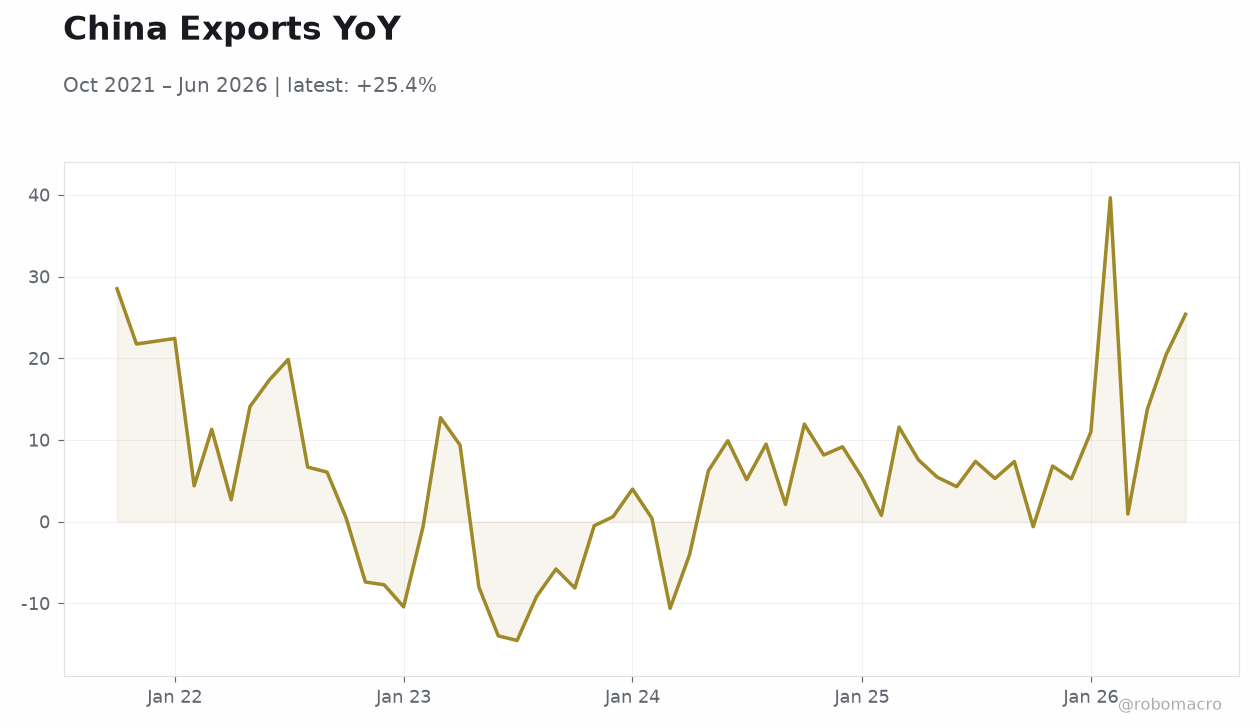 China Exports YoY | Type: macro_line | YoY %: 25.39 (2026-06-01) | Range: -14.55–39.64 | Trend(5pt): 28.5,-7.732,0.4113,7.56,25.39
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
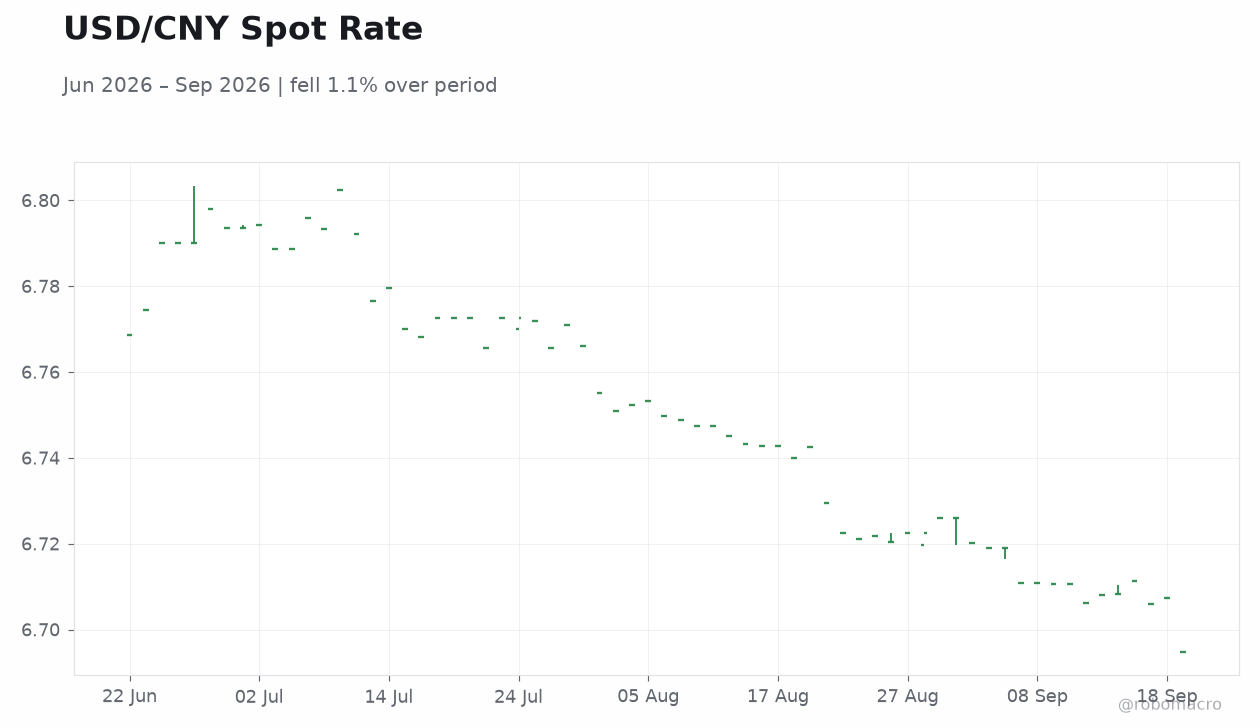
- PBOC eased yuan controls, lifting the currency to its strongest level since 2022 at USD/CNY 6.69.
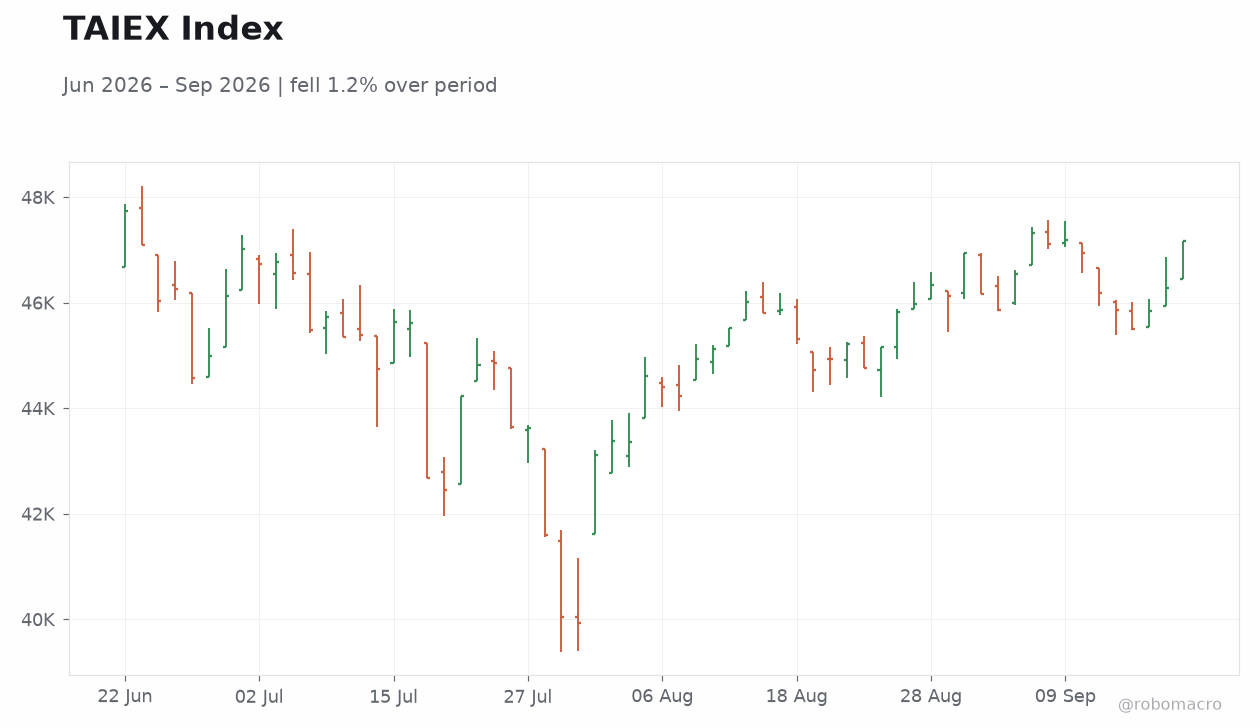
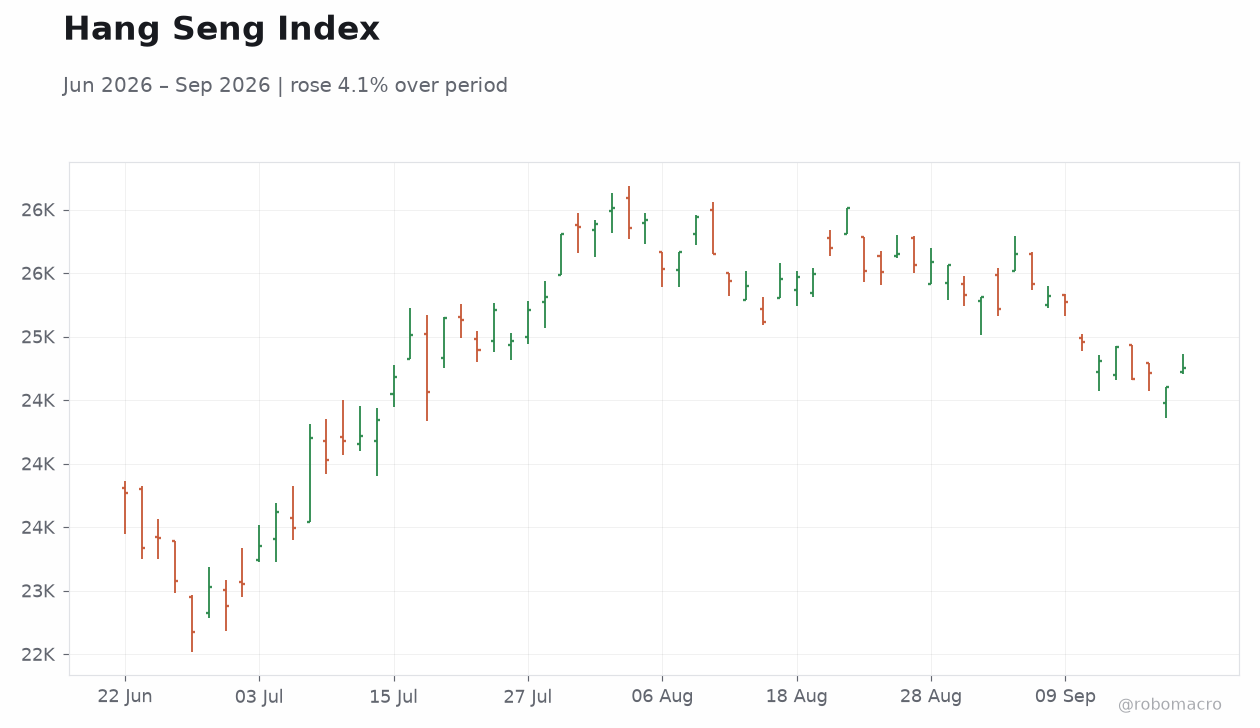
- Greater China equities advanced, led by TAIEX (+1.93%) and CSI 300 (+1.06%), while copper rose 2.68%.
- HKMA raised base rate to 4.25% after the Fed hike; no macro data releases occurred across the region.
Yesterday's Recap
Equity markets across Greater China posted solid gains on 20 September. The Shanghai Composite climbed 0.94% to 3,911.87 while the CSI 300 advanced 1.06% to 4,507.39. The Hang Seng Index rose 0.60% to 24,750.78 and the TAIEX outperformed with a 1.93% gain to 47,180.75.
The yuan strengthened sharply as the PBOC eased appreciation curbs, sending USD/CNY down 0.19% to 6.69 and marking a fresh multi-year high. USD/HKD remained stable at 7.84. No economic data were released for mainland China, Hong Kong or Taiwan.
In Hong Kong, the HKMA reported a surge in credit-card usage for Q2 2026, signaling resilient consumer spending under the currency-board regime. Copper, a key China growth proxy, rose 2.68% to 6.79 while Brent crude fell 7.62% to 95.96. China’s August CPI printed 0.80% YoY, providing a stable inflation backdrop.
The Day Ahead
The calendar for 21-22 September remains empty of scheduled releases or policy meetings for mainland China, Hong Kong and Taiwan. Markets will focus on any incremental PBOC signals regarding yuan management ahead of the Trump-Xi summit. Preparations for bilateral trade and AI notification talks will dominate attention.
Hong Kong banks are expected to maintain lending rates following the HKMA’s 4.25% base-rate decision. Semiconductor supply-chain developments in Taiwan will continue to draw scrutiny given the sector’s export sensitivity. Investors will also monitor cross-strait trade flows and any State Council liquidity guidance.
Property-sector sentiment in mainland China continues to hinge on incremental credit support rather than outright stimulus.
Other Economic Notes
Beijing is slow-walking further yuan appreciation despite US and European calls for trade rebalancing, according to Nikkei Asia. US Trade Representative Jamieson Greer and Treasury Secretary Scott Bessent both referenced ongoing China trade discussions, with Bessent proposing a US-China AI dialogue system for the upcoming summit. Hong Kong’s currency-board mechanics remain anchored, with the HKMA aggregate balance and peg dynamics showing no stress despite the recent base-rate adjustment.
The HKMA reported an increase in stored-value facility accounts and transactions for Q2 2026. ↓ p.2