Greater China Macro Daily(Beta Mode)
Yuan Peaks Ahead of Trump-Xi Summit
Market Snapshot
| Asset | Level | Change |
|---|---|---|
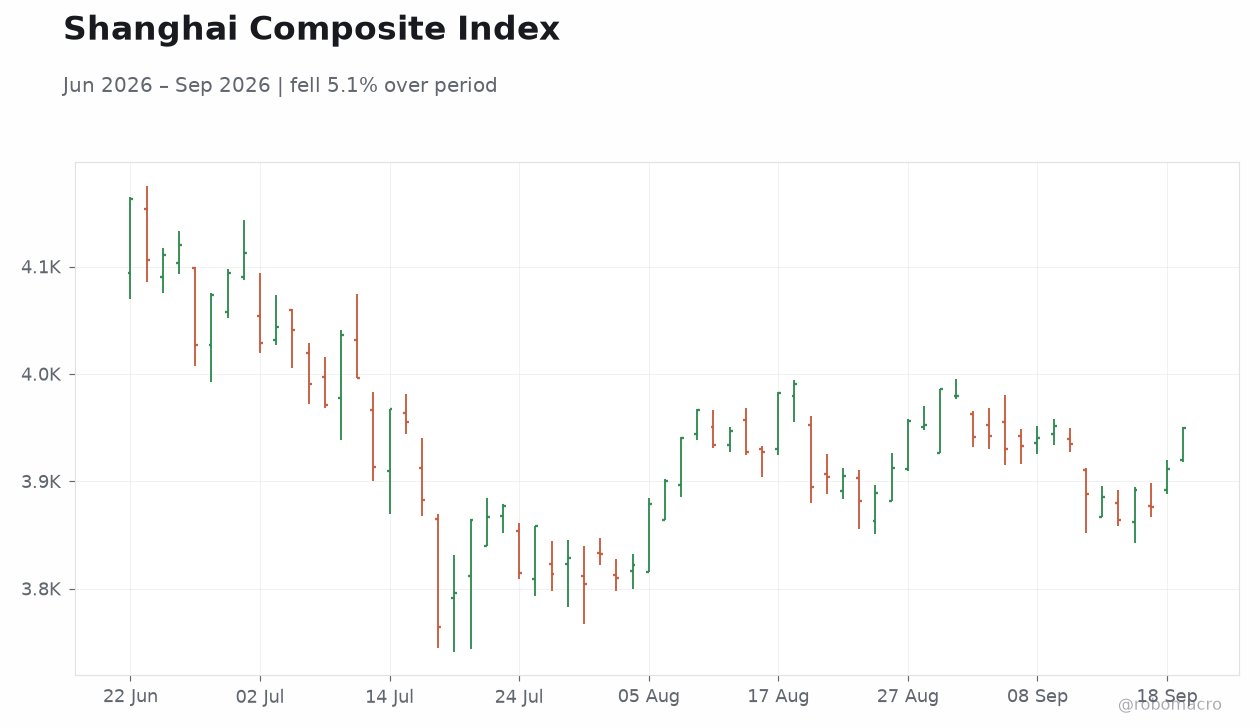
| Shanghai Composite | 3,952.13 | +0.06% |
| CSI 300 | 4,544.59 | +0.83% |
| Hang Seng | 25,042.71 | +1.18% |
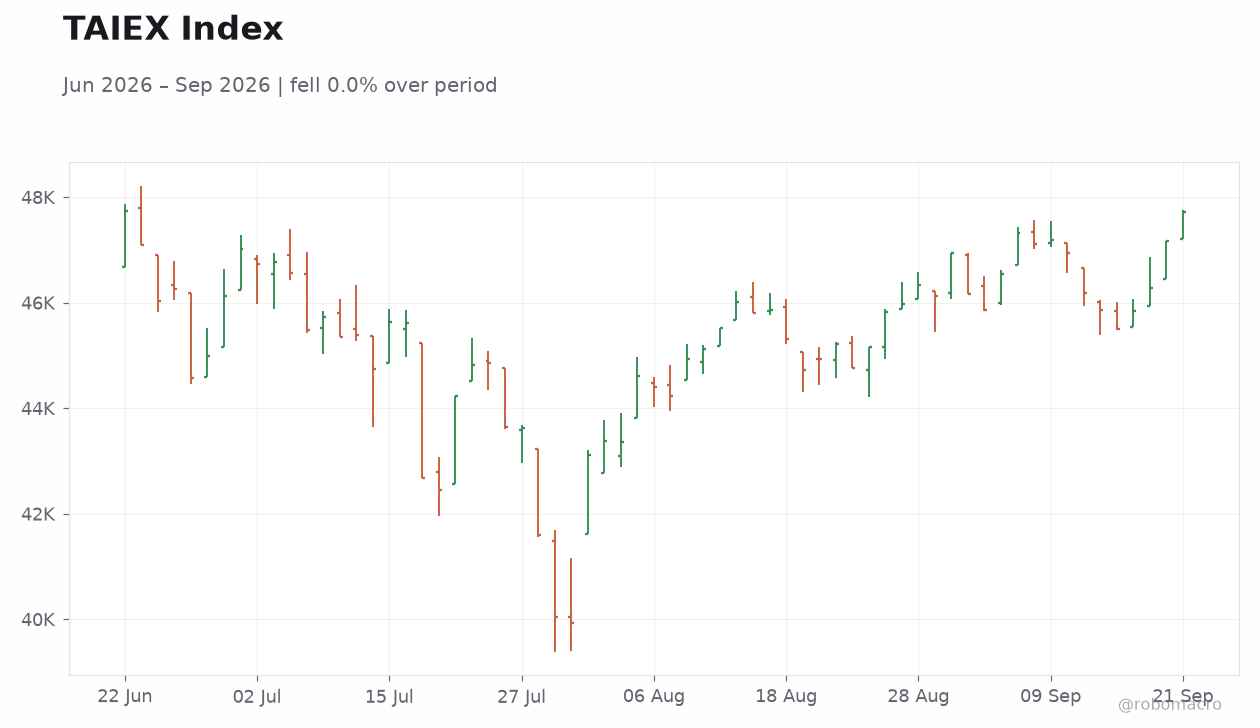
| TAIEX | 47,718.84 | +1.14% |
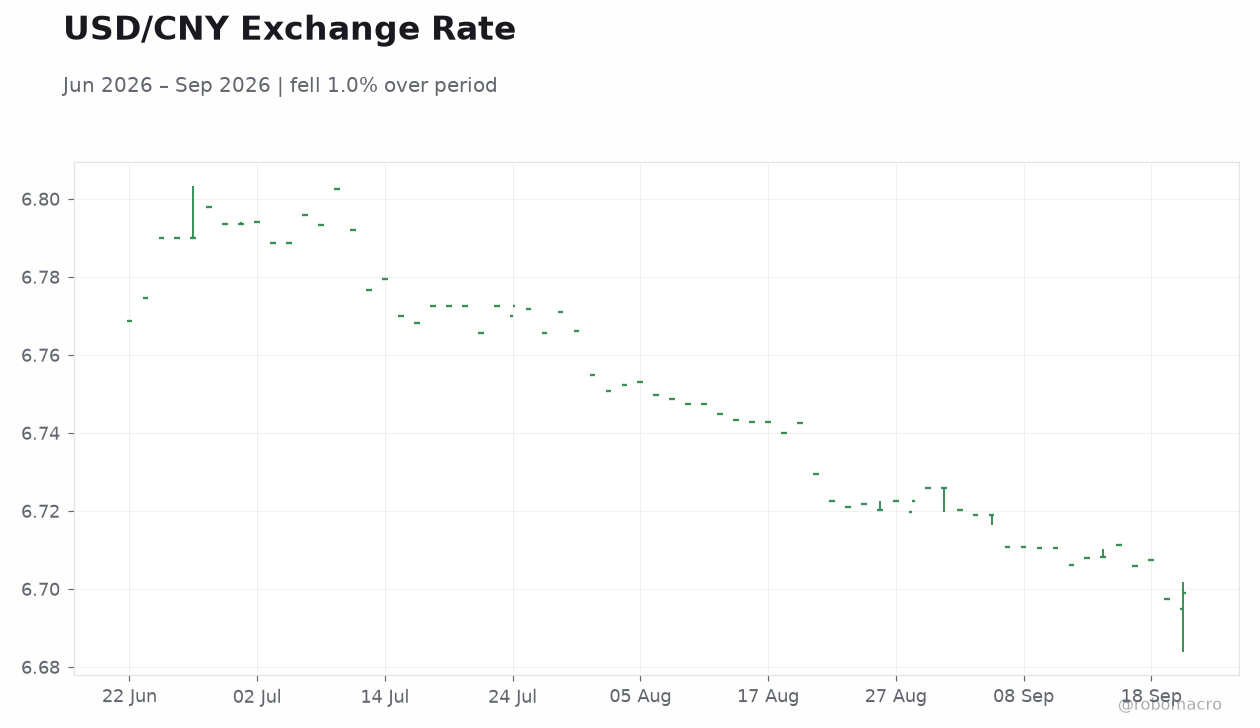
| USD/CNY | 6.70 | +0.02% |
| USD/HKD | 7.84 | -0.02% |
| Copper | 6.91 | +3.27% |
| Brent Crude | 98.65 | -1.68% |
| Gold | 4,396.20 | +0.28% |
| Bitcoin | 86,257.59 | -0.40% |
| China 2Y Govt Yield | - | - |
| China 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
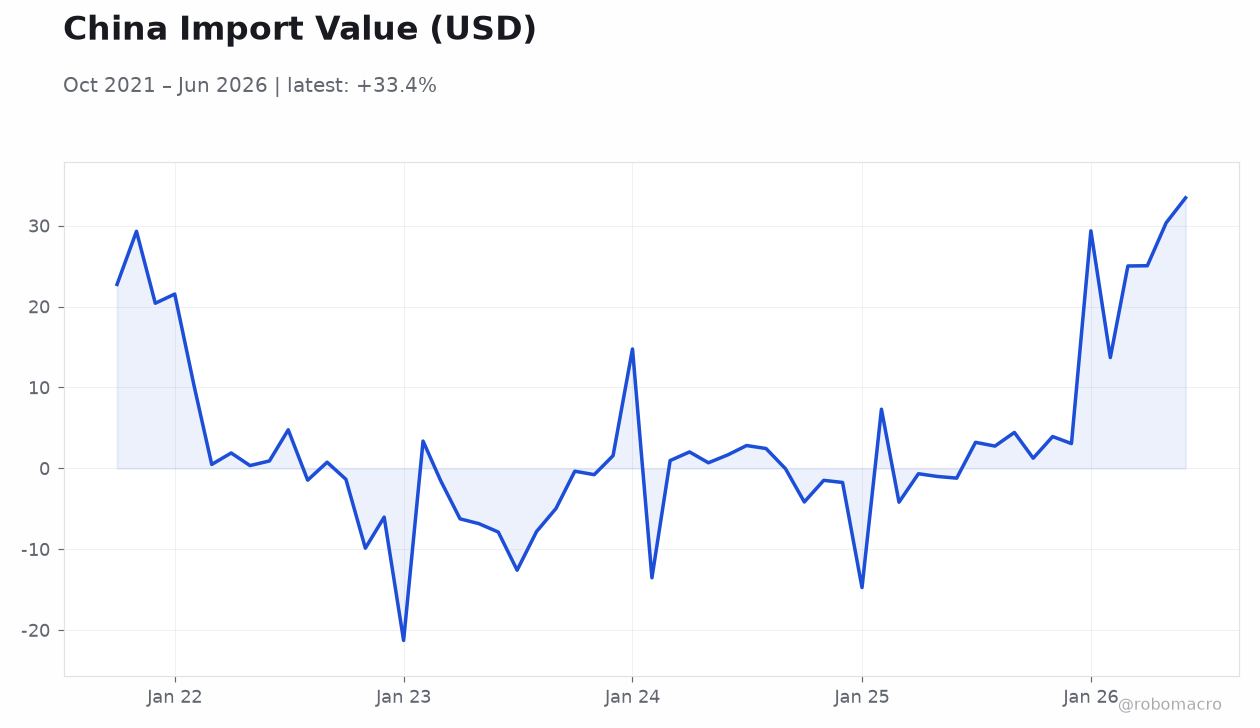
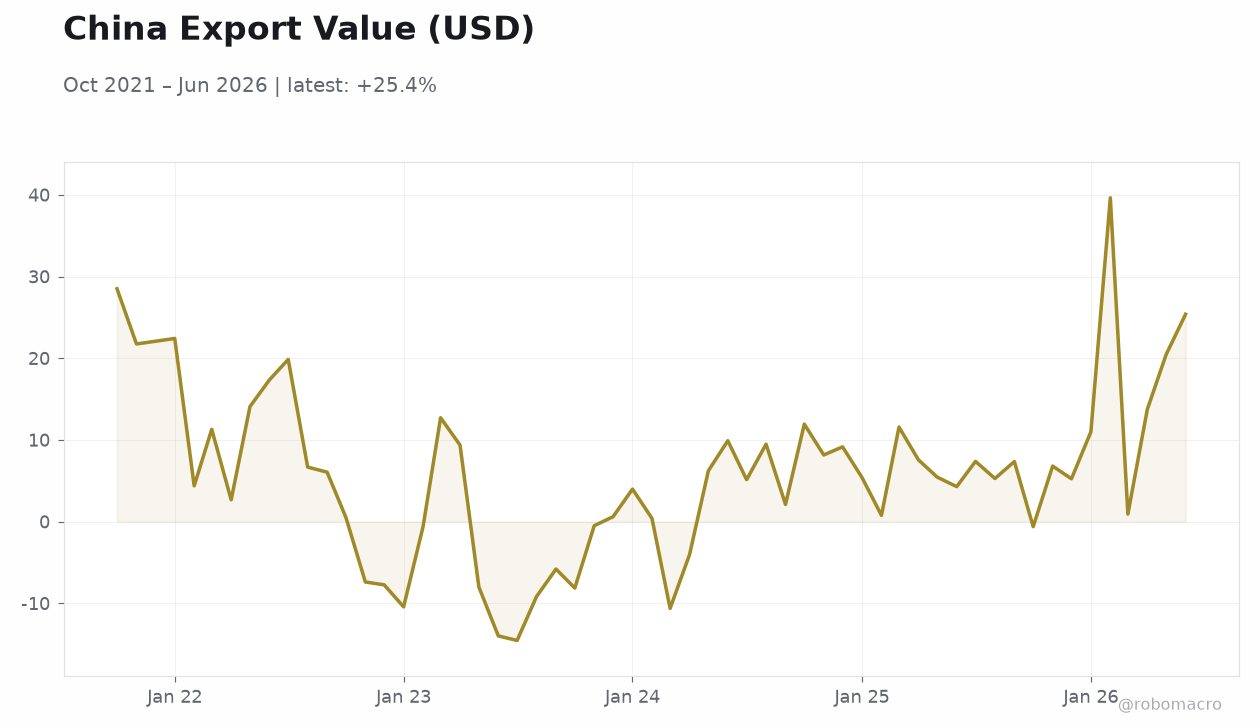 China Export Value (USD) | Type: macro_line | USD billion: 25.39 (2026-06-01) | Range: -14.55–39.64 | Trend(5pt): 28.5,-7.732,0.4113,7.56,25.39
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Equity markets across Greater China posted modest gains while the yuan reached a fresh multi-year high after the PBoC eased select curbs.
- No macroeconomic data releases occurred in mainland China, Hong Kong or Taiwan on 21 September.
- PBOC signals on financial opening-up and a 40% share of global container exports underscored China’s trade dependence ahead of the Trump-Xi meeting.
Yesterday's Recap
Equity benchmarks closed higher across Greater China on 21 September. The Shanghai Composite rose 0.06% to 3,952.13 while the CSI 300 advanced 0.83% to 4,544.59. The Hang Seng Index gained 1.18% to 25,042.71 and the TAIEX added 1.14% to 47,718.84.
USD/CNY finished at 6.70 after the yuan touched a multi-year peak following PBoC measures to ease certain restrictions ahead of the Trump-Xi summit. USD/HKD edged 0.02% lower to 7.84. Copper climbed 3.27% to 6.91 while Brent Crude fell 1.68% to 98.65 and gold rose 0.28% to 4,396.20.
No economic releases were reported for mainland China, Hong Kong or Taiwan. China’s share of global container exports reached 40%, highlighting continued trade reliance. Gold imports exceeded 1,000 tonnes amid firm yuan demand.
The most recent China CPI reading stood at 0.80% YoY as of 31 August.
The Day Ahead
Markets will monitor the PBoC’s expected USD/CNY reference rate of 6.6989. Attention remains on the Trump-Xi summit and any signals on trade or AI hotlines. HKMA green taxonomy updates and potential wholesale CBDC developments may draw follow-up commentary.
Taiwan semiconductor order books, already above the USD 100 billion annual mark, continue to reflect AI-driven demand. Property-sector sentiment in Hong Kong will be watched for resilience against any hawkish Fed signals. No major data prints are scheduled for mainland China, Hong Kong or Taiwan on 22 September.
Other Economic Notes
Mainland China’s economy continues to lean heavily on external demand, with container export share at 40% raising concerns among trading partners. Strong gold imports above 1,000 tonnes reflect investor preference for the metal amid a firmer yuan and expectations of lower prices. The PBoC’s pledge of high-level financial opening-up aims to attract inflows while managing currency volatility.
Hong Kong’s property recovery shows resilience despite external rate pressures, supported by local liquidity conditions. Taiwan’s export order surge underscores its central role in global technology supply chains.