RoboMacro ResearchAlso todaySee the Equities Daily

Greater China Macro Daily(Beta Mode)

September 27, 2026 robomacro.com

China Shares Slide on U.S.-China Tariff Deal

Shanghai Composite3,888.37-1.22%
CSI 3004,439.14-1.73%
Hang Seng24,510.09-1.01%
TAIEX48,024.60-0.28%

Market Snapshot

AssetLevelChange
Shanghai Composite3,888.37-1.22%
CSI 3004,439.14-1.73%
Hang Seng24,510.09-1.01%
TAIEX48,024.60-0.28%
USD/CNY6.70-0.11%
USD/HKD7.84+0.01%
Copper6.77+0.71%
Brent Crude97.44-8.59%
Gold4,321.20+0.54%
Bitcoin84,626.01+0.26%
China 2Y Govt Yield--
China 10Y Govt Yield--

Prior Economic Events

Data Prior Cons Actual
No events available
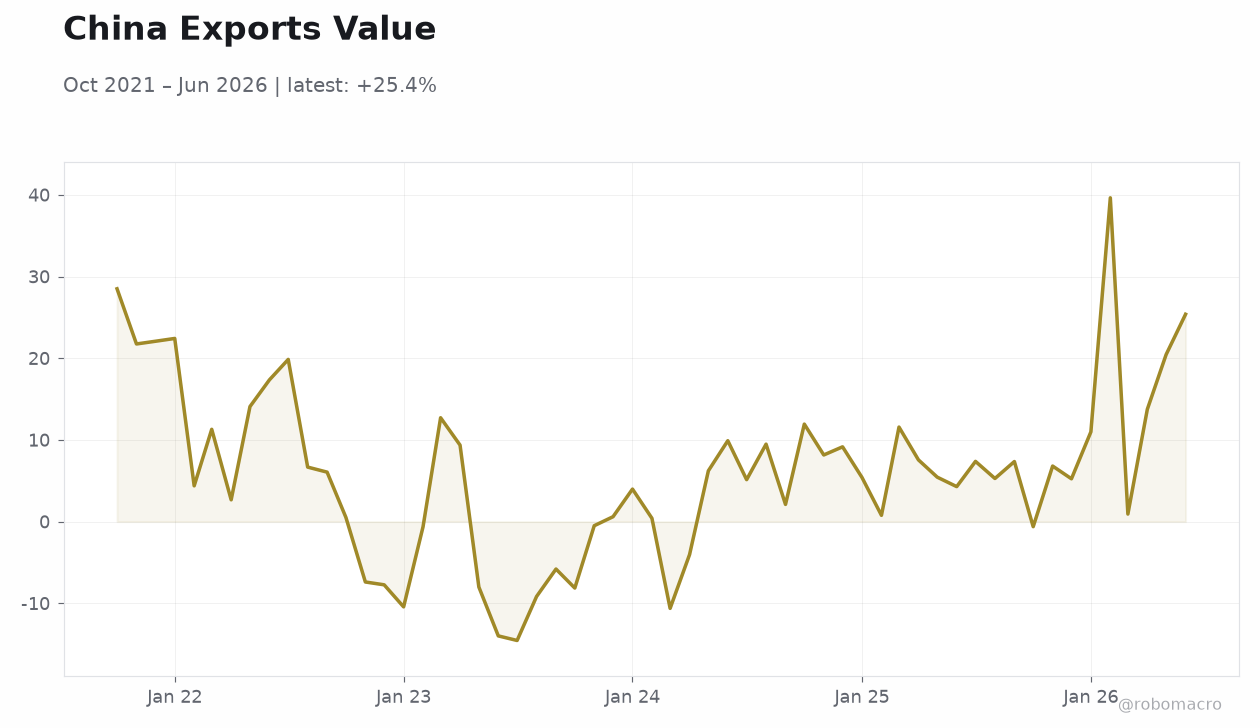
China Exports ValueChina Exports Value | Type: macro_line | USD mn: 25.39 (2026-06-01) | Range: -14.55–39.64 | Trend(5pt): 28.5,-7.732,0.4113,7.56,25.39

Today's Economic Events

Data Prior Cons Time
No events available
  • Shanghai Composite fell 1.22% to 3,888.37 while CSI 300 dropped 1.73% to 4,439.14 on thin volumes.
  • US and China agreed to cut tariffs on $30 billion of non-sensitive goods and launch an AI dialogue channel after summit talks.
  • Brent crude plunged 8.59% to 97.44 as USD/CNY eased 0.11% to 6.70 with HKD peg holding steady at 7.84.

Yesterday's Recap

Equity markets across Greater China posted broad losses on September 26 with no offsetting economic data releases from mainland China, Hong Kong or Taiwan. The Shanghai Composite closed at 3,888.37, down 1.22%, while the CSI 300 fell 1.73% to 4,439.14 amid limited domestic catalysts. Hong Kong’s Hang Seng Index declined 1.01% to 24,510.09 and Taiwan’s TAIEX eased 0.28% to 48,024.60.

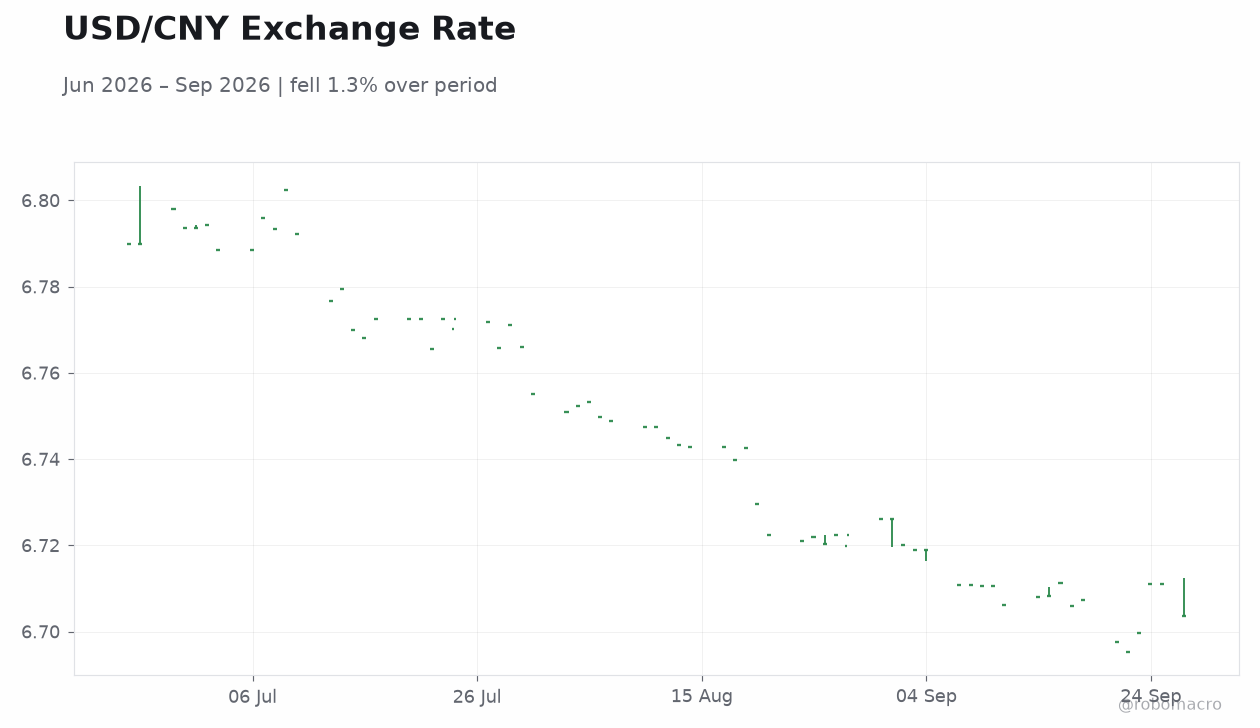
USD/CNY traded 0.11% lower at 6.70, reflecting modest yuan support, while USD/HKD remained anchored at 7.84. Copper rose 0.71% to 6.77 as a China demand proxy, yet Brent crude’s sharp 8.59% drop to 97.44 weighed on sentiment. US-China summit outcomes dominated headlines, including a tariff reduction pact on $30 billion of goods and a new “super intelligence” AI dialogue to manage incidents.

No PBoC liquidity operations, HKMA interventions or CBC policy signals emerged during the session. China’s exchange-rate policy drew continued scrutiny for supporting exports amid global supply-chain shifts, with no fresh property stimulus reported.

The Day Ahead

The Greater China calendar remains empty through September 28 with zero scheduled releases or central-bank operations across mainland China, Hong Kong and Taiwan. Markets will track follow-through from the US-China tariff agreement and any early signals on implementation timelines. Attention may shift to ongoing yuan policy commentary and its implications for export competitiveness.

HKMA will continue monitoring USD/HKD peg mechanics amid stable aggregate balance levels. Taiwan semiconductor supply-chain flows face no immediate cross-strait disruptions but remain sensitive to broader US export-control updates. Investors should watch for any State Council liquidity guidance that could influence PBoC open-market operations later in the week.

Hong Kong property conversions of hotels into student dorms highlight ongoing hospitality weakness without altering broader market drivers.

Other Economic Notes

China’s exchange-rate policy continues to draw scrutiny for its role in supporting exports and reshaping supply chains amid global trade realignment. Hong Kong property owners are converting hotels into student dormitories to address accommodation shortages, highlighting persistent hospitality-sector weakness. ↓ p.2
Page 1

Greater China Macro Daily(Beta Mode)

September 27, 2026 robomacro.com
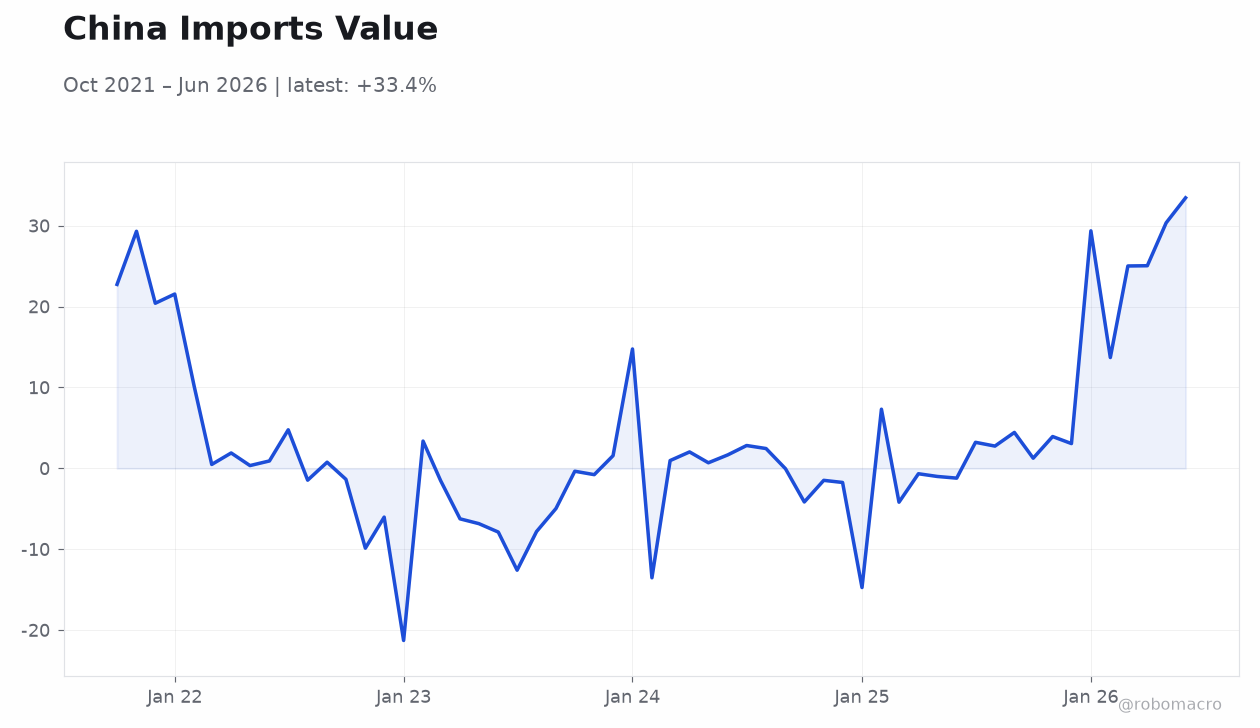
China Imports Value China Imports Value | Type: macro_line | USD mn: 33.45 (2026-06-01) | Range: -21.28–33.45 | Trend(5pt): 22.74,-6.027,-13.53,-0.665,33.45
USD/CNY Exchange Rate USD/CNY Exchange Rate | Type: market_hloc | Rate: 6.704 (2026-09-27) | Range: 6.695–6.802 | Trend(5pt): 6.79,6.773,6.745,6.719,6.704
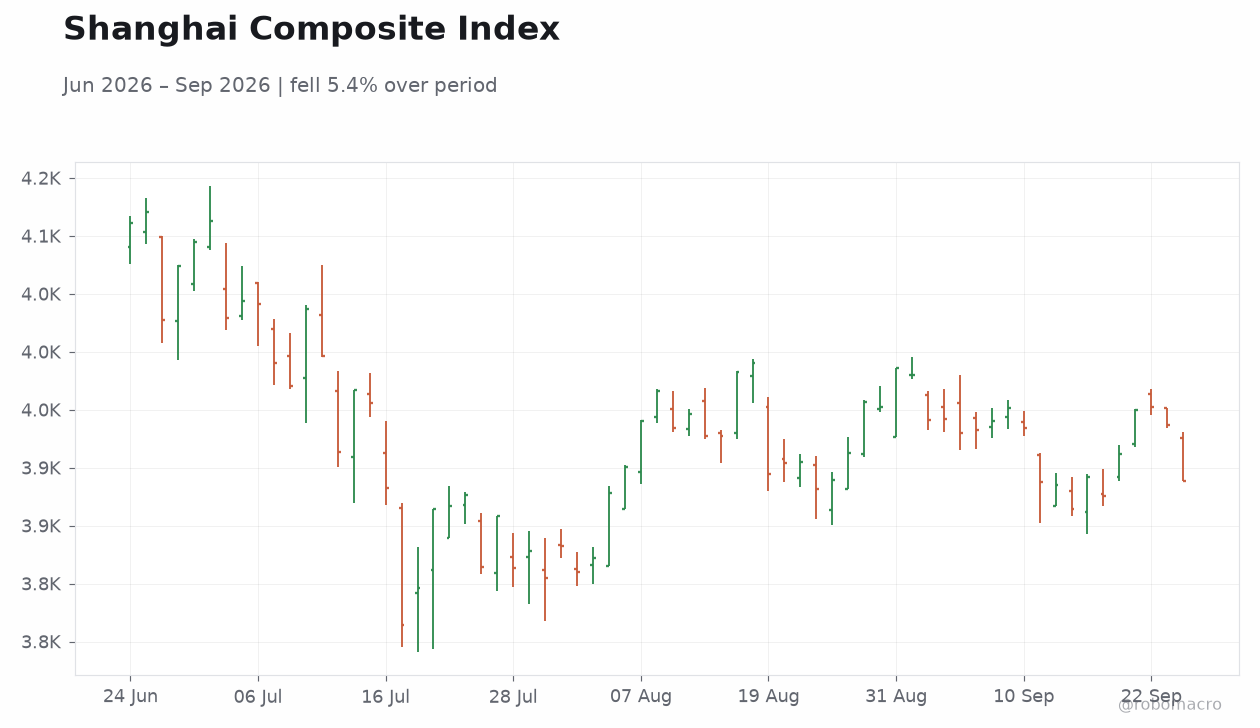
Shanghai Composite Index Shanghai Composite Index | Type: market_hloc | Index: 3888 (2026-09-24) | Range: 3764–4120 | Trend(6pt): 4111,3882,3940,3986,3952,3888
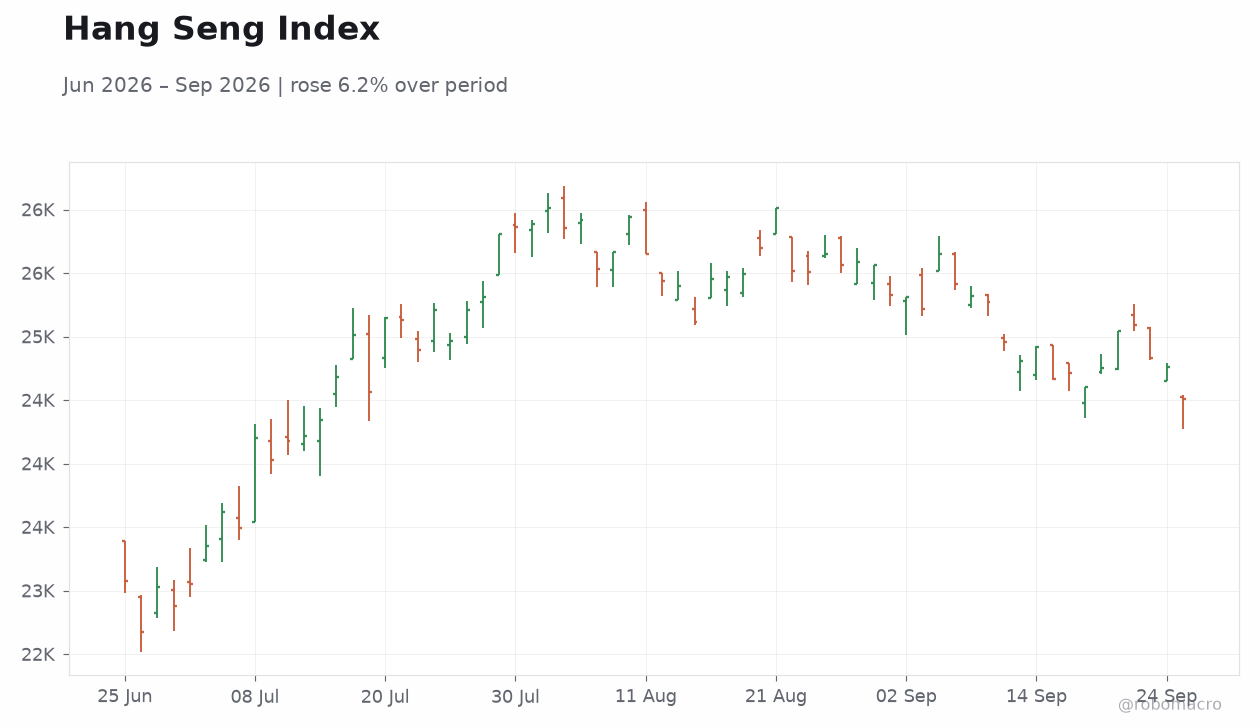
Hang Seng Index Hang Seng Index | Type: market_hloc | Index: 2.451e+04 (2026-09-25) | Range: 2.267e+04–2.601e+04 | Trend(6pt): 2.308e+04,2.514e+04,2.565e+04,2.531e+04,2.476e+04,2.451e+04

Other Economic Notes (continued)

Broader US-China commercial ties show incremental progress via the $30 billion tariff carve-out, yet underlying tensions over technology and AI governance persist. No fresh property-sector stimulus or regulatory easing appeared for mainland developers. Cross-strait investment flows remain steady without new policy shocks from either Beijing or Taipei.

HKMA warnings on fake stablecoin tokens underscore regulatory focus during rollout preparations.

Global Macro News

US consumer sentiment fell to a four-month low in September on rising price concerns, adding downside risks to global demand that could spill into Chinese export sectors. Soaring US bond yields show little sign of cooling the world’s largest economy, keeping pressure on emerging-market currencies including the yuan. The Fed’s ongoing rate path continues to anchor HKMA policy through the currency peg, limiting Hong Kong’s monetary autonomy.

Yen strength to 157 against the dollar after US-Japan finance-chief talks on “strong yen” concerns may indirectly support regional carry-trade flows. Canadian growth forecasts were trimmed on tariff and yield headwinds, mirroring potential China trade sensitivities. Tokenised-deposit experiments in Singapore and Thailand highlight divergent regulatory approaches compared with Hong Kong’s stablecoin rollout.

Overall, external demand signals remain mixed and could influence PBoC liquidity decisions in coming weeks.

Sponsored by Arbitrage Search
Page 2

Greater China Macro Daily(Beta Mode)

September 27, 2026 robomacro.com

Continuation

Greater China Central Banks Watch

The PBoC conducted no MLF or open-market operations on September 26, leaving liquidity conditions unchanged ahead of any State Council policy signals. Focus remains on potential RRR adjustments should export data weaken further, though no immediate easing signals have surfaced. HKMA maintained the USD/HKD peg at 7.84 with aggregate balance levels stable, underscoring the mechanical transmission of US rates into Hong Kong financial conditions.

The authority also issued warnings on fake HSBC and HKDAP tokens linked to stablecoin preparations, reinforcing regulatory vigilance. CBC held no rate decision and reported no FX intervention, with semiconductor export outlooks still tied to global chip demand rather than domestic policy shifts. Across the three central banks, policy divergence persists: PBoC retains easing flexibility, HKMA stays fully constrained by the peg, and CBC monitors external trade linkages without immediate action.

Markets will next watch for any joint PBoC-State Council liquidity guidance that could alter funding conditions in mainland money markets.

Sponsored by Arbitrage Search
Page 3