Greater China Macro Daily(Beta Mode)
Equities Slip Ahead of China PMI Releases
Market Snapshot
| Asset | Level | Change |
|---|---|---|
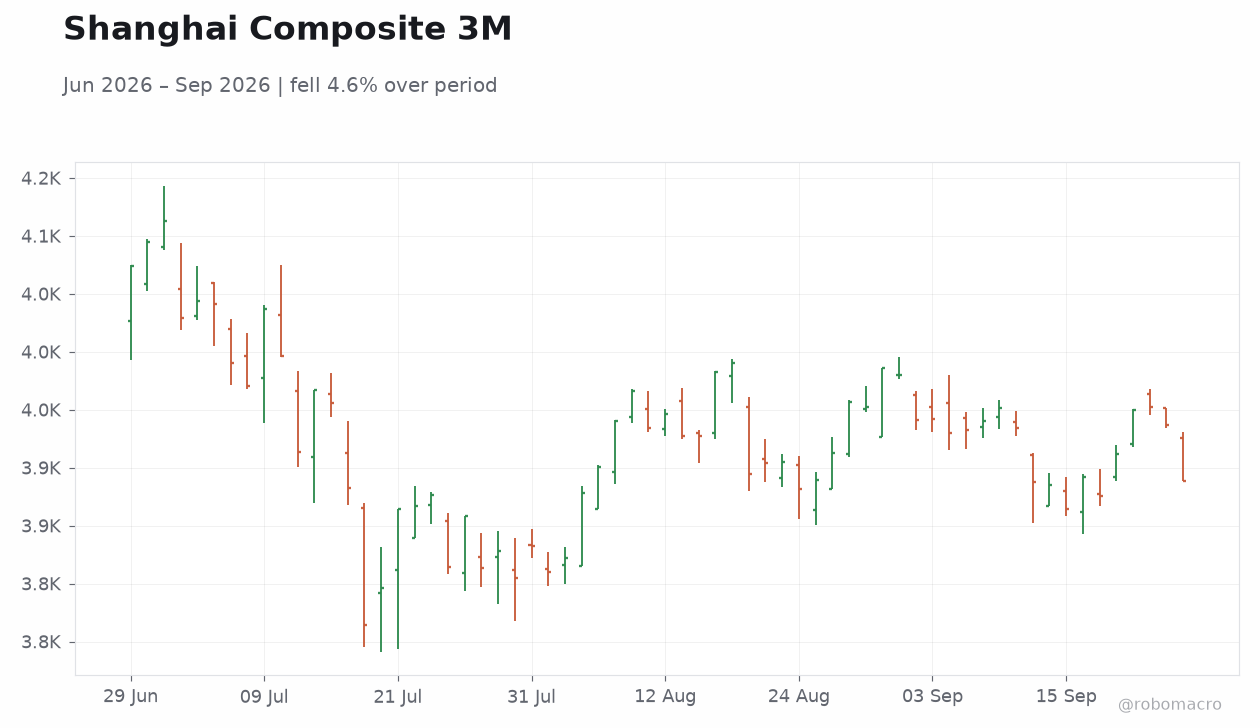
| Shanghai Composite | 3,888.37 | -1.22% |
| CSI 300 | 4,439.14 | -1.73% |
| Hang Seng | 24,510.09 | -1.01% |
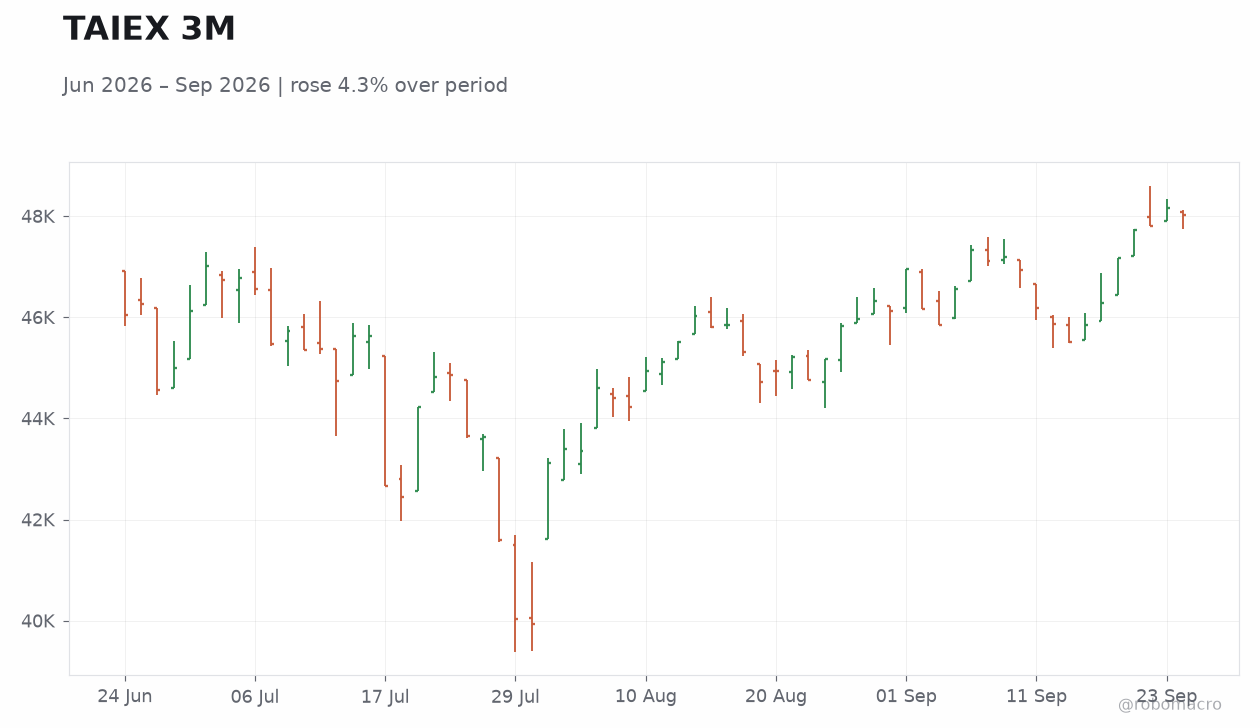
| TAIEX | 48,024.60 | -0.28% |
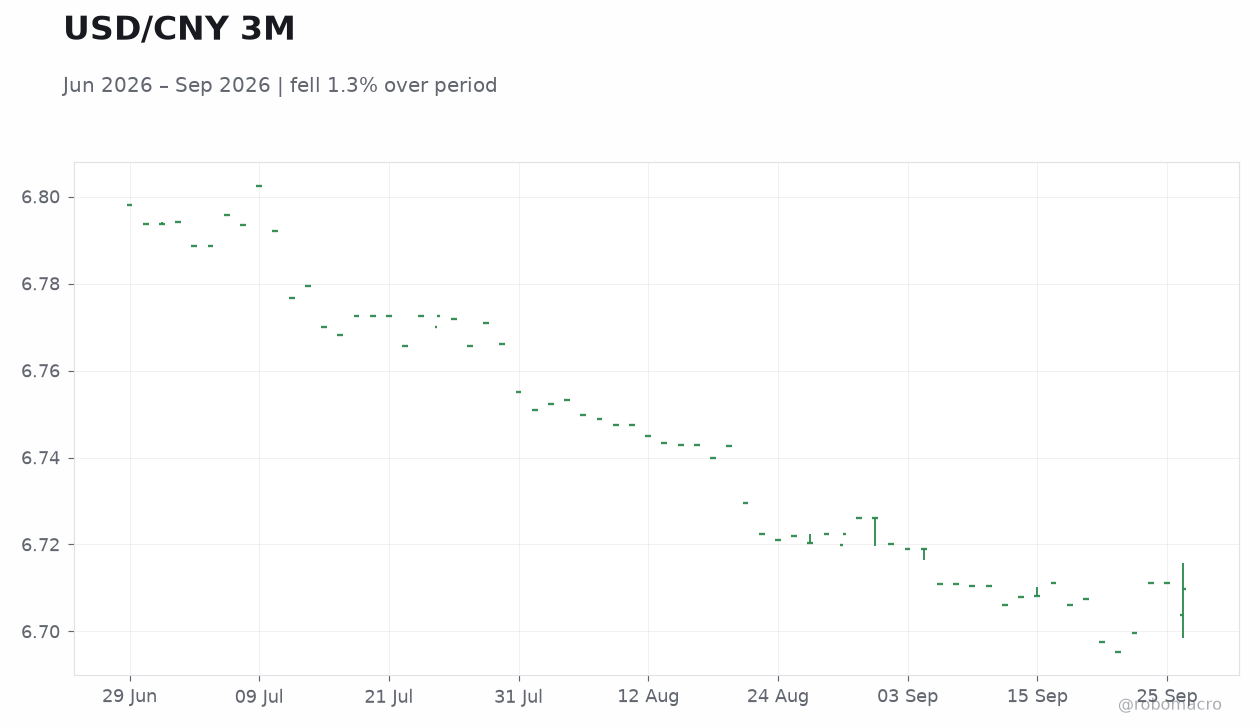
| USD/CNY | 6.71 | -0.02% |
| USD/HKD | 7.84 | +0.03% |
| Copper | 6.61 | -1.31% |
| Brent Crude | 98.56 | -5.52% |
| Gold | 4,148.50 | -4.00% |
| Bitcoin | 83,124.71 | -1.58% |
| China 2Y Govt Yield | - | - |
| China 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
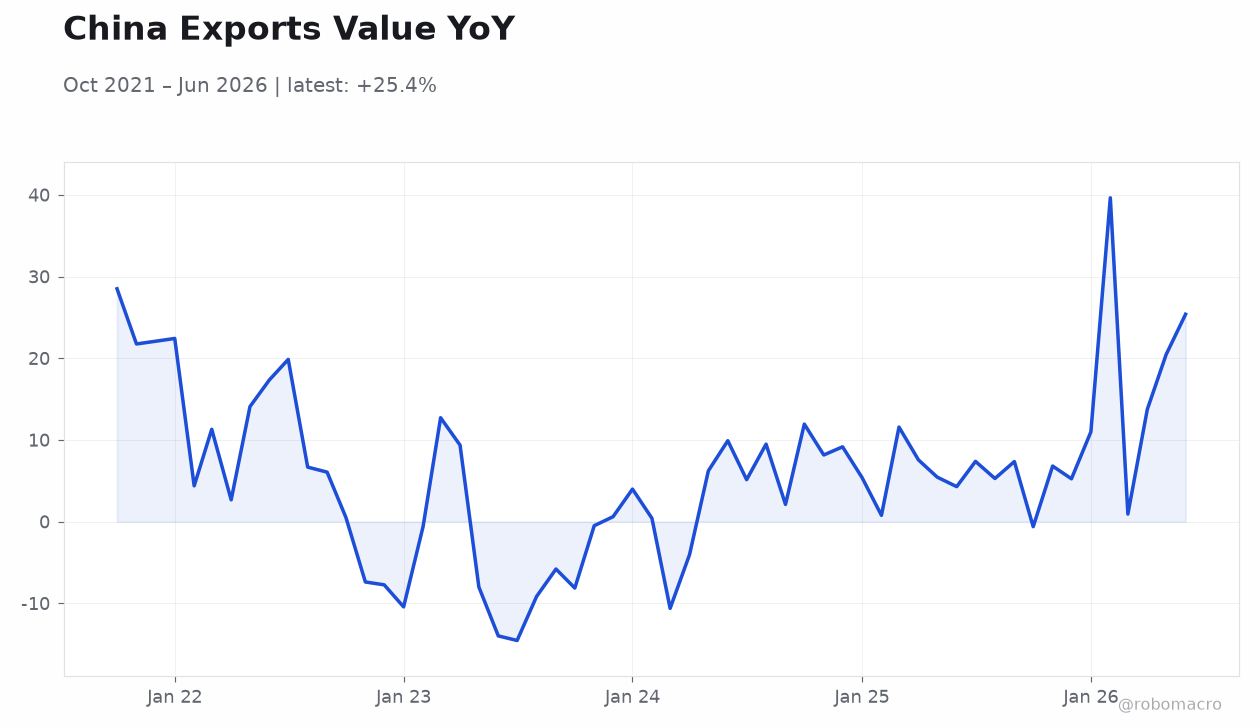
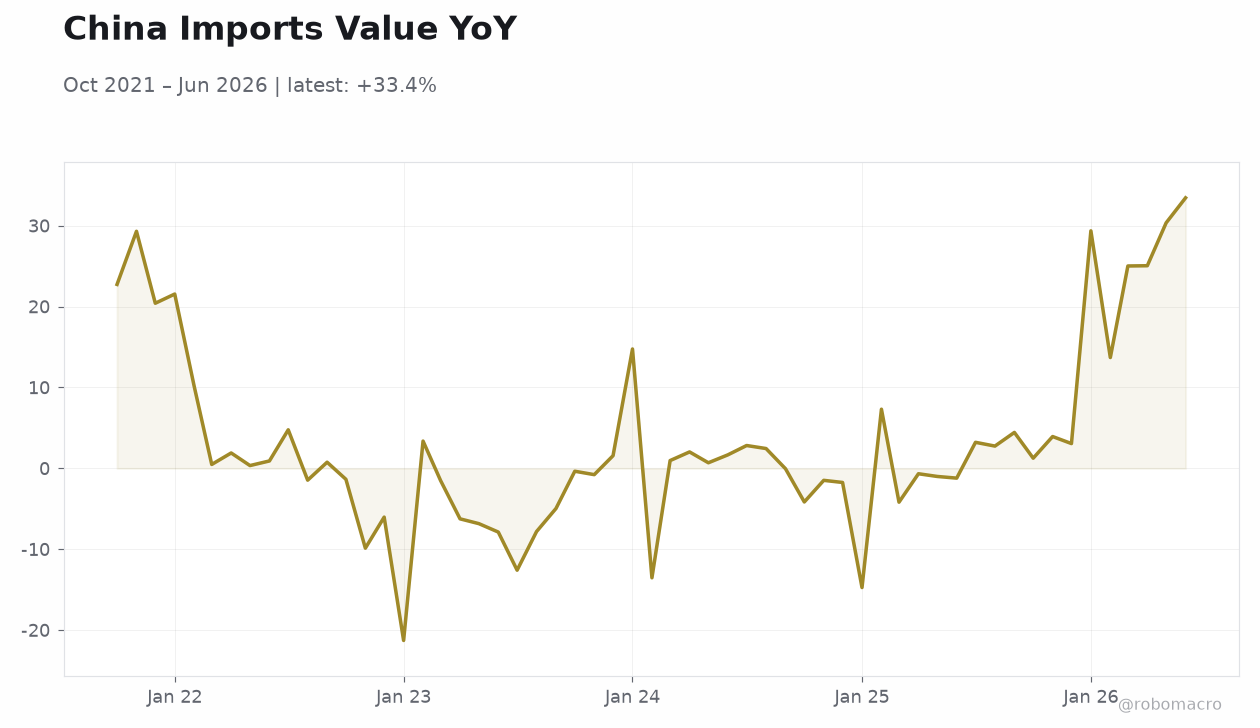 China Imports Value YoY | Type: macro_line | YoY %: 33.45 (2026-06-01) | Range: -21.28–33.45 | Trend(5pt): 22.74,-6.027,-13.53,-0.665,33.45
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| NBS Manufacturing PMI | 49.80 | 50.10 | 17:30 |
| NBS Non-Manufacturing PMI | 49 | 49.30 | 17:30 |
| RatingDog Manufacturing PMI | 51.50 | 51.60 | 17:45 |
| RatingDog Services PMI | 51.40 | 51.10 | 17:45 |
- Mainland equities fell over 1% as investors positioned ahead of key PMI prints.
- US and China finalized $30 billion tariff cuts on non-sensitive goods after Trump-Xi summit.
- NBS and RatingDog manufacturing PMIs due tomorrow with consensus pointing to modest rebounds.
Yesterday's Recap
Mainland China equity indices posted sharp losses on September 27 with the Shanghai Composite closing at 3,888.37, down 1.22 percent, while the CSI 300 dropped 1.73 percent to 4,439.14. Hong Kong’s Hang Seng Index declined 1.01 percent to 24,510.09 and Taiwan’s TAIEX eased 0.28 percent to 48,024.60. No macroeconomic data releases occurred across mainland China, Hong Kong or Taiwan.
USD/CNY finished at 6.71 after a 0.02 percent dip and USD/HKD rose 0.03 percent to 7.84. Commodity proxies for Chinese demand weakened, with copper falling 1.31 percent to 6.61 and Brent crude plunging 5.52 percent to 98.56. News flow centered on the release of product lists covering $30 billion in reciprocal US-China tariff reductions on non-sensitive goods, alongside separate tariff cuts on US corn, wheat, meat and dairy imports.
The agreements followed the Trump-Xi summit and coincided with the establishment of a bilateral artificial-intelligence dialogue channel.
The Day Ahead
Four PMI releases scheduled for September 29 will dominate Greater China calendars. The NBS Manufacturing PMI is expected to rise to 50.1 from 49.8, while the Non-Manufacturing PMI is forecast at 49.3 versus 49.0 previously. RatingDog Manufacturing PMI consensus stands at 51.6 against 51.5 last month and the Services PMI is projected at 51.1 after 51.4.
Markets will scrutinize the diffusion between official and private gauges for signs of stabilization in mainland manufacturing and services activity. No PBoC open-market operations, HKMA interventions or CBC policy meetings appear on the calendar. Traders will also monitor any follow-up statements from Beijing on the newly agreed tariff reductions.
Other Economic Notes
Real wage growth in Hong Kong slowed to a post-pandemic low of 1.1 percent year-to-date after inflation adjustment, highlighting subdued consumer purchasing power. The $30 billion tariff package excludes strategic sectors yet signals incremental de-escalation in bilateral trade frictions that could support select export-oriented supply chains. Copper’s 1.31 percent decline underscores persistent caution around mainland industrial demand despite the trade thaw.
↓ p.2