Greater China Macro Daily(Beta Mode)
China Policy Push Meets PMI Test
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| Shanghai Composite | 3,830.45 | +0.18% |
| CSI 300 | 4,345.21 | -2.12% |
| Hang Seng | 24,642.51 | +0.54% |
| TAIEX | 48,024.60 | -0.28% |
| USD/CNY | 6.70 | -0.15% |
| USD/HKD | 7.85 | +0.02% |
| Copper | 6.66 | +1.41% |
| Brent Crude | 95.67 | -9.13% |
| Gold | 4,215.00 | +1.12% |
| Bitcoin | 83,521.69 | +0.02% |
| China 2Y Govt Yield | - | - |
| China 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
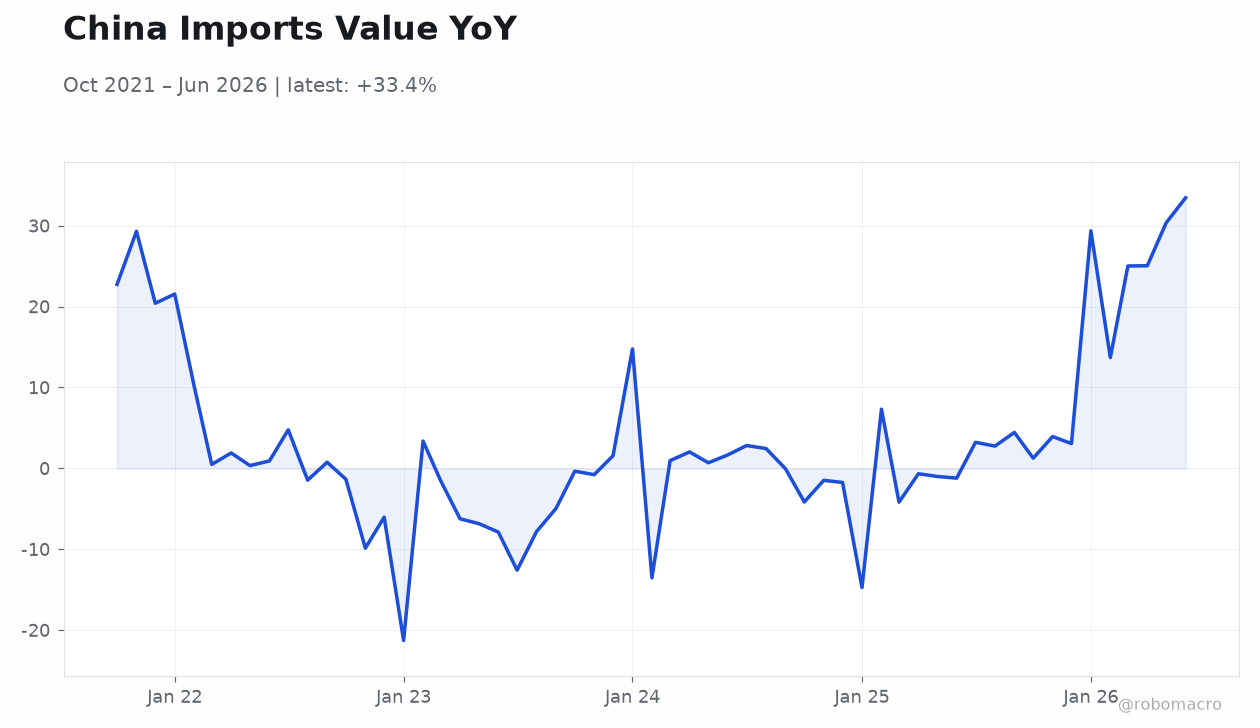
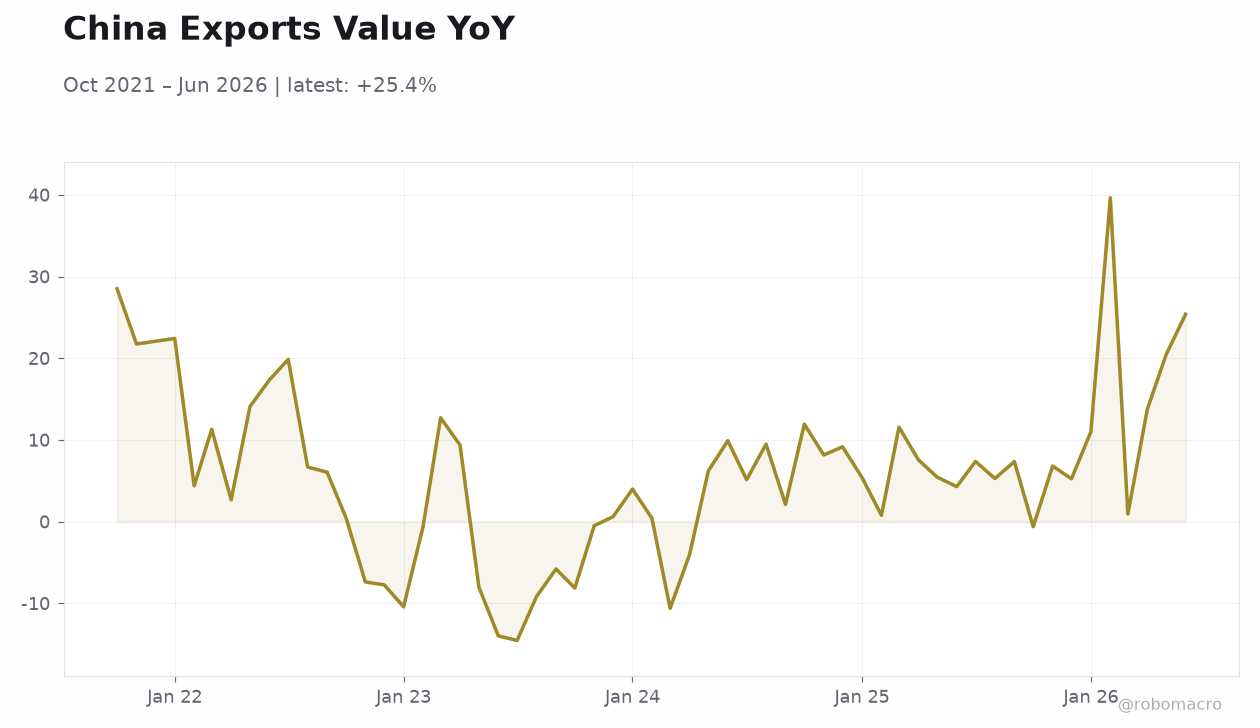 China Exports Value YoY | Type: macro_line | YoY %: 25.39 (2026-06-01) | Range: -14.55–39.64 | Trend(5pt): 28.5,-7.732,0.4113,7.56,25.39
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| NBS Manufacturing PMI | 49.80 | 50.10 | 17:30 |
| NBS Non-Manufacturing PMI | 49 | 49.30 | 17:30 |
| RatingDog Manufacturing PMI | 51.50 | 51.60 | 17:45 |
| RatingDog Services PMI | 51.40 | 51.10 | 17:45 |
- China to introduce new pro-growth measures and study property market stabilization policies.
- US-China agree on mutual $30B tariff cuts excluding soybeans and strategic sectors.
- NBS and RatingDog PMI releases due today with modest consensus improvements expected.
Yesterday's Recap
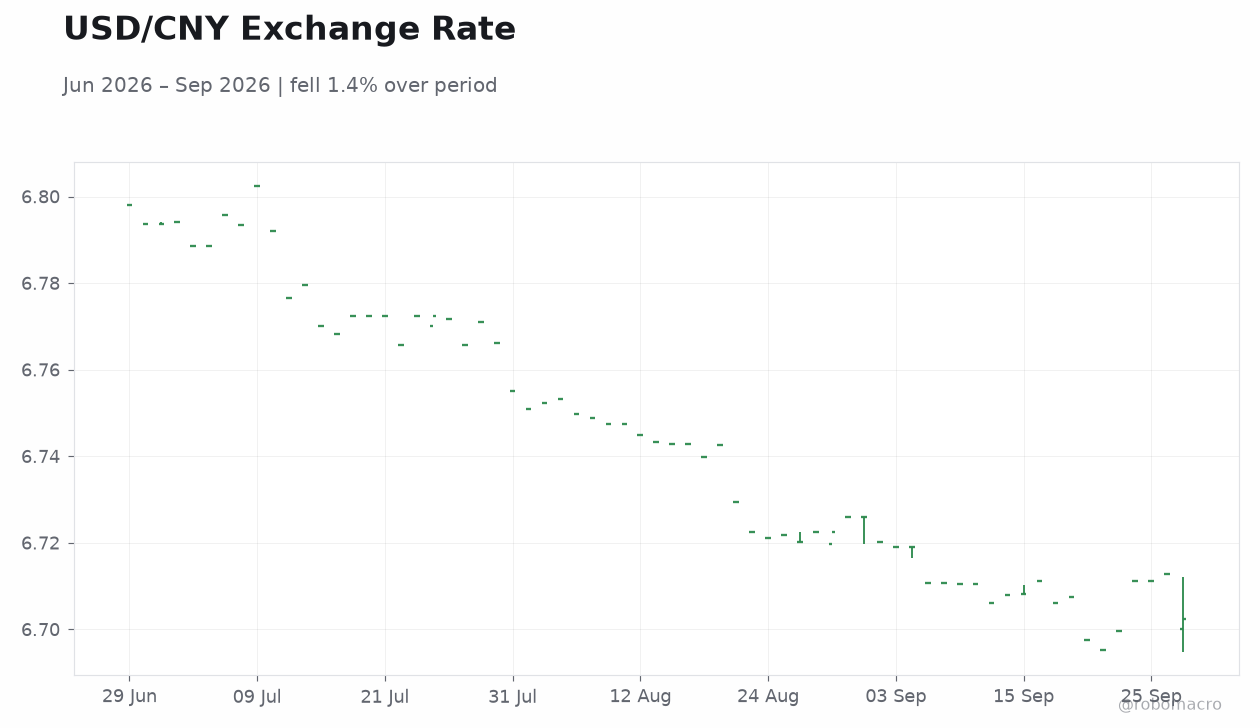
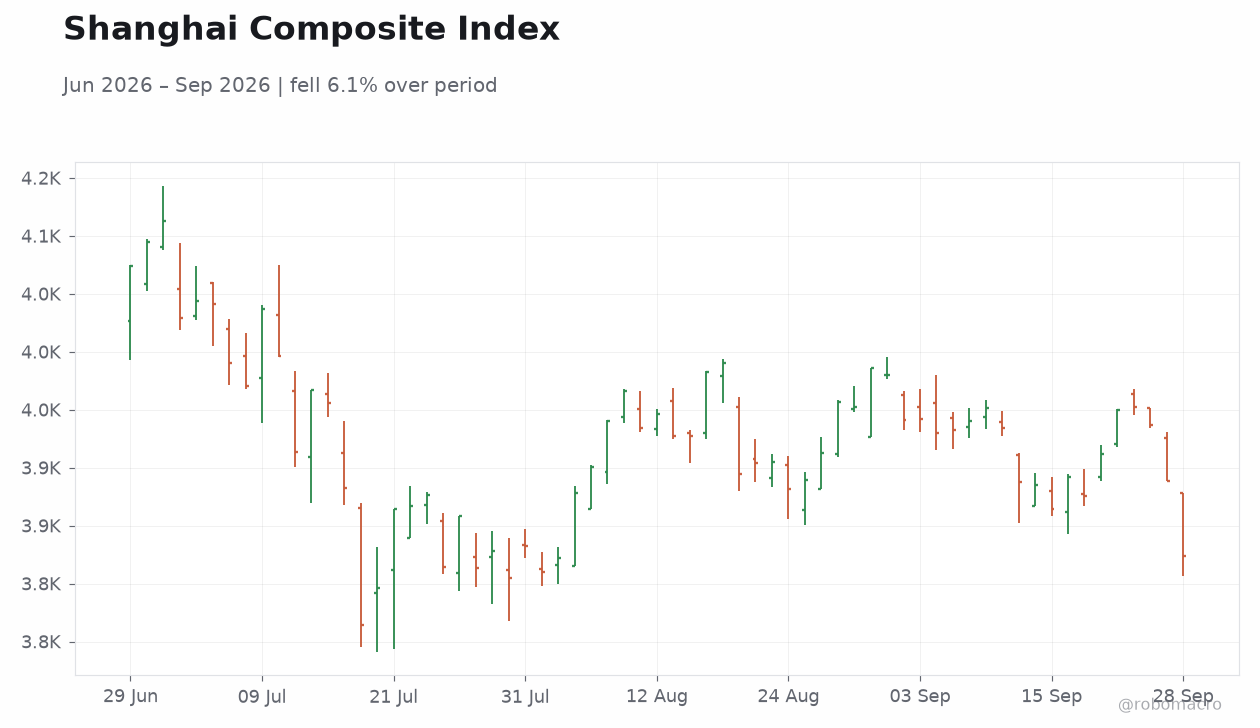
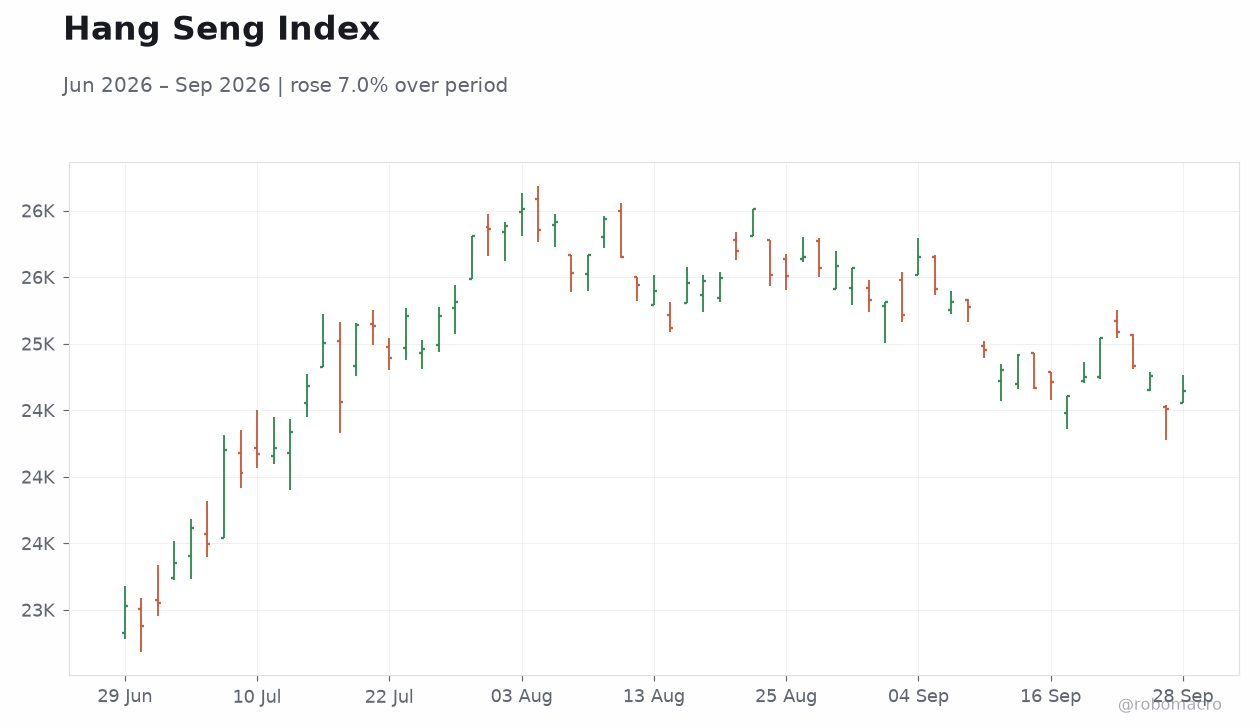
Mainland equities diverged sharply as the Shanghai Composite edged up 0.18% to 3,830.45 while the CSI 300 dropped 2.12% to 4,345.21. Hong Kong’s Hang Seng rose 0.54% to 24,642.51 on early policy optimism while Taiwan’s TAIEX slipped 0.28% to 48,024.60. The USD/CNY rate eased 0.15% to 6.70, reflecting modest yuan support, and USD/HKD held steady at 7.85.
Copper climbed 1.41% as a China demand proxy while Brent Crude plunged 9.13% and gold gained 1.12%. China’s government signaled fresh pro-growth policies focused on investment and property stabilization studies, alongside a US-China deal to cut tariffs on $30 billion of each other’s goods excluding soybeans. No data releases occurred on 28 September.
The Day Ahead
Four China PMI prints are scheduled for late afternoon ET, including NBS Manufacturing PMI at a 50.1 consensus versus 49.8 prior and Non-Manufacturing PMI at 49.3 versus 49.0. RatingDog Manufacturing PMI is expected at 51.6 from 51.5 while Services PMI consensus sits at 51.1 from 51.4. Markets will scrutinize whether the readings confirm stabilization after recent policy signals.
No PBoC liquidity operations, HKMA interventions, or CBC meetings are listed. Focus remains on whether the prints align with the government’s pro-growth stance.
Other Economic Notes
China’s August CPI printed 0.80% YoY, indicating subdued price pressures that leave room for further policy easing. The announced tariff reductions with the US should support agricultural imports but leave China’s trade surplus largely intact by excluding strategic sectors. Property market support measures are expected to emphasize investment channels rather than broad consumption stimulus.
LNG imports are projected to decline for a second consecutive month on elevated prices linked to Middle East tensions. These developments reinforce Beijing’s preference for targeted supply-side measures over broad demand boosts.
Global Macro News
Fed Governor Barr described the US economy as “strikingly” resilient and defended the prior rate hike, supporting a cautious global policy backdrop that affects capital flows into Greater China assets. ↓ p.2