Greater China Macro Daily(Beta Mode)
China PMIs Beat as Beijing Unveils Mortgage Aid
Market Snapshot
| Asset | Level | Change |
|---|---|---|
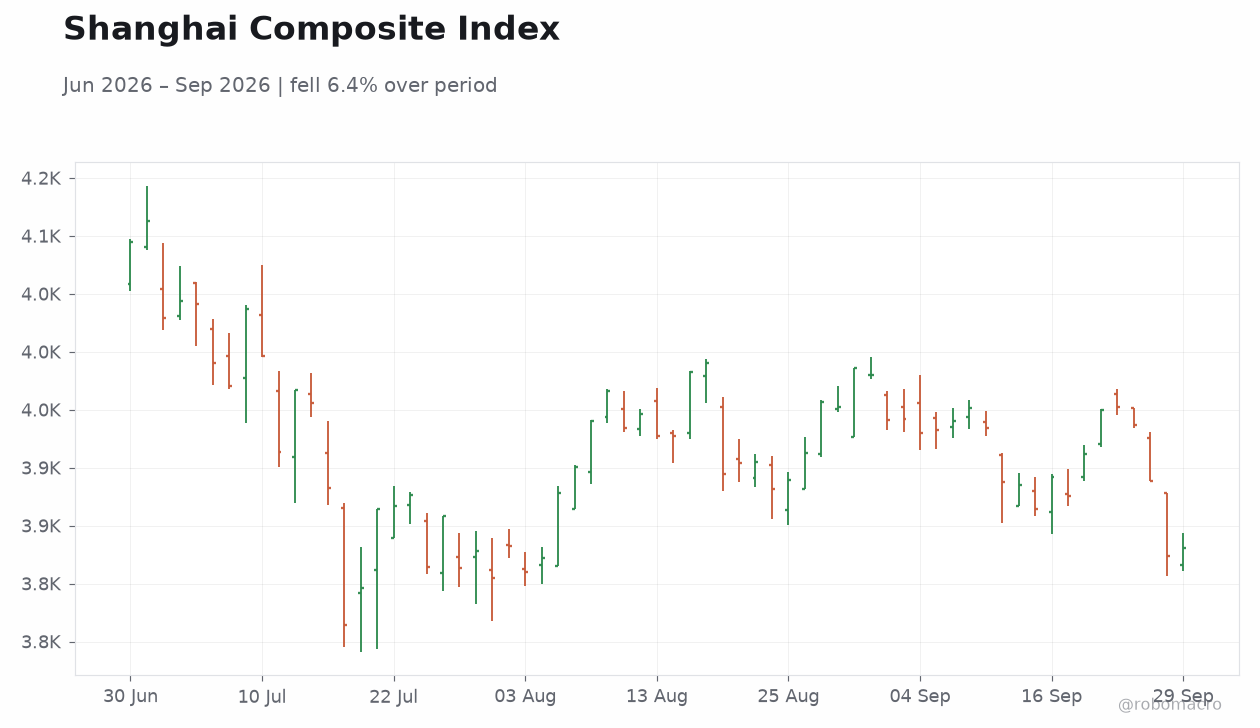
| Shanghai Composite | 3,842.19 | +0.31% |
| CSI 300 | 4,357.62 | +0.29% |
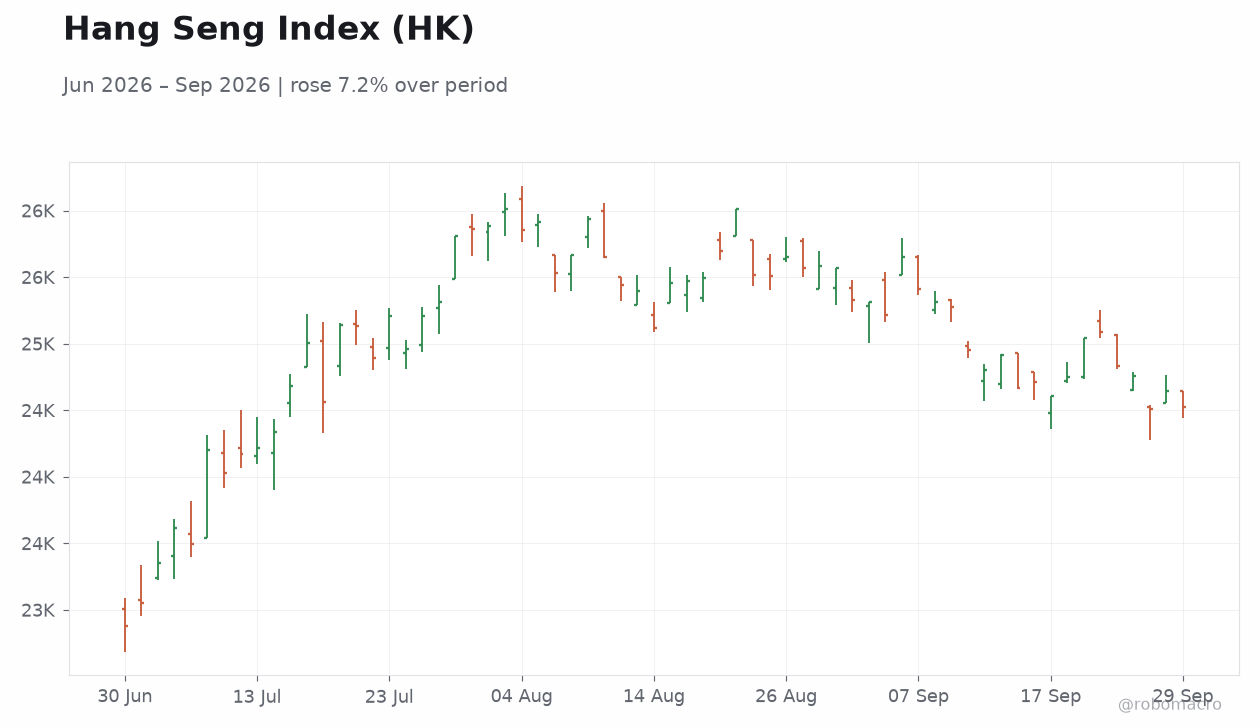
| Hang Seng | 24,523.57 | -0.48% |
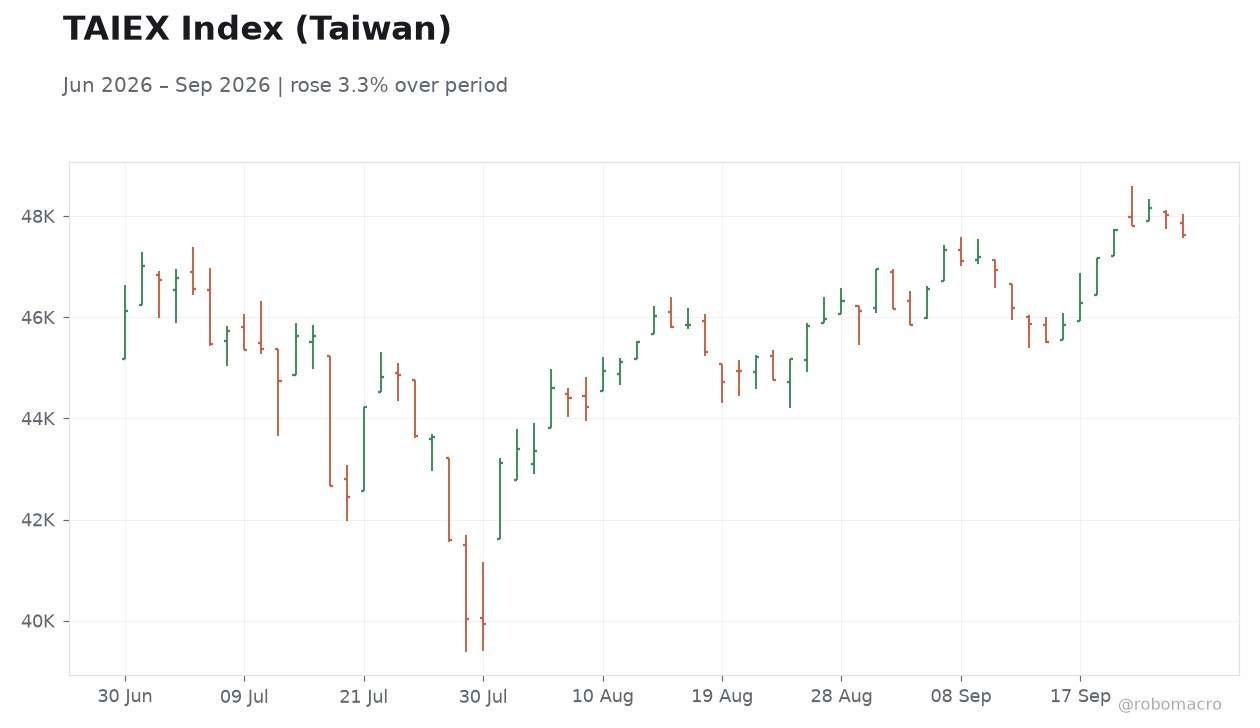
| TAIEX | 47,631.96 | -0.82% |
| USD/CNY | 6.70 | -0.17% |
| USD/HKD | 7.85 | +0.01% |
| Copper | 6.64 | +1.47% |
| Brent Crude | 97.92 | -4.55% |
| Gold | 4,189.10 | +0.22% |
| Bitcoin | 83,718.38 | +0.11% |
| China 2Y Govt Yield | - | - |
| China 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| NBS Manufacturing PMI | 49.80 | 50.10 | 50.10 |
| NBS Non-Manufacturing PMI | 49 | 49.30 | 50.20 |
| RatingDog Manufacturing PMI | 51.50 | 51.60 | 52.10 |
| RatingDog Services PMI | 51.40 | 51.10 | 51.60 |
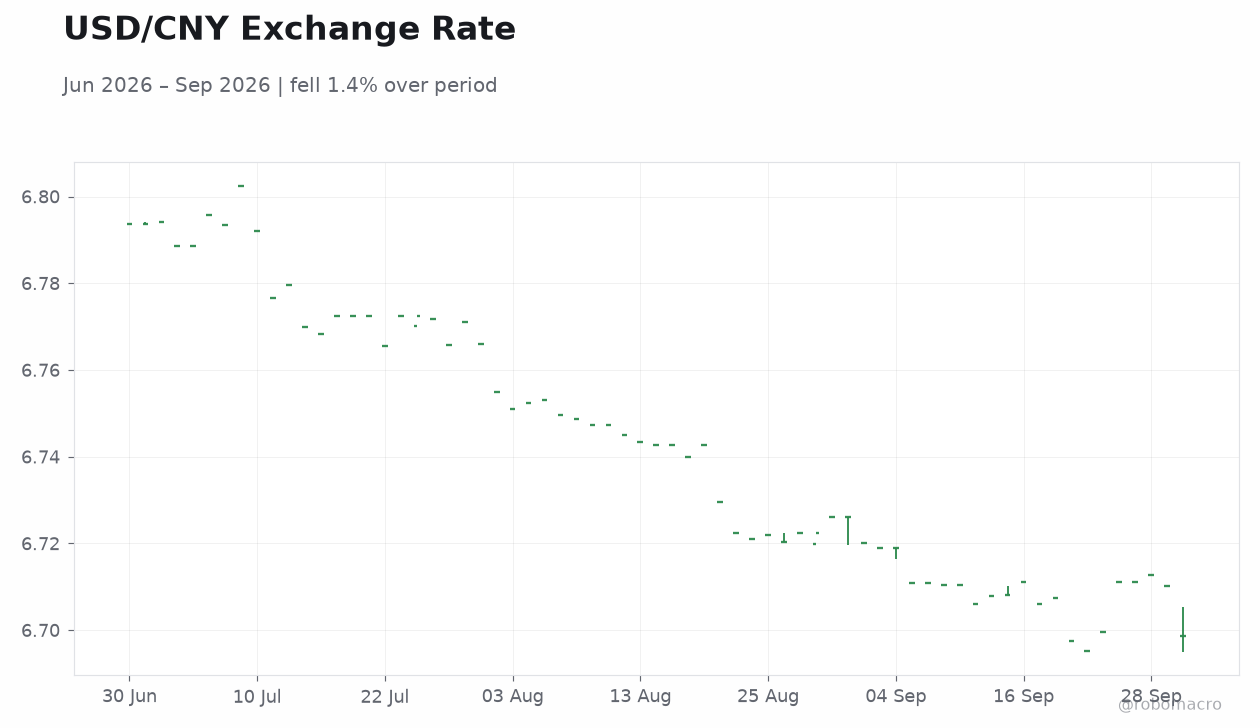 USD/CNY Exchange Rate | Type: market_hloc | Rate: 6.699 (2026-09-30) | Range: 6.695–6.802 | Trend(6pt): 6.794,6.766,6.743,6.719,6.713,6.699
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- NBS and RatingDog PMIs beat expectations, with manufacturing at 50.1 and 52.1 respectively, signaling improving momentum.
- Beijing announced mortgage subsidies for first-time buyers and a policy rate cut to support growth and the property sector.
- Shanghai Composite rose 0.31% while Hang Seng fell 0.48% and TAIEX dropped 0.82%; USD/CNY eased to 6.70.
Yesterday's Recap
China’s September PMI readings surprised to the upside across both official and private gauges. NBS Manufacturing PMI printed at 50.1, matching consensus and rising from 49.8, while Non-Manufacturing PMI jumped to 50.2 versus 49.3 expected. RatingDog Manufacturing PMI reached 52.1 against 51.6 consensus and Services PMI hit 51.6 versus 51.1.
Mainland equities advanced modestly with the Shanghai Composite gaining 0.31% to 3,842.19 and CSI 300 adding 0.29% to 4,357.62. Hong Kong and Taiwan indices declined, with Hang Seng falling 0.48% to 24,523.57 and TAIEX dropping 0.82% to 47,631.96. USD/CNY eased 0.17% to 6.70 amid the PBoC’s expected reference rate near 6.7025.
Beijing unveiled mortgage subsidies for first-time buyers plus a policy interest-rate cut, while the PBoC offered cheap loans to clear local-government arrears and pledged further measures to stabilize the property market. Copper rose 1.47% to 6.64 while Brent Crude fell 4.55% to 97.92, and gold edged 0.22% higher to 4,189.10.
The Day Ahead
No economic releases, PBoC liquidity operations, HKMA interventions, or CBC meetings are scheduled for 30 September or 1 October. Markets will remain focused on follow-through from yesterday’s policy announcements on mortgage support and local-government financing. Property-sector sentiment may continue to respond to the new subsidies and rate measures.
Copper prices, which rose 1.47% to 6.64, will serve as a near-term proxy for growth expectations. Brent Crude’s 4.55% drop to 97.92 could ease imported inflation pressures for mainland China. USD/HKD held steady at 7.85 with no immediate peg pressure evident.
Other Economic Notes
The broad PMI beat reduces near-term pressure on the PBoC to ease further while reinforcing the case for targeted fiscal and credit support. Hong Kong household debt climbed to 89.5% of GDP, though the HKMA judged the debt-servicing ratio as remaining healthy. Policy emphasis has shifted toward investment and property stabilization rather than broad consumption stimulus.
Local-government arrears clearance via PBoC cheap loans addresses a key drag on fiscal space. No material Taiwan-specific regulatory or cross-strait trade developments emerged. China’s LNG imports are set to decline for a second month amid elevated prices.