Greater China Macro Daily(Beta Mode)
China PMIs Beat, Equities Advance
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| Shanghai Composite | 3,842.20 | +0.31% |
| CSI 300 | 4,357.62 | +0.29% |
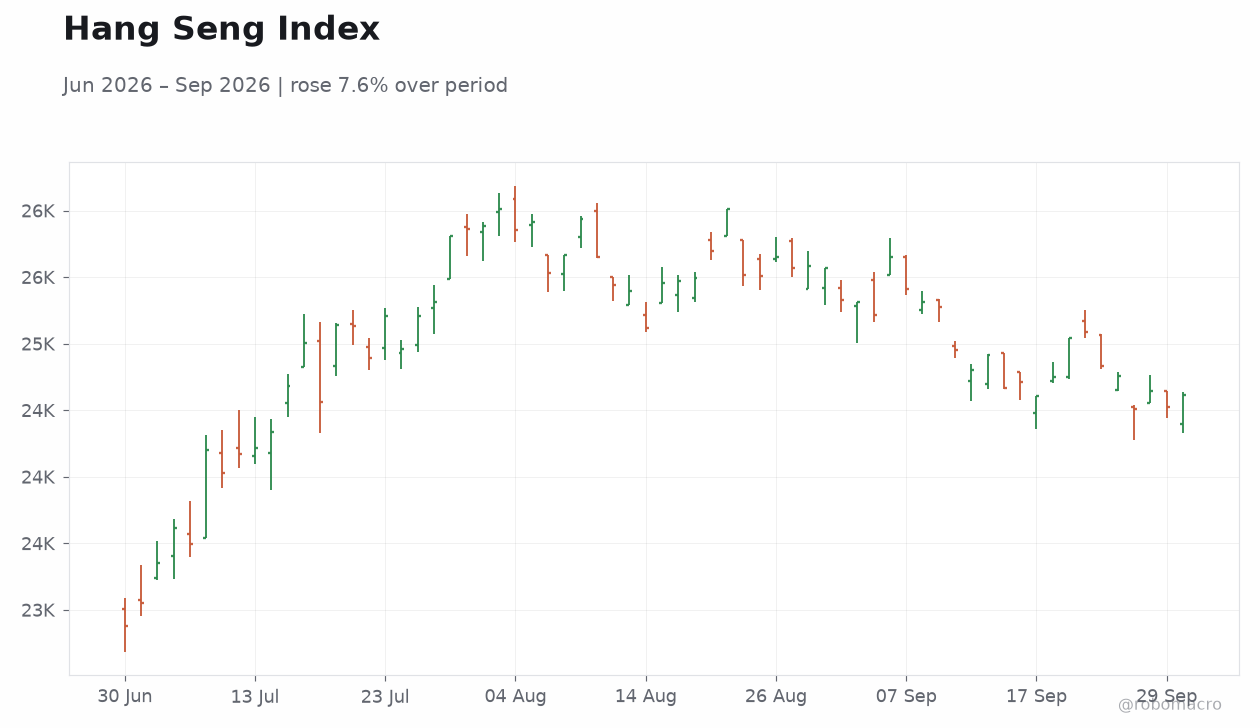
| Hang Seng | 24,613.27 | +0.37% |
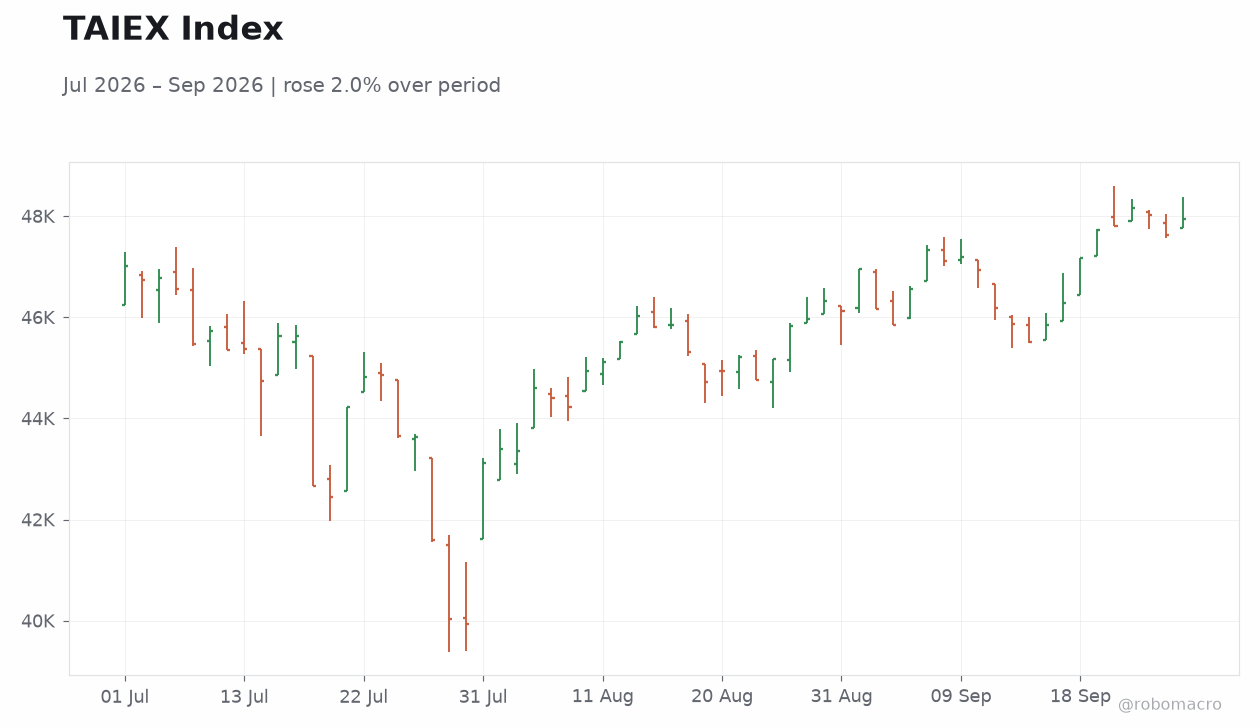
| TAIEX | 47,940.13 | +0.65% |
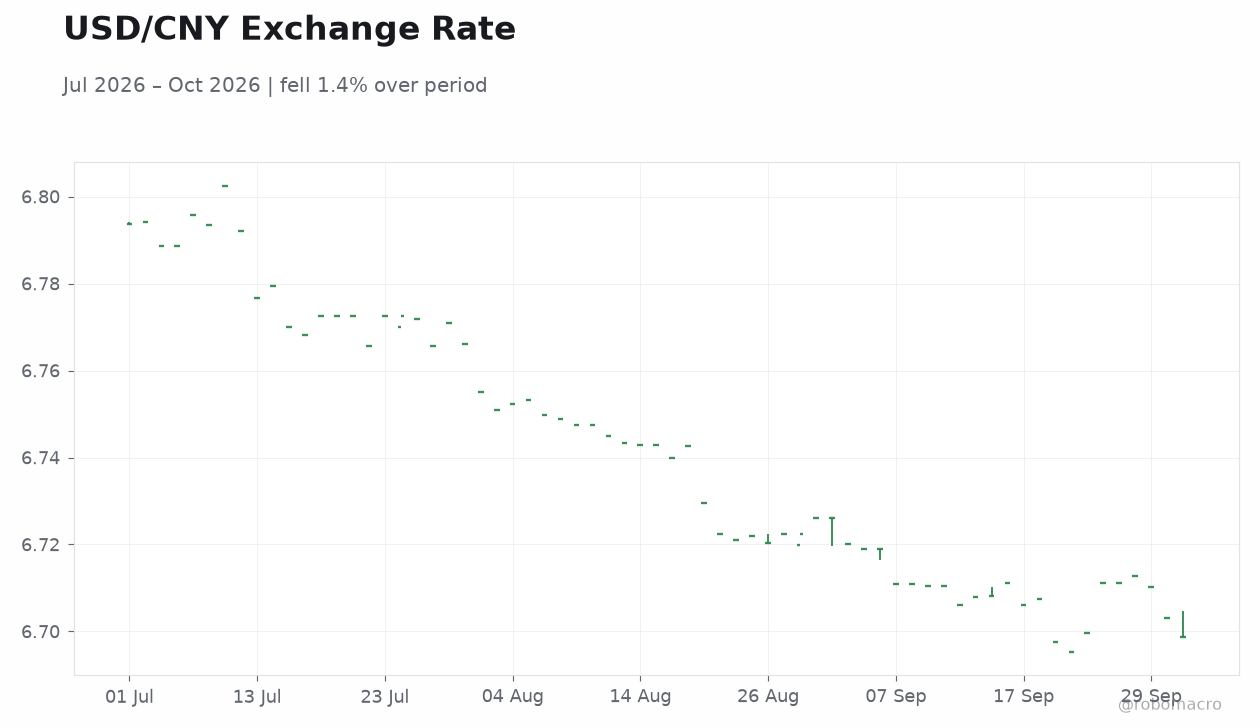
| USD/CNY | 6.70 | -0.06% |
| USD/HKD | 7.85 | -0.01% |
| Copper | 6.58 | +0.27% |
| Brent Crude | 102.21 | -1.27% |
| Gold | 4,207.80 | +0.50% |
| Bitcoin | 84,622.53 | +1.28% |
| China 2Y Govt Yield | - | - |
| China 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| NBS Manufacturing PMI | 49.80 | 50.10 | 50.10 |
| NBS Non-Manufacturing PMI | 49 | 49.30 | 50.20 |
| RatingDog Manufacturing PMI | 51.50 | 51.60 | 52.10 |
| RatingDog Services PMI | 51.40 | 51.10 | 51.60 |
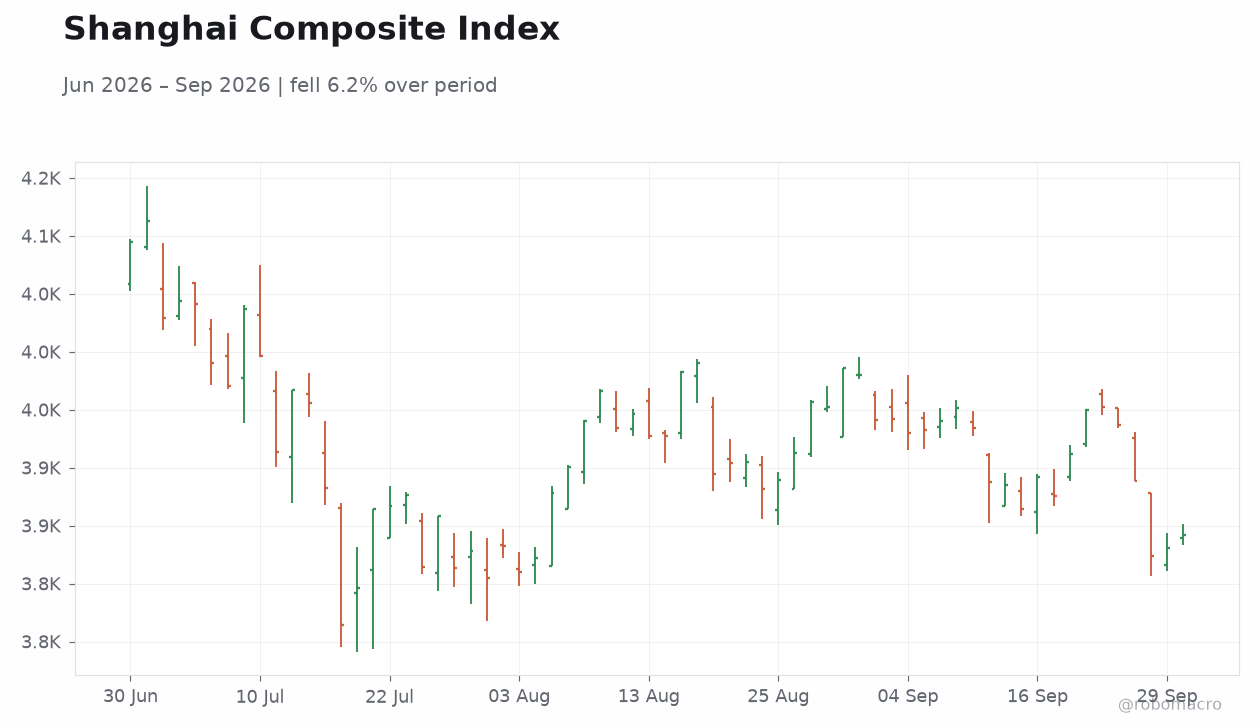 Shanghai Composite Index | Type: market_hloc | Index: 3842 (2026-09-30) | Range: 3764–4112 | Trend(6pt): 4094,3867,3927,3930,3830,3842
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- NBS and RatingDog PMIs rose above forecasts, signaling Q3 stabilization in mainland China activity.
- Shanghai Composite gained 0.31% and TAIEX rose 0.65% as USD/CNY eased 0.06% to 6.70.
- PBoC set to fix USD/CNY reference rate at 6.7025 amid canceled fuel exports to support domestic supply.
Yesterday's Recap
Mainland China data dominated. NBS Manufacturing PMI printed at 50.1, matching consensus and rising from 49.8, while NBS Non-Manufacturing PMI climbed to 50.2 against 49.3 expected. RatingDog Manufacturing PMI advanced to 52.1 from 51.5 and RatingDog Services PMI reached 51.6 versus 51.1 forecast.
Equities responded positively with Shanghai Composite closing at 3,842.20, up 0.31%, CSI 300 at 4,357.62, up 0.29%, Hang Seng at 24,613.27, up 0.37%, and TAIEX at 47,940.13, up 0.65%. USD/CNY fell 0.06% to 6.70 and USD/HKD slipped 0.01% to 7.85. Copper rose 0.27% to 6.58 while Brent crude dropped 1.27% to 102.21.
Gold gained 0.50% to 4,207.80 and Bitcoin added 1.28% to 84,622.53. Chinese fuel exporters canceled select October product cargoes to prioritize domestic supply. Bilateral China-Bangladesh trade hit a record $12.8 billion in H1 2026, up 10.6% year-on-year.
The Day Ahead
No high-impact releases or policy meetings are scheduled for October 1 or 2 across mainland China, Hong Kong or Taiwan. PBoC open-market operations will set daily liquidity conditions and the USD/CNY reference rate is expected at 6.7025. HKMA will monitor USD/HKD peg mechanics and aggregate balance flows.
CBC faces no immediate rate decision but will track semiconductor export data and cross-strait investment trends. Markets will focus on any State Council signals on property sector support and potential RRR adjustments. Traders await further PBoC liquidity injections ahead of the October holiday period.
Other Economic Notes
Mainland China activity shows modest stabilization after August CPI printed 0.80% year-on-year. Canceled fuel exports reflect Beijing’s priority on domestic energy security amid global volatility. Hong Kong household debt reached 89.5% of GDP with HKMA stating the debt-servicing ratio remains healthy.
Taiwan opposition proposed a TWD20,000 universal cash handout funded by tax surpluses, potentially supporting consumption. Semiconductor-driven tax surpluses in the region highlight concentrated gains that may spill over to broader activity. Property sector dynamics and cross-strait trade flows remain key watchpoints for Q4.