Greater China Macro Daily(Beta Mode)
China PMIs Beat as Fuel Export Curbs Resume
Market Snapshot
| Asset | Level | Change |
|---|---|---|
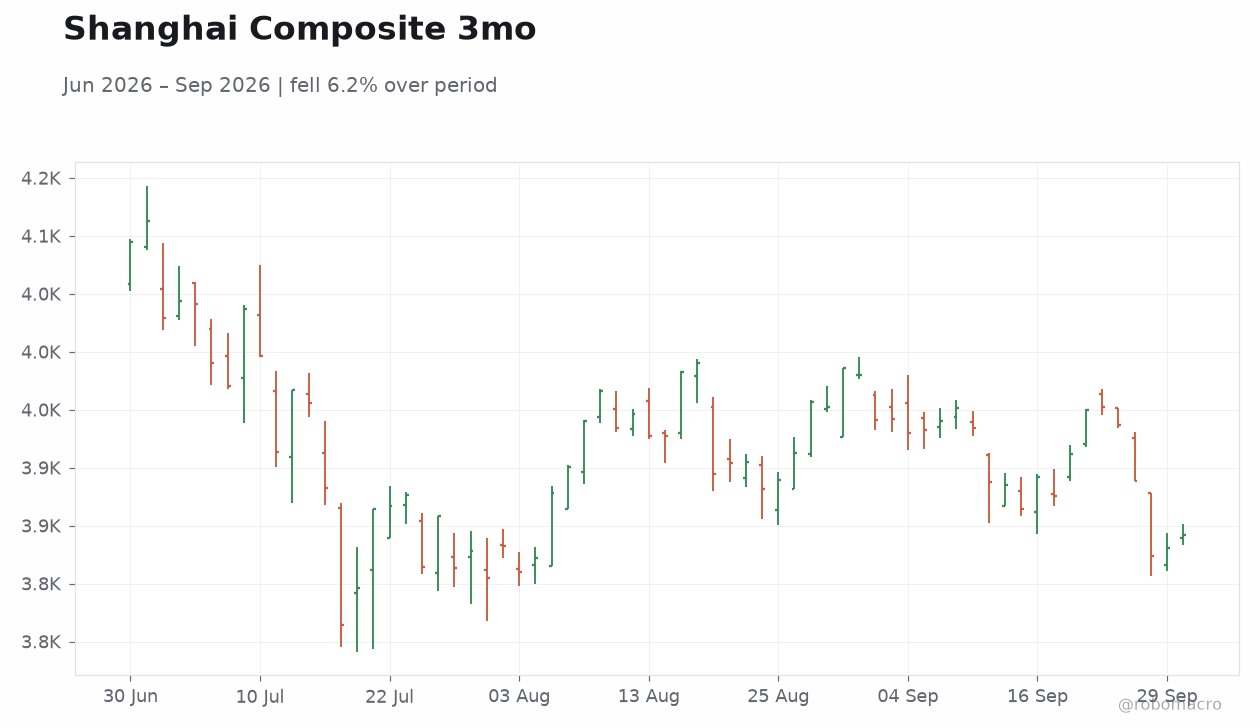
| Shanghai Composite | 3,842.19 | +0.31% |
| CSI 300 | 4,357.62 | +0.29% |
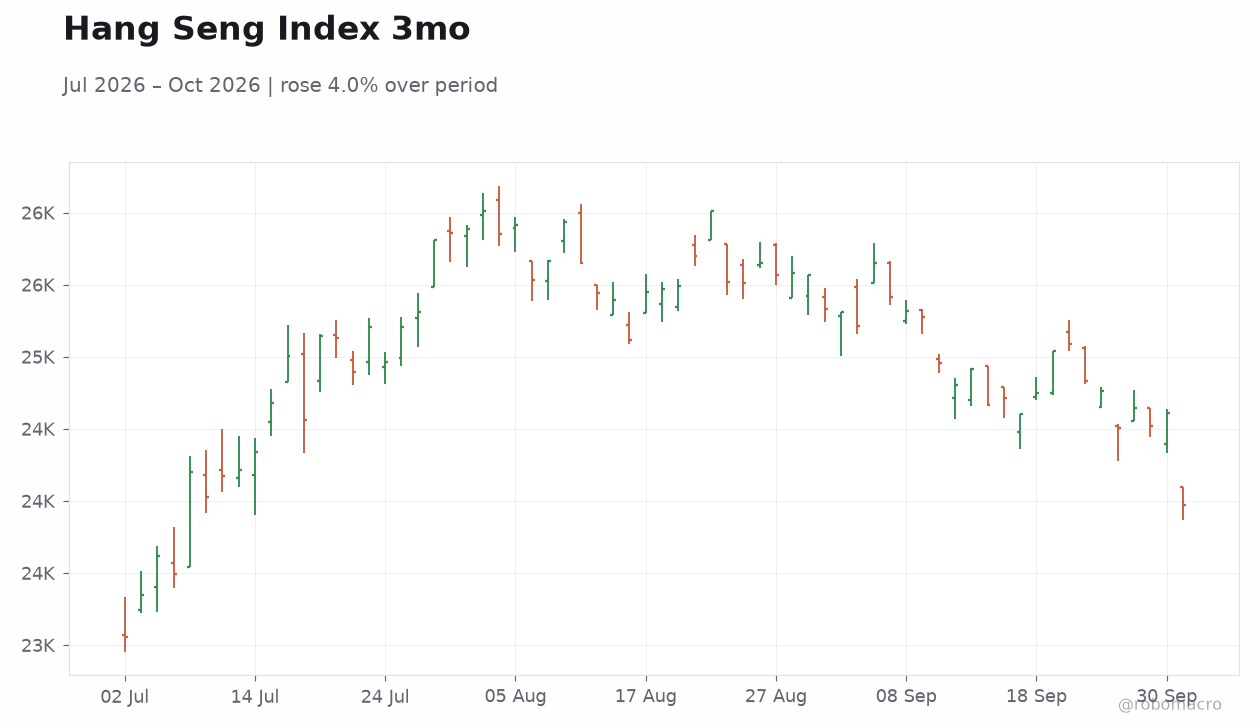
| Hang Seng | 23,972.29 | -2.60% |
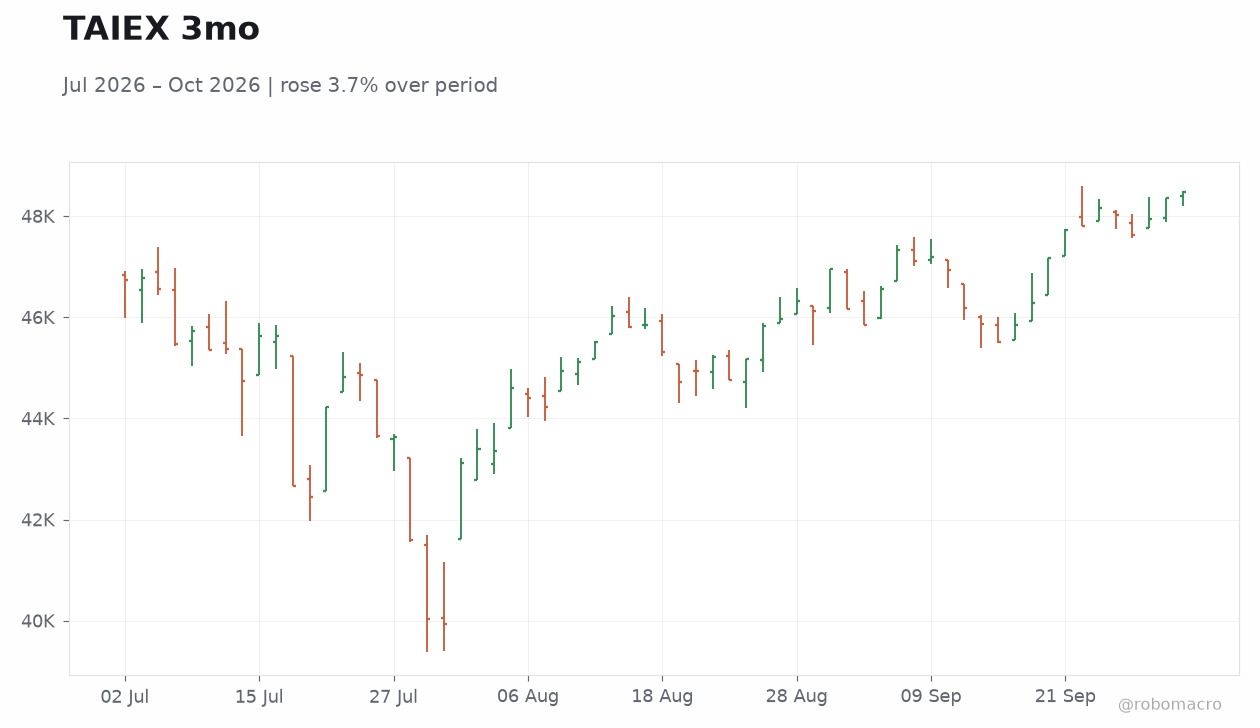
| TAIEX | 48,475.74 | +0.25% |
| USD/CNY | 6.70 | -0.09% |
| USD/HKD | 7.85 | -0.00% |
| Copper | 6.55 | +1.03% |
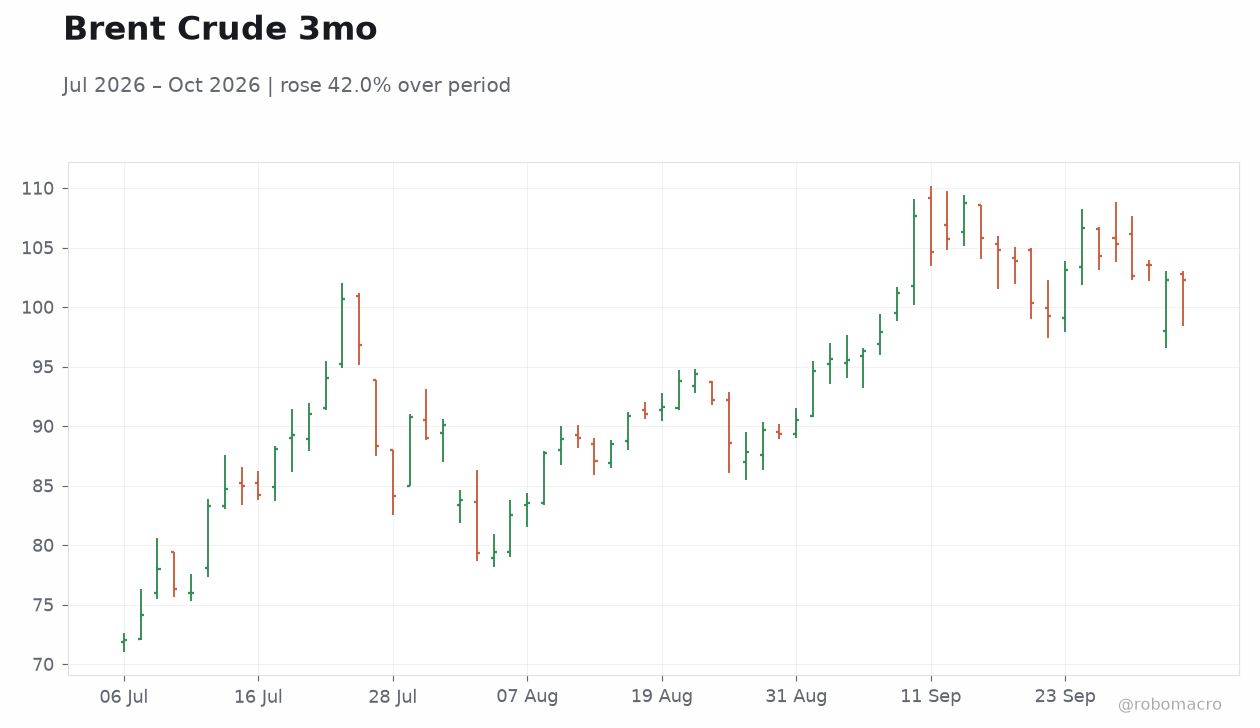
| Brent Crude | 102.25 | -0.06% |
| Gold | 4,162.30 | -0.95% |
| Bitcoin | 86,009.00 | +1.47% |
| China 2Y Govt Yield | - | - |
| China 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| NBS Manufacturing PMI | 49.80 | 50.10 | 50.10 |
| NBS Non-Manufacturing PMI | 49 | 49.30 | 50.20 |
| RatingDog Manufacturing PMI | 51.50 | 51.60 | 52.10 |
| RatingDog Services PMI | 51.40 | 51.10 | 51.60 |
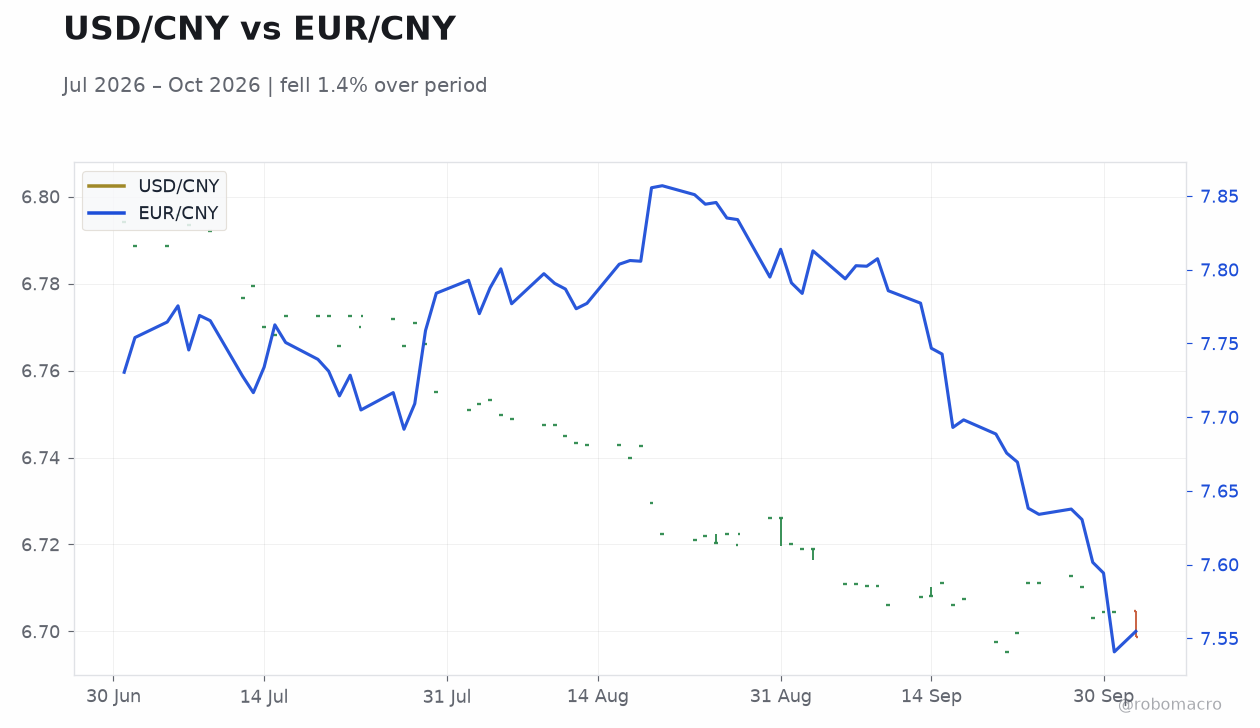 USD/CNY vs EUR/CNY | Type: market_hloc | USD/CNY: 6.699 (2026-10-04) | Range: 6.695–6.802 | Trend(5pt): 6.794,6.772,6.743,6.706,6.699 | EUR/CNY: 7.555 (2026-10-04) | Range: 7.541–7.857 | Trend(5pt): 7.73,7.717,7.806,7.786,7.555
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- China’s September NBS and RatingDog PMI readings exceeded expectations, confirming modest expansion in manufacturing and services.
- Mainland equities rose while Hong Kong shares fell sharply amid property-sector losses at New World Development.
- China resumed curbs on refined fuel exports as domestic inventories tightened, adding pressure to global energy markets.
Yesterday's Recap
China’s September NBS Manufacturing PMI printed at 50.1, matching consensus and rising from 49.8, while the Non-Manufacturing PMI jumped to 50.2 against a 49.3 forecast. RatingDog Manufacturing PMI climbed to 52.1 from 51.5 and Services PMI reached 51.6 versus 51.1 expected, together signaling broader stabilization in factory and services activity. Shanghai Composite advanced 0.31 percent to 3,842.19 and CSI 300 gained 0.29 percent to 4,357.62, whereas Hang Seng dropped 2.60 percent to 23,972.29 on losses tied to New World Development’s HK$18.3 billion airport-mall write-down.
TAIEX edged 0.25 percent higher to 48,475.74. USD/CNY eased 0.09 percent to 6.70 while USD/HKD held steady at 7.85. Copper rose 1.03 percent to 6.55 as a growth proxy, Brent Crude slipped 0.06 percent to 102.25, and gold fell 0.95 percent to 4,162.30.
China’s decision to reimpose limits on refined-product exports tightened domestic crude and fuel inventories and reduced available supply for global buyers.
The Day Ahead
No mainland, Hong Kong or Taiwan data releases are scheduled for October 4 or 5. Markets will monitor any unscheduled PBoC liquidity operations and State Council policy signals. HKMA aggregate-balance movements remain the key watch item for USD/HKD peg stability.
Taiwan semiconductor export figures and cross-strait trade data are not due until later in the month. Investors will also track global risk sentiment for spillover effects on regional equities and the yuan.
Other Economic Notes
China’s resumption of fuel-export curbs coincides with depleted domestic inventories and will support Brent prices near current levels. Property-sector stress remains visible after New World Development booked a US$2.33 billion loss on the terminated Hong Kong airport-mall project, underscoring ongoing balance-sheet pressure for developers. Rare-earth supply-chain dominance continues to constrain U.S.
downstream manufacturers despite Washington’s efforts to diversify sourcing. Copper’s daily gain reflects improving sentiment toward Chinese industrial demand following the PMI beat. No new cross-strait investment or semiconductor-regulation updates emerged overnight.