Greater China Macro Daily(Beta Mode)
Yuan at Four-Year High as PBoC Pushes Back
Market Snapshot
| Asset | Level | Change |
|---|---|---|
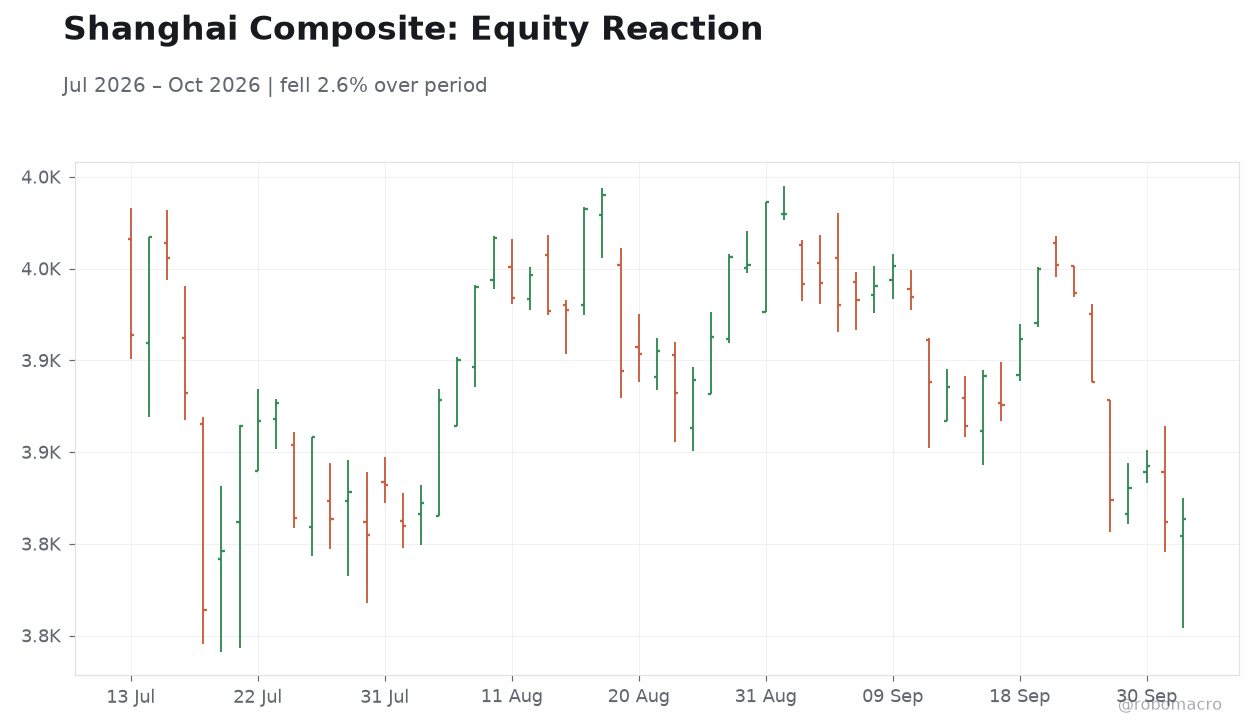
| Shanghai Composite | 3,813.79 | +0.05% |
| CSI 300 | 4,317.25 | +0.16% |
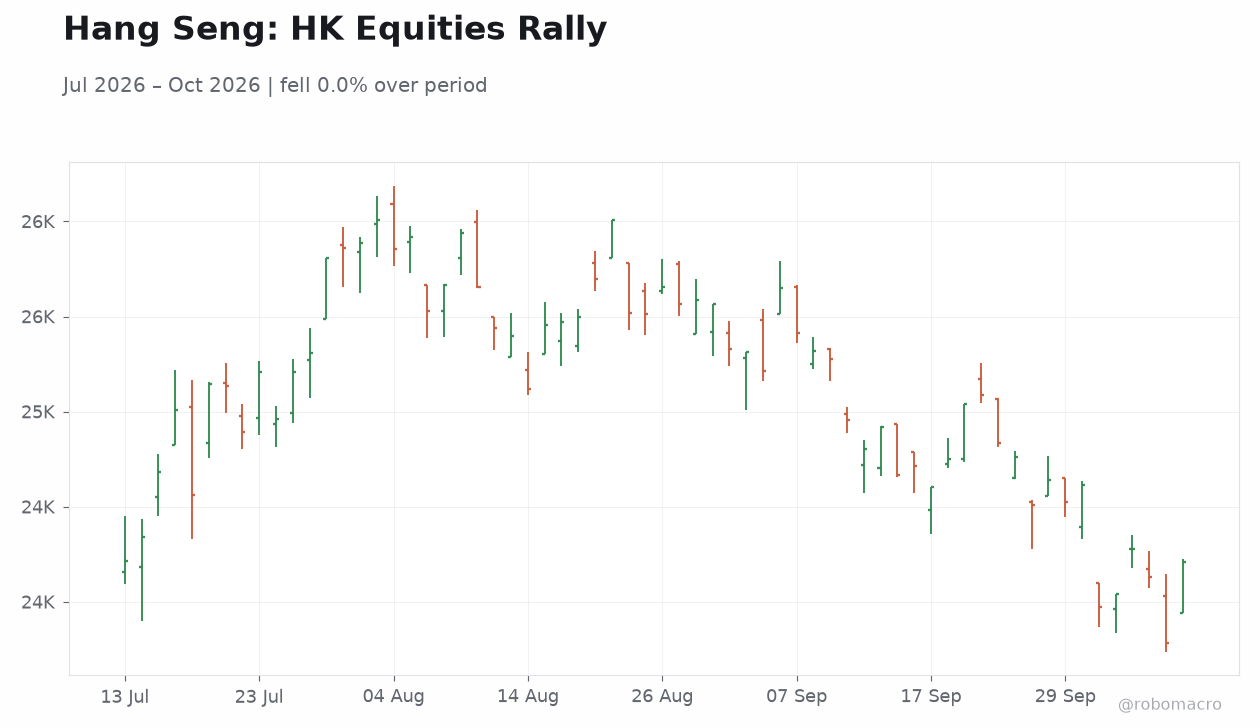
| Hang Seng | 24,211.35 | +1.79% |
| TAIEX | 49,313.44 | -0.99% |
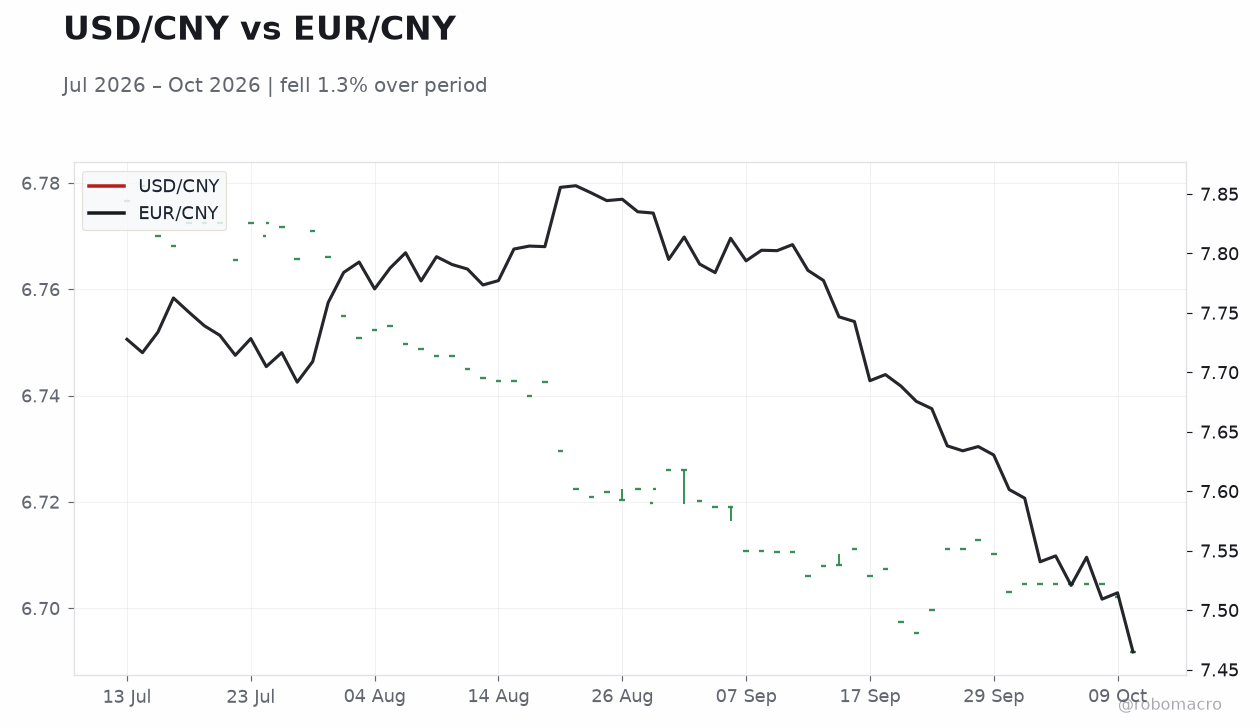
| USD/CNY | 6.69 | -0.15% |
| USD/HKD | 7.85 | -0.01% |
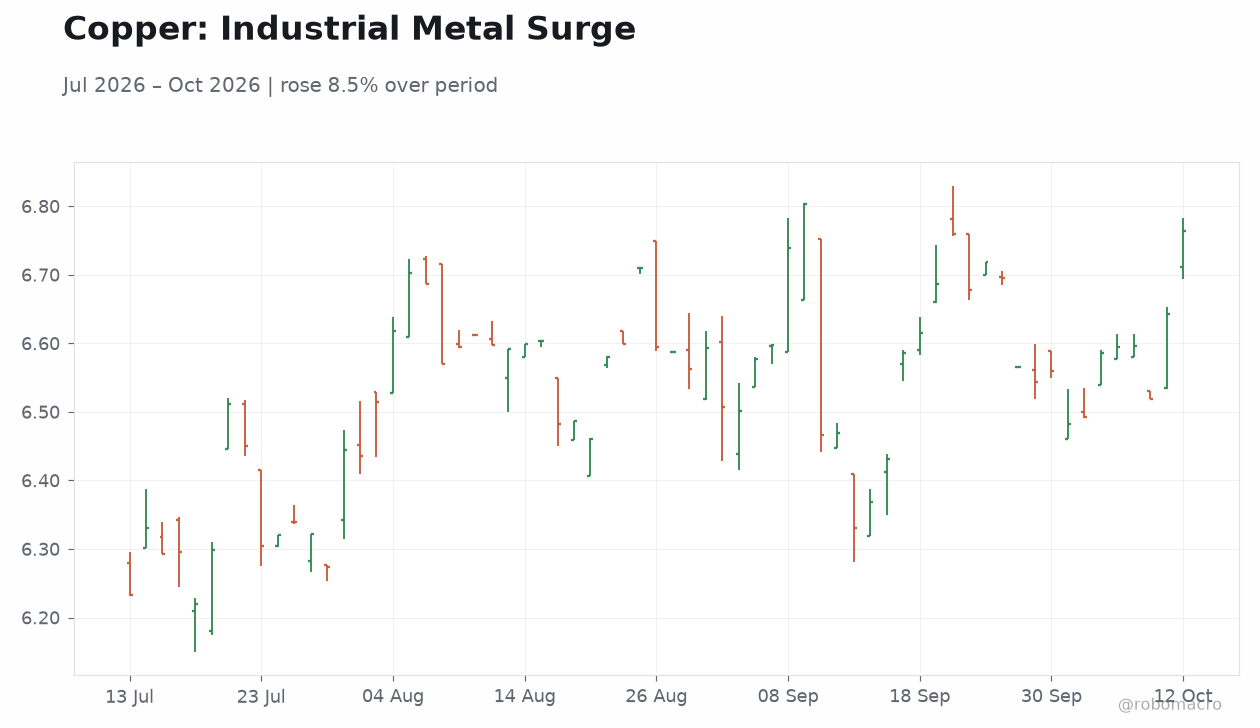
| Copper | 6.76 | +1.84% |
| Brent Crude | 105.92 | +1.15% |
| Gold | 4,195.90 | -0.48% |
| Bitcoin | 82,528.13 | -1.38% |
| China 2Y Govt Yield | - | - |
| China 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
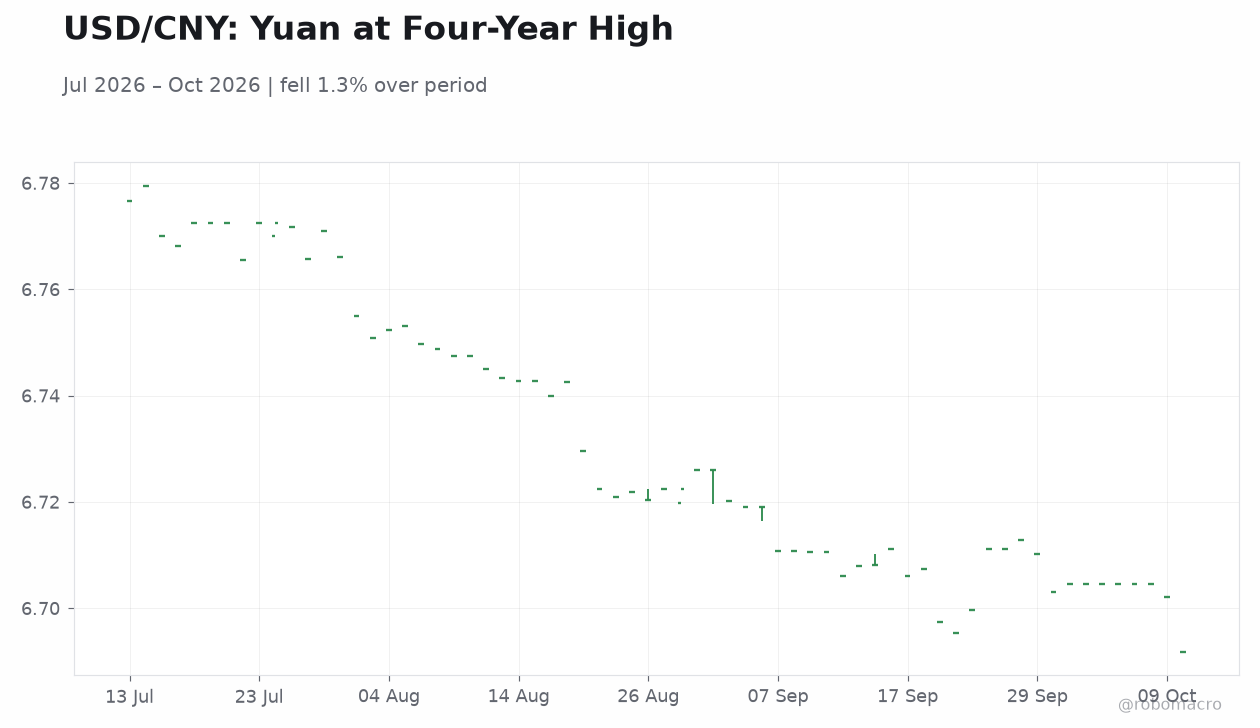 USD/CNY: Yuan at Four-Year High | Type: market_hloc | USD/CNY: 6.692 (2026-10-12) | Range: 6.692–6.78 | Trend(6pt): 6.777,6.752,6.72,6.706,6.702,6.692
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Inflation Rate Year-over-Year | 0.80 | 1.10 | 21:30 |
| Inflation Rate Month-over-Month | 0.40 | - | 21:30 |
| Producer Price Index Year-over-Year | 3.80 | 4.40 | 21:30 |
| Exports Year-over-Year | 25 | 25.30 | 23:00 |
| Imports Year-over-Year | 28.20 | 23.50 | 23:00 |
| Trade Balance | 119,100m | 114,500m | 23:00 |
- PBoC rejects undervaluation claims as the yuan hits a four-year high on a trade-weighted basis; fixing seen near 6.7174
- China CPI, PPI and trade data lead the docket, with exports seen moderating to 25.3% y/y
- Hang Seng gains 1.79% and copper jumps 1.84%; TAIEX slips 0.99% ahead of earnings
Yesterday's Recap
Mainland China dominated the session as currency policy took centre stage. The People's Bank of China publicly rejected claims that the yuan is undervalued, insisting the market determines the exchange rate, and the currency responded by climbing to a four-year high against a basket of trading-partner currencies. USD/CNY slipped 0.15% to 6.69, while the expected fixing near 6.7174 signals continued tolerance for measured appreciation.
Commerzbank and domestic outlets framed the PBoC's stance as a defence of its FX narrative rather than a shift to managed strength, an important distinction for exporters' margins. Equities diverged: the Hang Seng Index rallied 1.79% to 24,211.35, the Shanghai Composite edged up 0.05% to 3,813.79 and the CSI 300 added 0.16% to 4,317.25, but Taiwan's TAIEX fell 0.99% to 49,313.44. Hong Kong also secured the spotlight with confirmation that HSBC and Goldman Sachs will headline the HKMA's Global Financial Leaders' Summit in early November.
Copper's 1.84% surge to 6.76 reinforced the constructive China growth tone.
The Day Ahead
Mainland China releases a heavy slate tonight. At 21:30 ET, CPI is expected to accelerate to 1.1% y/y from 0.8%, with the m/m print and PPI — consensus 4.4% versus 3.8% prior — rounding out the inflation picture. At 23:00 ET, trade data takes centre stage: exports are seen easing to 25.3% y/y from 25.0%, while imports are forecast to slow sharply to 23.5% from 28.2%, implying a trade surplus near $114.5bn versus $119.1bn previously.
A softer import figure would feed the debate on domestic demand strength despite headline export momentum. The PBoC's daily fixing will be scrutinised for signals on how far officials will let the yuan run. Hong Kong and Taiwan have no major scheduled releases, leaving the mainland data to set the regional tone into Tuesday.
Other Economic Notes
The yuan's trade-weighted strength has distributional consequences: exporters' renminbi receipts buy more abroad, but competitiveness questions resurface just as Western policymakers revive undervaluation narratives — German commentary noted Beijing rejects the idea that a stronger yuan must come at Western behest. ↓ p.2