Greater China Macro Daily(Beta Mode)
Export Strength Lifts China Equities and Bonds
Market Snapshot
| Asset | Level | Change |
|---|---|---|
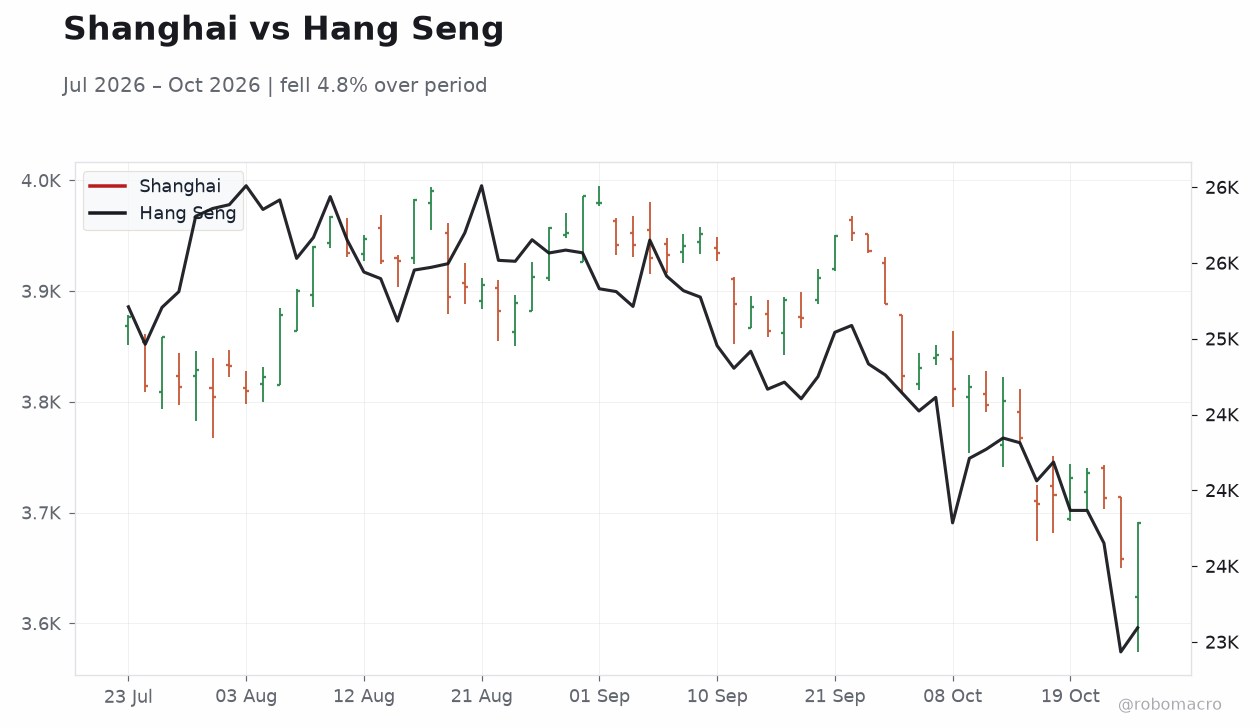
| Shanghai Composite | 3,690.48 | +0.89% |
| CSI 300 | 4,105.33 | +1.71% |
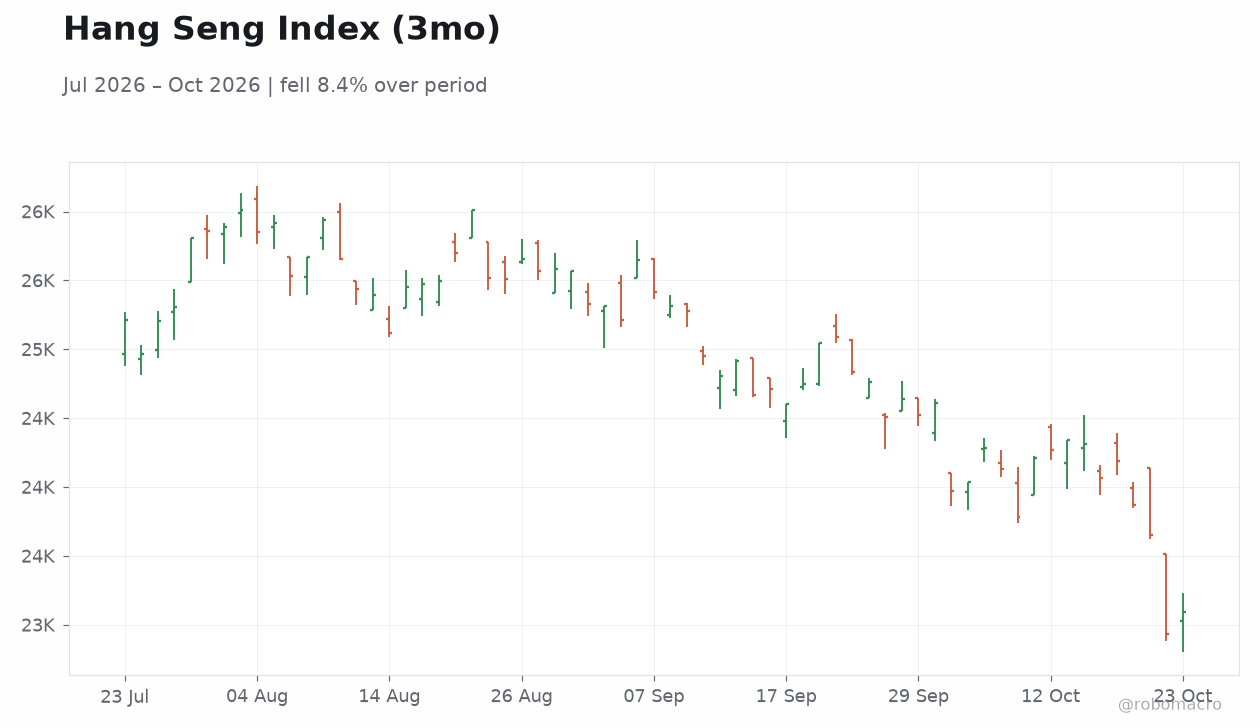
| Hang Seng | 23,093.37 | +0.69% |
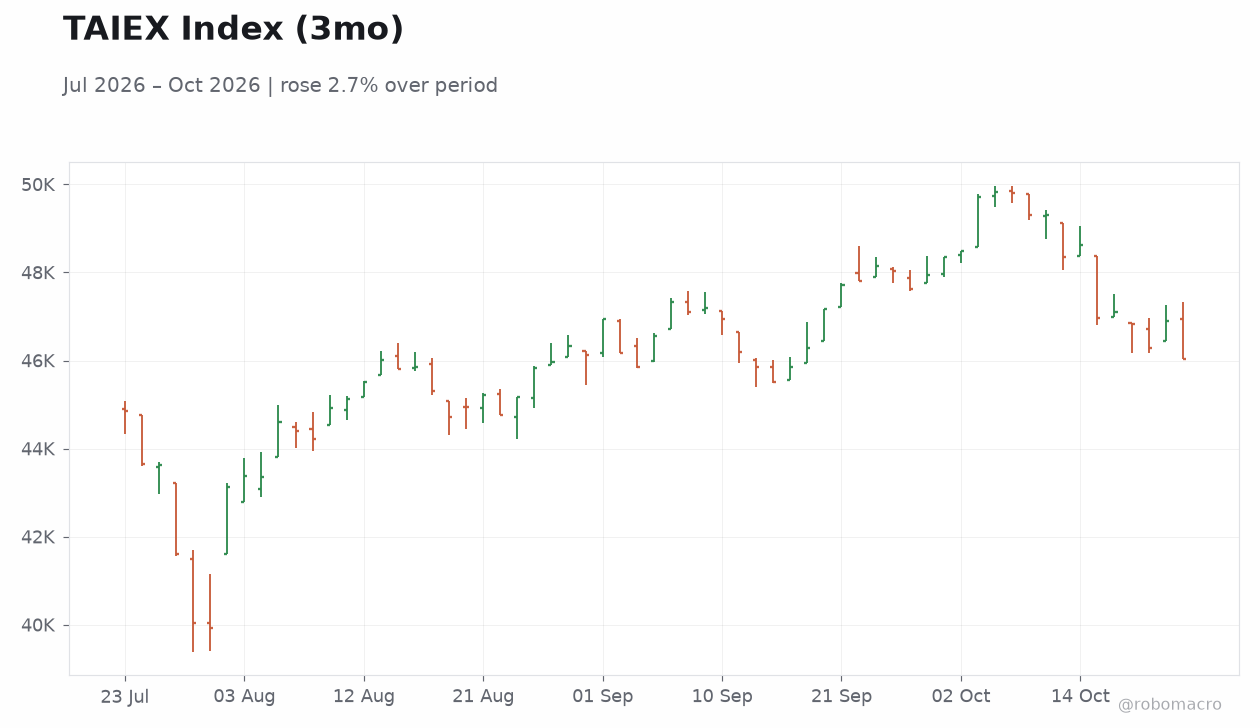
| TAIEX | 46,041.43 | -1.81% |
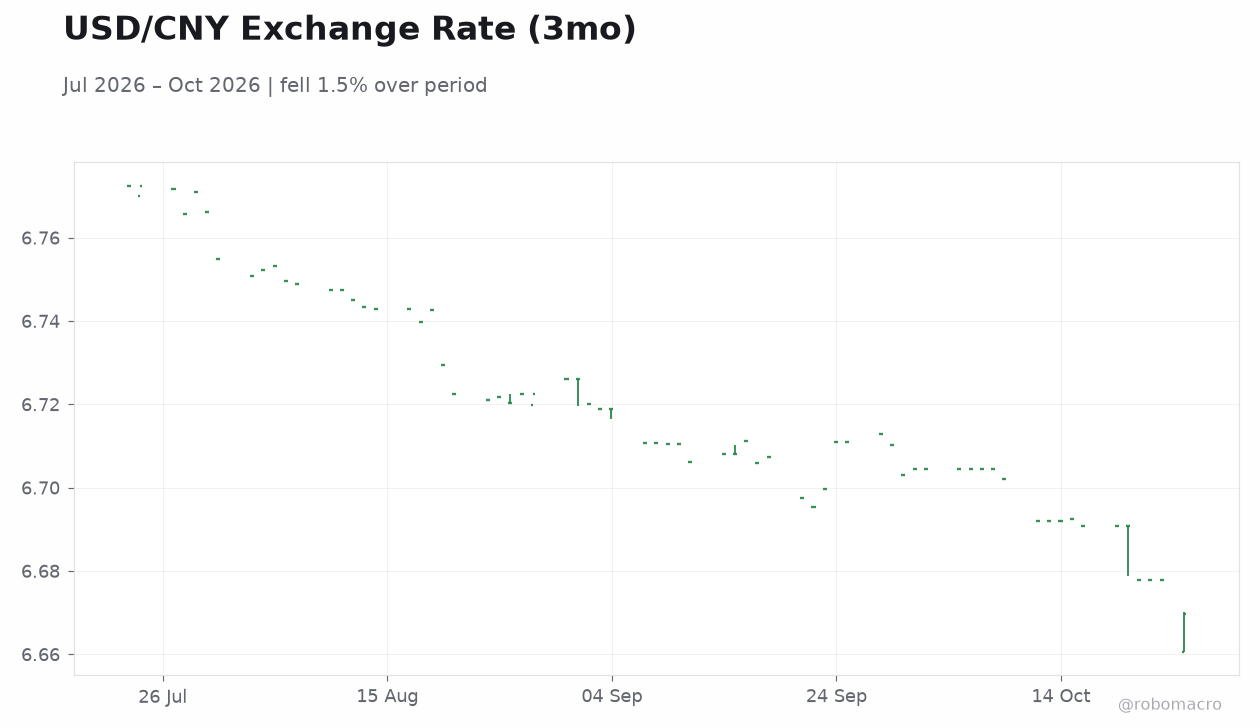
| USD/CNY | 6.67 | -0.12% |
| USD/HKD | 7.84 | +0.08% |
| Copper | 6.51 | +0.49% |
| Brent Crude | 111.70 | -4.30% |
| Gold | 4,007.90 | +0.00% |
| Bitcoin | 80,360.58 | -0.53% |
| China 2Y Govt Yield | - | - |
| China 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
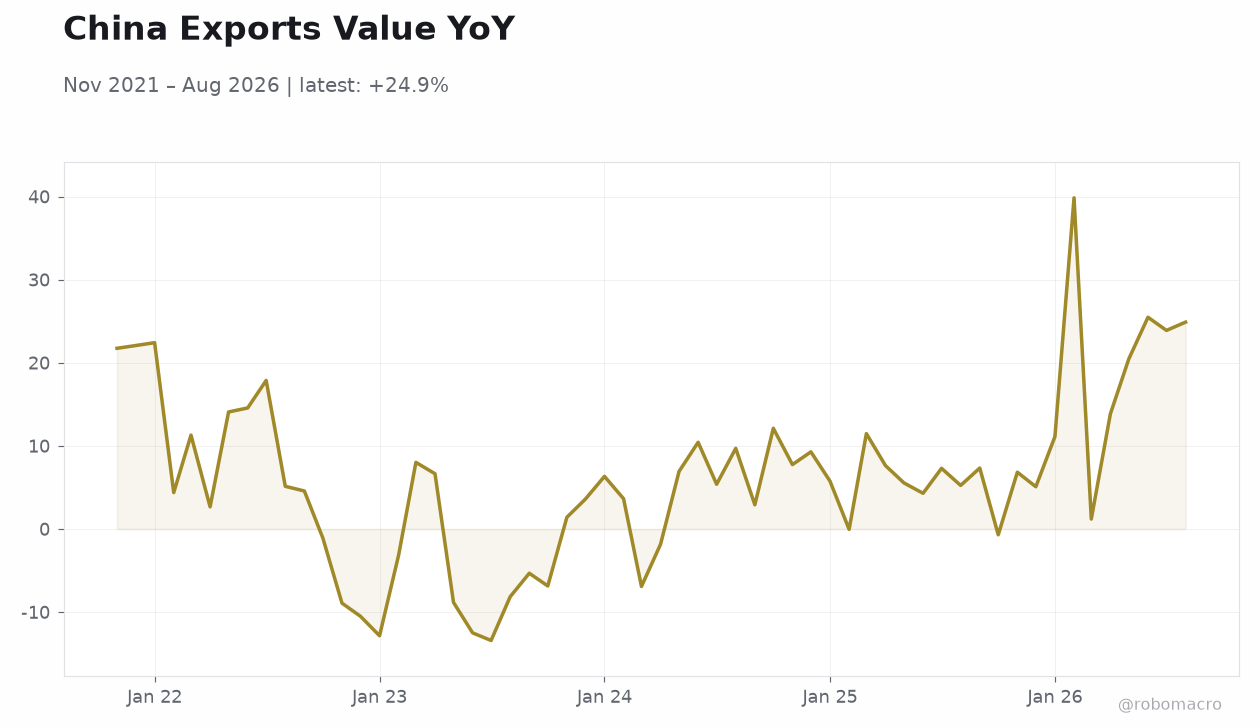 China Exports Value YoY | Type: macro_line | YoY %: 24.9 (2026-08-01) | Range: -13.41–39.85 | Trend(6pt): 21.75,-12.84,-6.912,5.548,23.9,24.9
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- China’s economy expanded 4.5% in Q3, driven by robust exports while domestic demand remained soft.
- Offshore yuan government bonds priced at record-low yields as onshore debt rallied and HKMA expanded RMB liquidity facilities.
- Mainland and Hong Kong equities rose while TAIEX declined; USD/CNY eased 0.12% to 6.67 amid stable policy signals.
Yesterday's Recap
Mainland China equities advanced sharply as the CSI 300 climbed 1.71% to 4,105.33 and the Shanghai Composite gained 0.89% to 3,690.48, supported by news that the economy grew 4.5% in the July-September quarter on strong exports. Hong Kong’s Hang Seng index rose 0.69% to 23,093.37 while Taiwan’s TAIEX fell 1.81% to 46,041.43. The offshore yuan strengthened modestly with USD/CNY declining 0.12% to 6.67.
China sold government bonds in Hong Kong at record-low yields across most maturities as offshore yields tracked the onshore rally. HKMA named Deutsche Bank an offshore yuan primary liquidity provider and raised the RMB repo facility to RMB22 billion while designating 12 banks as primary liquidity providers. Copper, a key China growth proxy, edged 0.49% higher to 6.51 while Brent crude dropped 4.30% to 111.70.
Gold held steady at 4,007.90.
The Day Ahead
No major data releases are scheduled across Greater China today. Markets will monitor follow-through from the offshore RMB bond tender results and any further signals from the State Council on stimulus implementation. Traders will also watch USD/HKD movements around the 7.84 level for signs of HKMA intervention.
Semiconductor supply-chain updates from Taiwan remain in focus given ongoing global tech demand. Cross-strait trade flows and any PBoC liquidity operations will provide additional color on policy stance.
Other Economic Notes
China’s export-led growth highlights the continued divergence between external and domestic demand, with industrial strength offsetting persistent property-sector weakness. Bridgewater’s China arm shifted to a prudently optimistic stance on local equities while reducing gold exposure, signaling selective foreign-investor interest. Fiscal policy moved only modestly from austerity before the recent stimulus package, leaving room for further support if domestic indicators soften.
Copper’s modest gain aligns with the export-driven growth narrative but remains sensitive to global industrial activity. Property-sector dynamics continue to weigh on broader consumption, keeping policy focus on targeted easing rather than broad rate cuts. The absence of fresh high-frequency indicators leaves the 4.5% Q3 print as the dominant reference point for assessing momentum.