Mainland Stocks Rally as Yuan Firms
Shanghai Composite3,690.48+0.89%
CSI 3004,105.33+1.71%
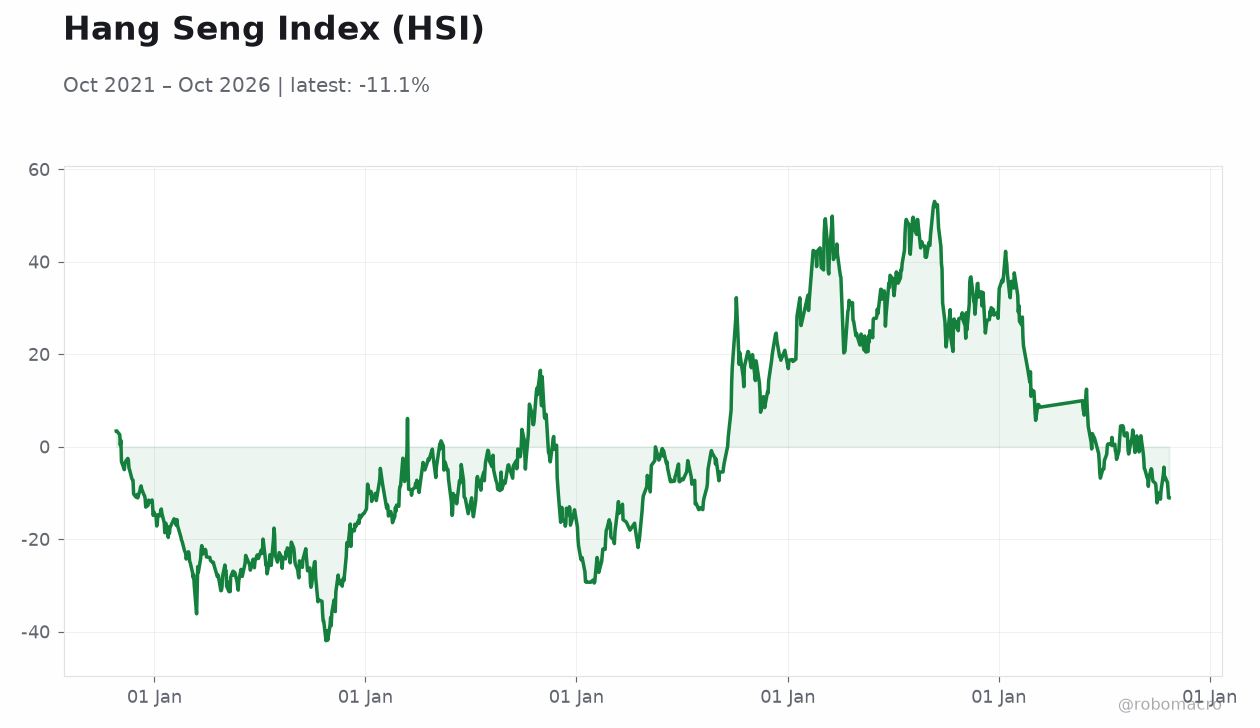
Hang Seng23,093.37+0.69%
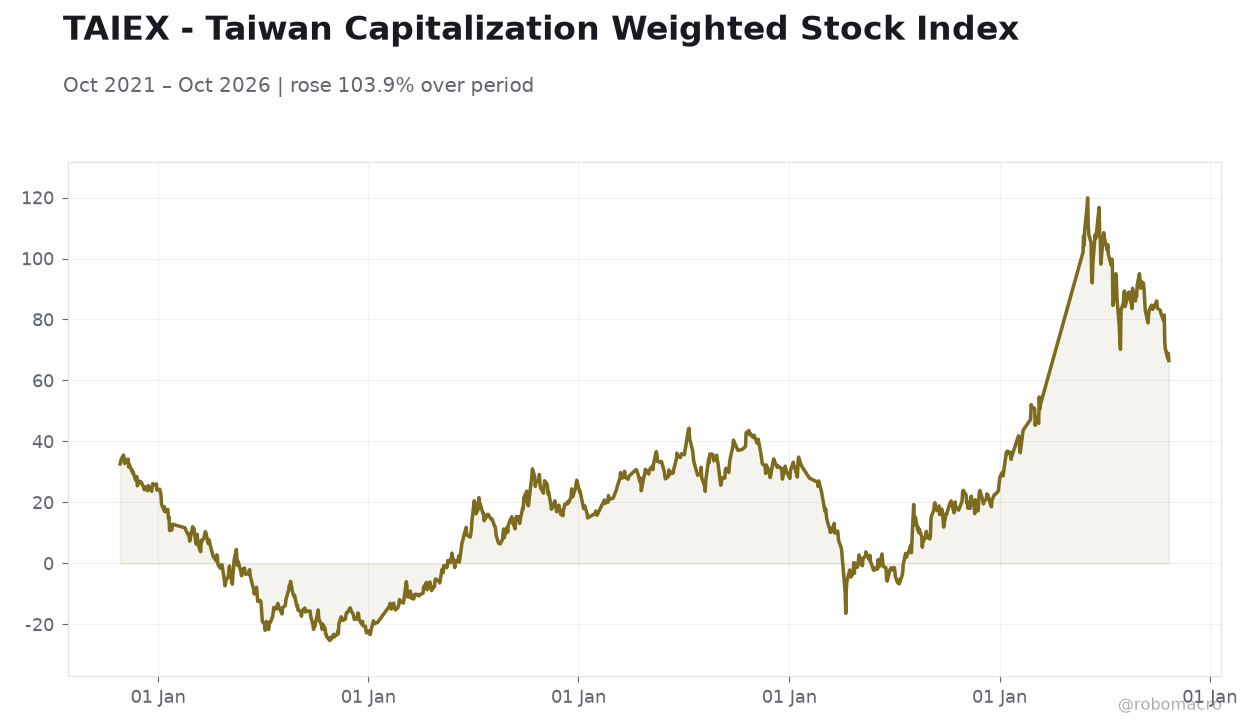
TAIEX46,041.43-1.81%
Market Snapshot
| Asset | Level | Change |
|---|
| Shanghai Composite | 3,690.48 | +0.89% |
| CSI 300 | 4,105.33 | +1.71% |
| Hang Seng | 23,093.37 | +0.69% |
| TAIEX | 46,041.43 | -1.81% |
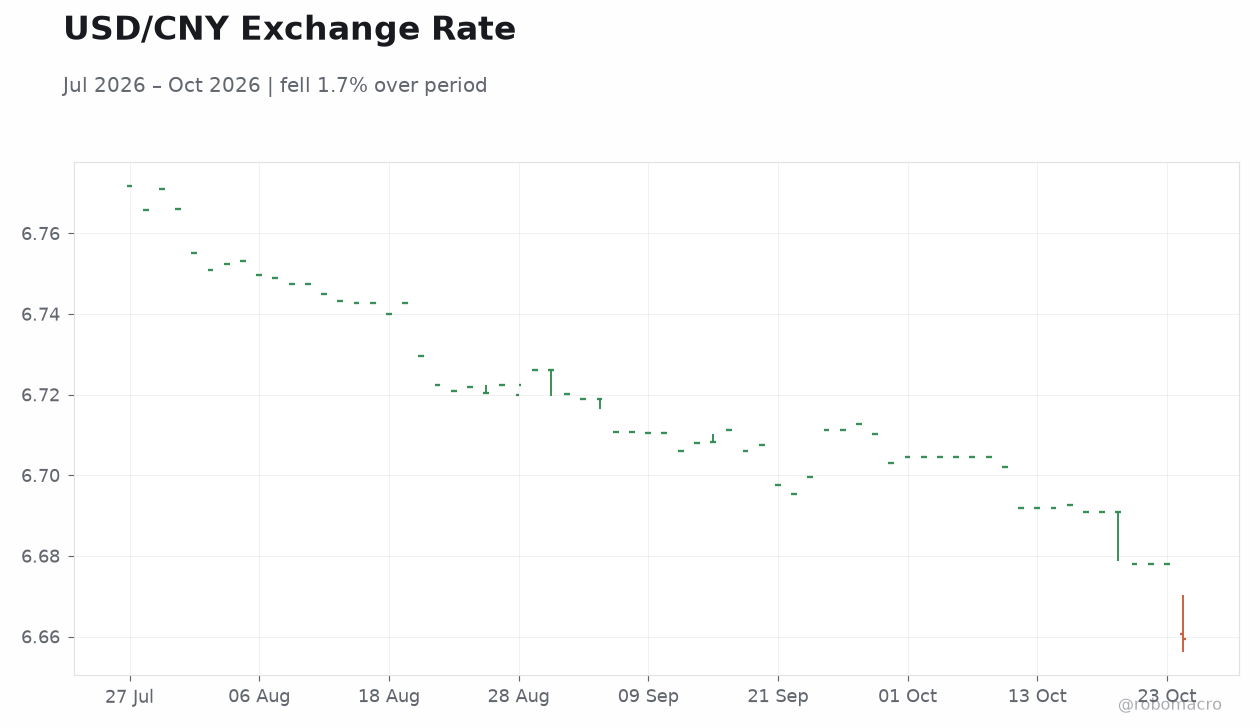
| USD/CNY | 6.66 | -0.28% |
| USD/HKD | 7.84 | +0.10% |
| Copper | 6.54 | +1.06% |
| Brent Crude | 110.27 | -5.53% |
| Gold | 4,031.00 | +0.58% |
| Bitcoin | 79,897.54 | -0.16% |
| China 2Y Govt Yield | - | - |
| China 10Y Govt Yield | - | - |
Prior Economic Events
| Data |
Prior |
Cons |
Actual |
| No events available |
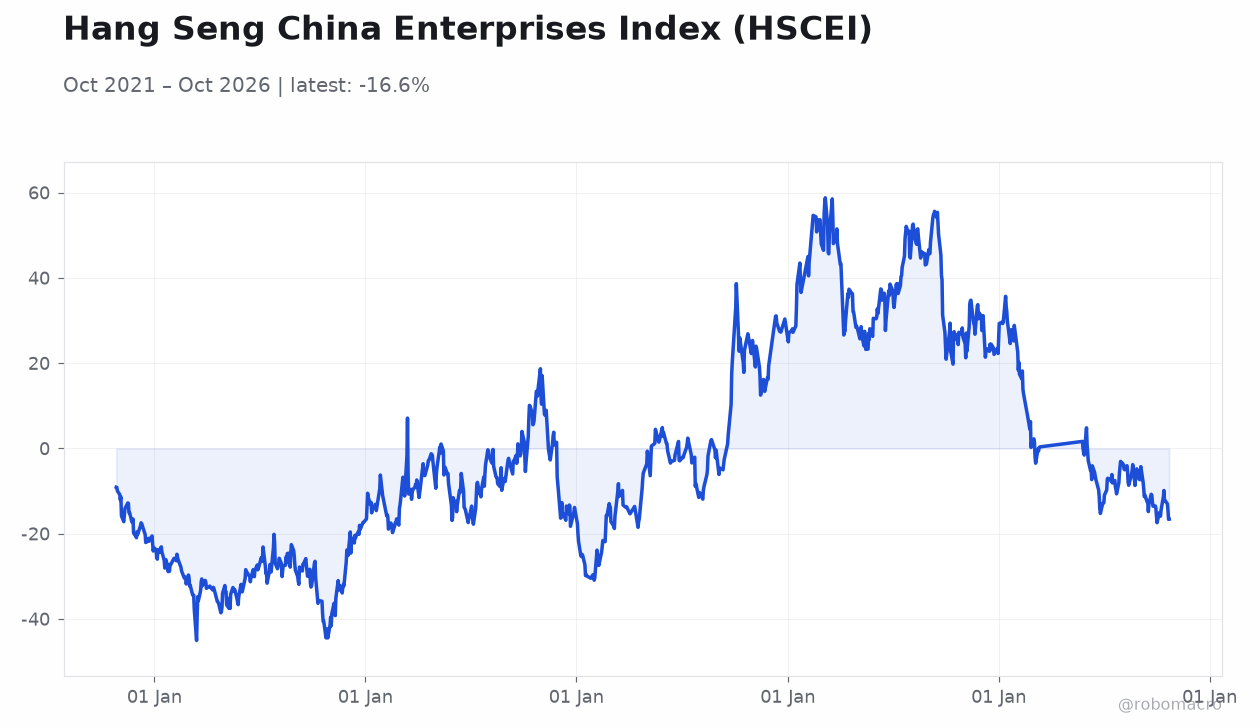
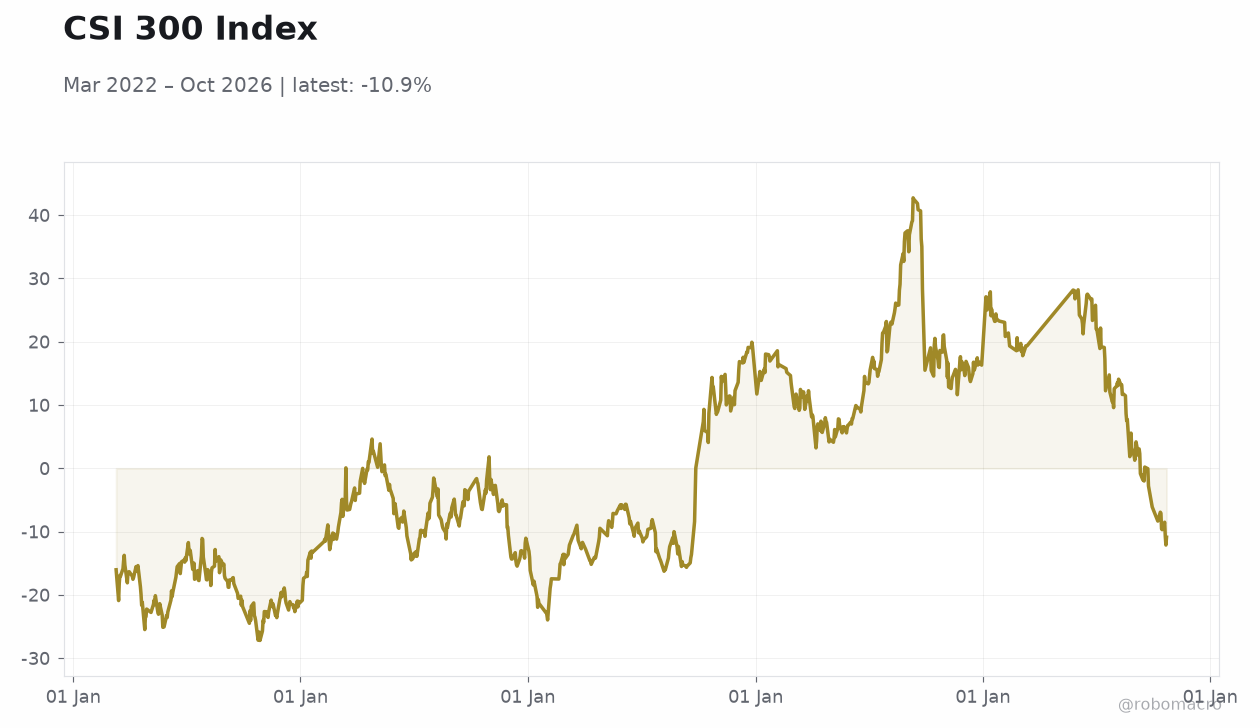 CSI 300 Index | Type: macro_line | CSI 300 Index: -10.88 (2026-10-23) | Range: -27.2–42.74 | Trend(5pt): -16.02,-5.552,-11.58,15.61,-10.88
Today's Economic Events
| Data |
Prior |
Cons |
Time |
| NBS Manufacturing PMI | 50.10 | 50.10 | 21:30 |
| NBS Non-Manufacturing PMI | 50.20 | 50.50 | 21:30 |
- CSI 300 surges 1.71% while Shanghai Composite gains 0.89% on export resilience and offshore yuan bond demand.
- HKMA designates 12 primary liquidity providers and lifts yuan repo facility to RMB22 billion to deepen offshore market.
- TAIEX falls 1.81% as Taiwan equities lag amid broader regional rotation; USD/CNY drops 0.28% to 6.66.
Yesterday's Recap
Mainland Chinese equities posted solid gains on October 25, with the CSI 300 climbing 1.71% to 4,105.33 and the Shanghai Composite advancing 0.89% to 3,690.48. The moves reflected continued strength in exports, which supported third-quarter growth despite persistent domestic softness. Offshore yuan bonds priced at record-low yields in Hong Kong, tracking the onshore rally and signaling sustained investor appetite for Chinese debt.
The HKMA announced the appointment of 12 banks as primary liquidity providers and expanded the yuan repo facility to RMB22 billion, measures aimed at bolstering offshore yuan market depth. In contrast, the TAIEX declined 1.81% to 46,041.43 as Taiwan equities faced selling pressure. USD/CNY eased 0.28% to 6.66, reflecting modest yuan appreciation.
Copper rose 1.06% to 6.54, consistent with China demand signals, while Brent crude fell 5.53% to 110.27. China’s economy expanded 4.5% in the July-September quarter, driven by robust exports while domestic demand remained subdued. The central bank has emphasized industrial competitiveness rather than currency depreciation as the key export driver.
Fiscal policy shifted only modestly from austerity before recent stimulus measures were introduced. Property sector weakness continues to weigh on consumption, keeping policy focus on targeted liquidity support.
The Day Ahead
Markets will monitor the October 30 release of NBS Manufacturing PMI and Non-Manufacturing PMI, both due at 21:30 ET. The manufacturing print is expected to hold at 50.1 while non-manufacturing is forecast to edge up to 50.5. No other high-impact Greater China data are scheduled for the immediate session.
Traders will also watch PBoC liquidity operations and any State Council commentary on fiscal support. Equity flows into mainland indices may remain sensitive to export data trends and offshore bond performance. The stronger yuan helps contain imported inflation pressures while export resilience contrasts with softer domestic indicators, keeping external demand central to growth forecasts.
Page 1
Never miss an issue
Subscribe to Greater China Macro Daily and get each new issue delivered to your inbox.
Already a member? Visit robomacro.com
to log in and manage subscriptions, or use Forgot Password to set a password.