China Equities Diverge Ahead of PMI Releases
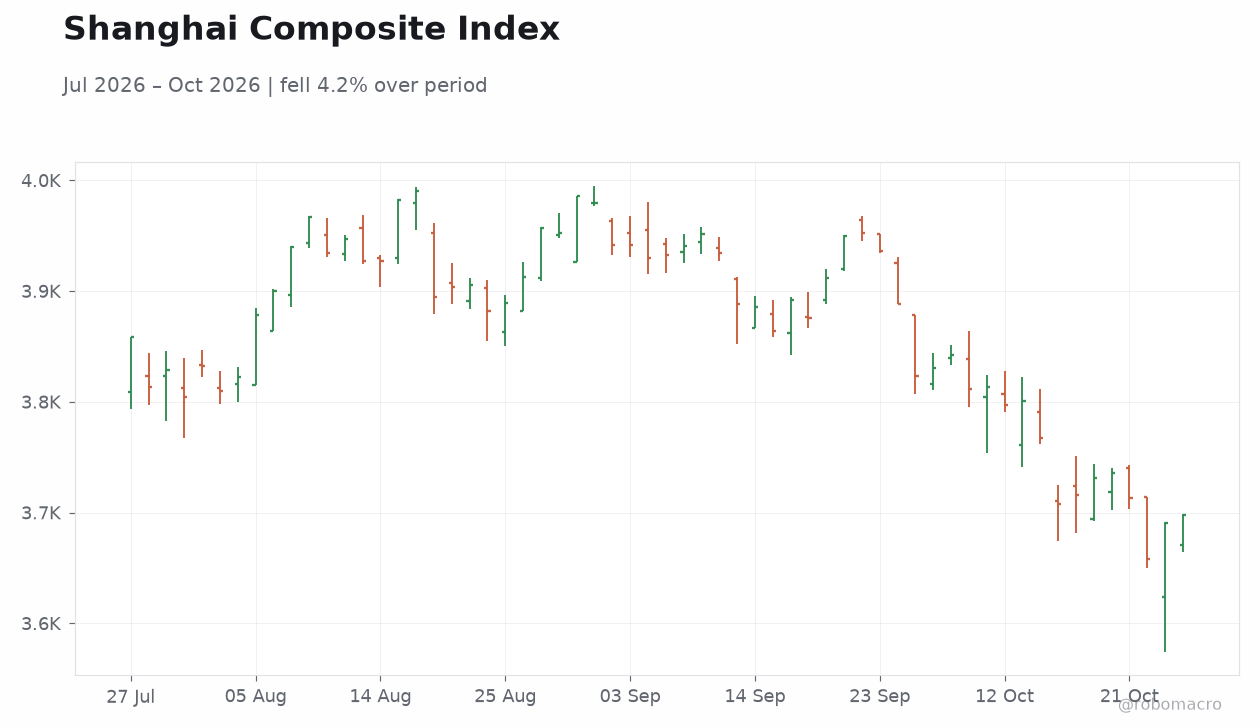
Shanghai Composite3,678.05-0.53%
CSI 3004,049.55-1.36%
Hang Seng23,211.81+0.51%
TAIEX46,041.43-1.81%
Market Snapshot
| Asset | Level | Change |
|---|
| Shanghai Composite | 3,678.05 | -0.53% |
| CSI 300 | 4,049.55 | -1.36% |
| Hang Seng | 23,211.81 | +0.51% |
| TAIEX | 46,041.43 | -1.81% |
| USD/CNY | 6.67 | -0.19% |
| USD/HKD | 7.84 | +0.02% |
| Copper | 6.66 | +2.35% |
| Brent Crude | 109.74 | -5.24% |
| Gold | 4,073.10 | +0.86% |
| Bitcoin | 80,743.29 | +0.92% |
| China 2Y Govt Yield | - | - |
| China 10Y Govt Yield | - | - |
Prior Economic Events
| Data |
Prior |
Cons |
Actual |
| No events available |
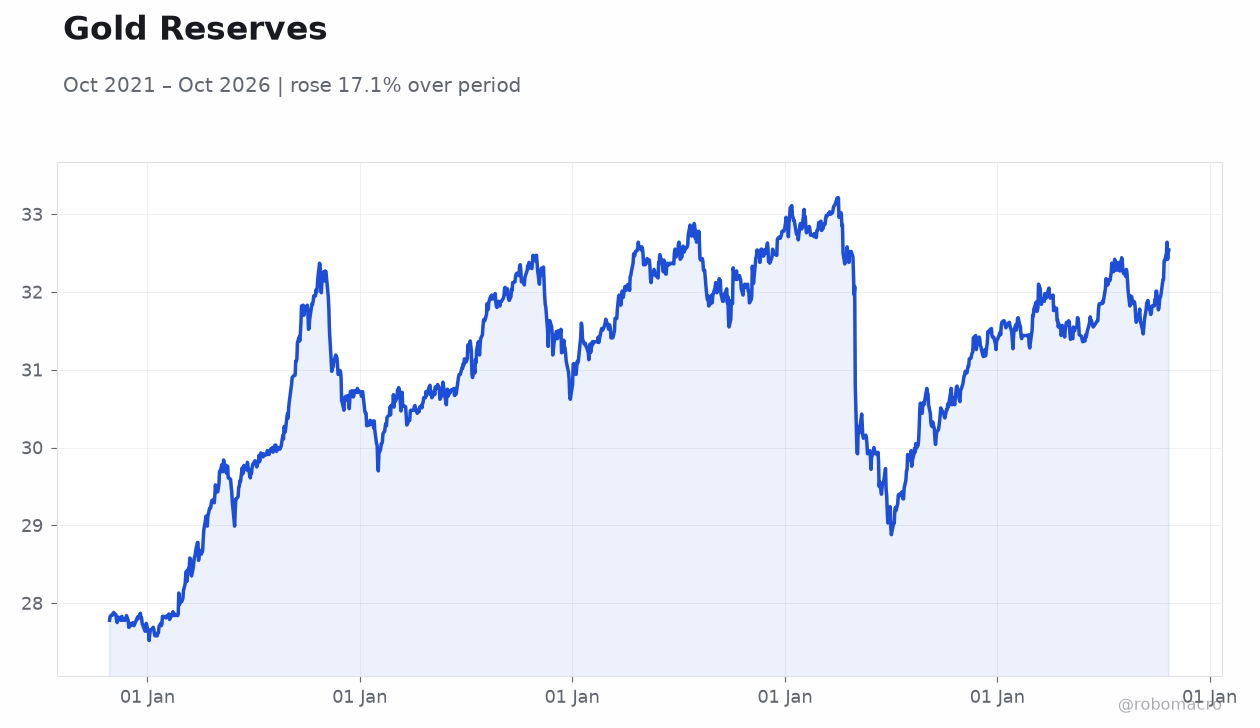
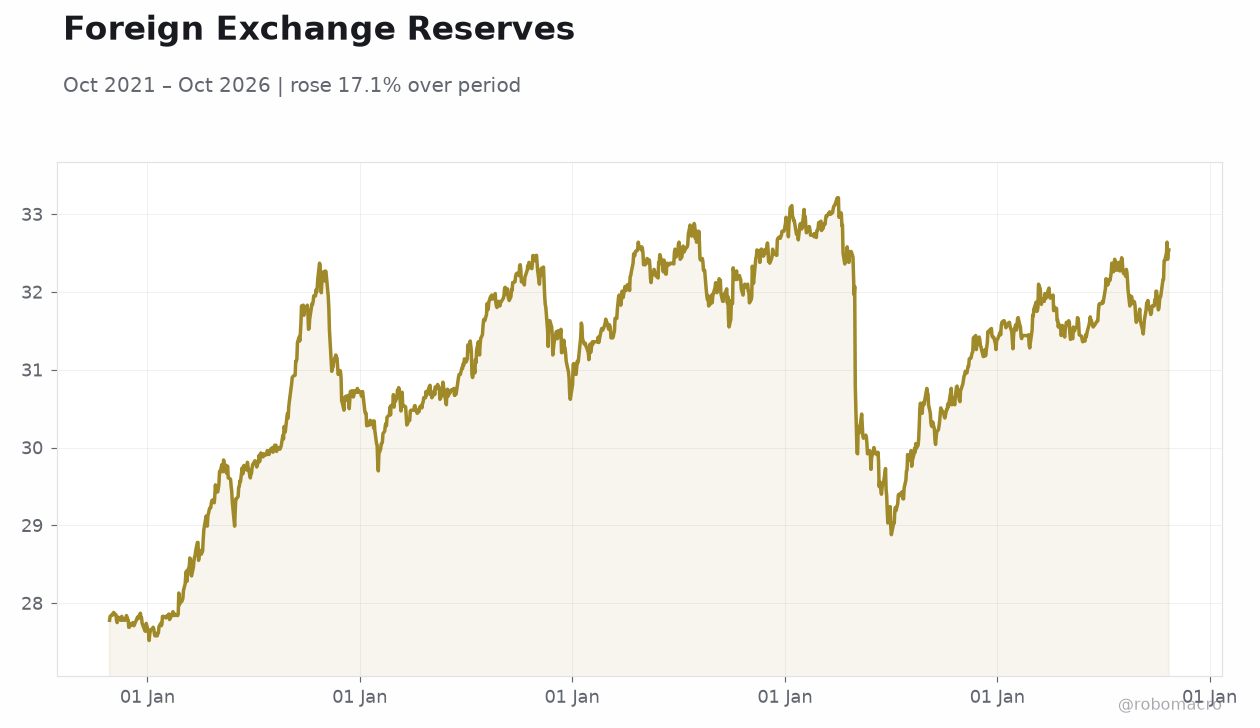 Foreign Exchange Reserves | Type: macro_line | Foreign Exchange Reserves: 32.54 (2026-10-23) | Range: 27.52–33.21 | Trend(6pt): 27.78,30.05,32.58,29.34,32.42,32.54
Today's Economic Events
| Data |
Prior |
Cons |
Time |
| NBS Manufacturing PMI | 50.10 | 50.10 | 21:30 |
| NBS Non-Manufacturing PMI | 50.20 | 50.50 | 21:30 |
- CSI 300 fell 1.36% while Hang Seng rose 0.51% as investors positioned ahead of October PMI releases.
- HKMA designated 12 primary liquidity providers and expanded the yuan repo facility to 22 billion yuan.
- Copper gained 2.35% on signs of resilient China demand despite broader equity weakness.
Yesterday's Recap
Mainland China equities declined sharply with the CSI 300 dropping 1.36% to 4,049.55 and the Shanghai Composite easing 0.53% to 3,678.05. Taiwan’s TAIEX fell 1.81% to 46,041.43 amid semiconductor supply-chain concerns. Hong Kong bucked the trend as the Hang Seng advanced 0.51% to 23,211.81.
The USD/CNY rate declined 0.19% to 6.67, reflecting modest yuan support. Copper rose 2.35% to 6.66 as traders weighed China demand strength against AI-related weakness elsewhere. Brent crude dropped 5.24% to 109.74 while gold climbed 0.86% to 4,073.10.
No major data releases occurred across Greater China on October 26. State-backed ETF inflows reached the highest level since the April 2025 rout, signaling continued official efforts to stabilize mainland equities. Morgan Stanley highlighted further downside risk for Chinese stocks given softening consumption momentum.
Property-sector refinancing activity remains elevated, with Gaw Capital seeking to roll over a HK$14.4 billion facility. Cross-strait semiconductor linkages continue to influence Taiwan equity performance amid global AI demand fluctuations.
The Day Ahead
Markets will focus on the NBS Manufacturing PMI and Non-Manufacturing PMI scheduled for release on October 30. Both prints carry high market impact and will provide fresh readings on mainland China activity after the August CPI figure of 0.80% YoY. Analysts expect the manufacturing gauge to hold near 50.1 while the non-manufacturing index is projected at 50.5.
Any material deviation could shift expectations for PBoC liquidity operations in November. Equity and commodity traders will also monitor follow-through from the HKMA’s yuan repo expansion. Copper prices steadied as investors balanced AI-stock weakness against China demand signals.
The US Export-Import Bank reauthorization debate intensified, with lawmakers citing the need to counter China’s global energy financing reach. An EU-China agreement on hybrid-vehicle exports eased some trade tensions but offered limited relief to European automakers. South Korea’s Q3 GDP beat forecasts on semiconductor exports, underscoring regional supply-chain linkages to Taiwan.
↓ p.2
Page 1
Never miss an issue
Subscribe to Greater China Macro Daily and get each new issue delivered to your inbox.
Already a member? Visit robomacro.com
to log in and manage subscriptions, or use Forgot Password to set a password.