Greater China Macro Daily(Beta Mode)
HKMA Holds Base Rate as Taiwan Tech Surges
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| Shanghai Composite | 3,656.53 | -0.68% |
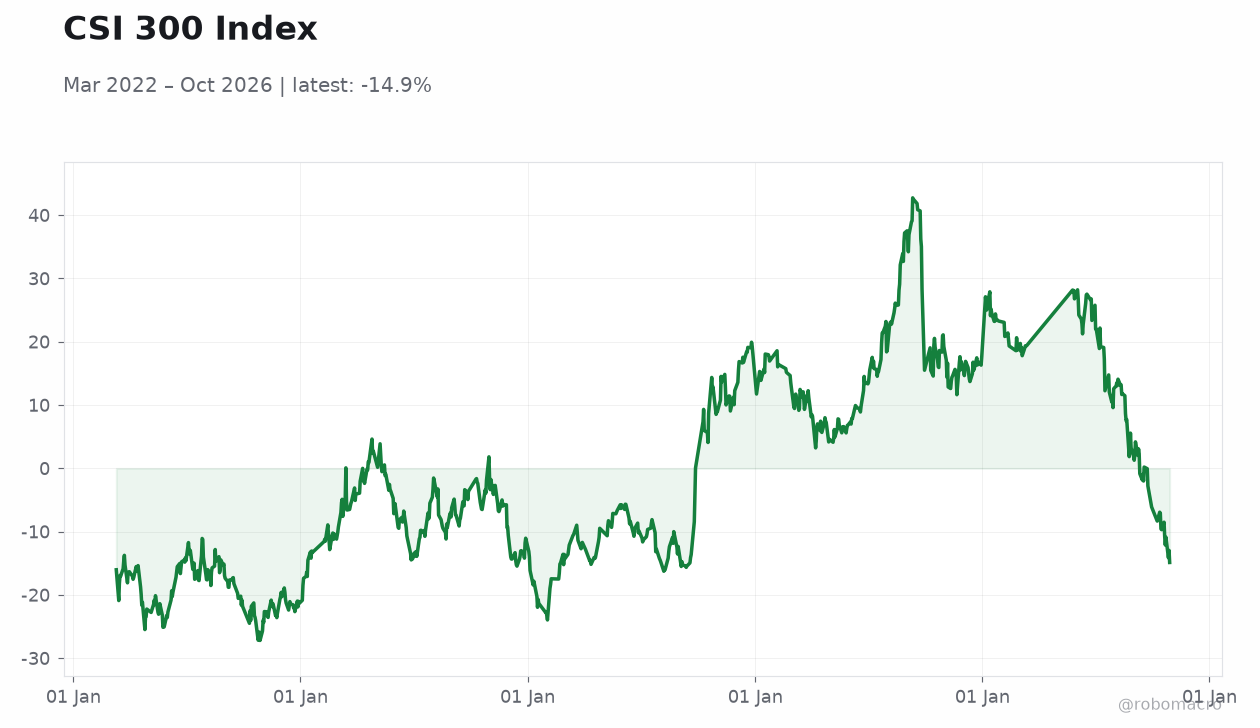
| CSI 300 | 4,041.84 | -1.03% |
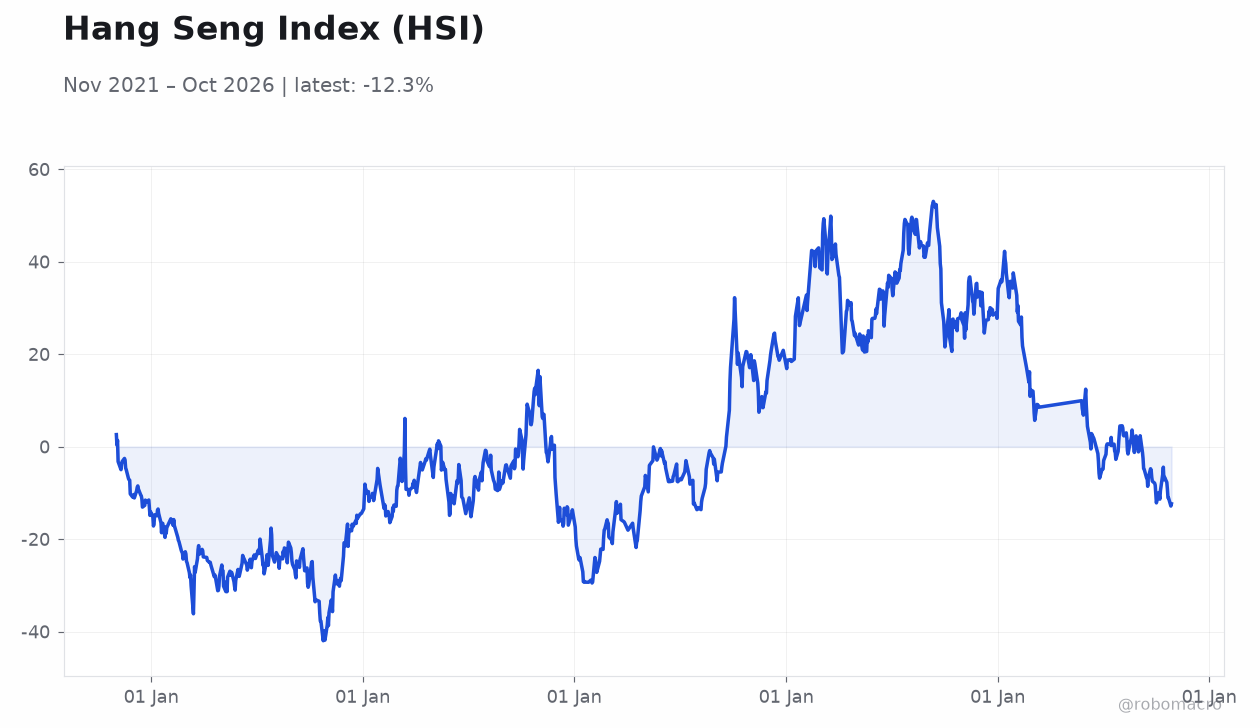
| Hang Seng | 23,094.83 | +0.23% |
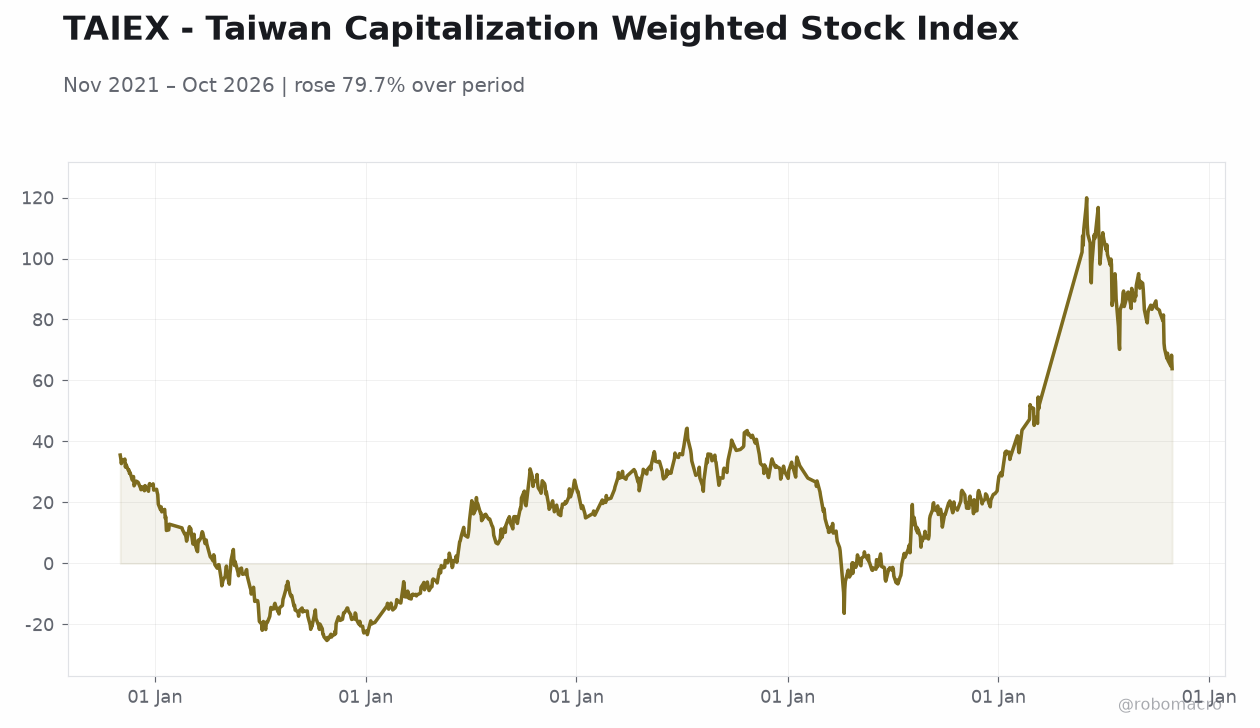
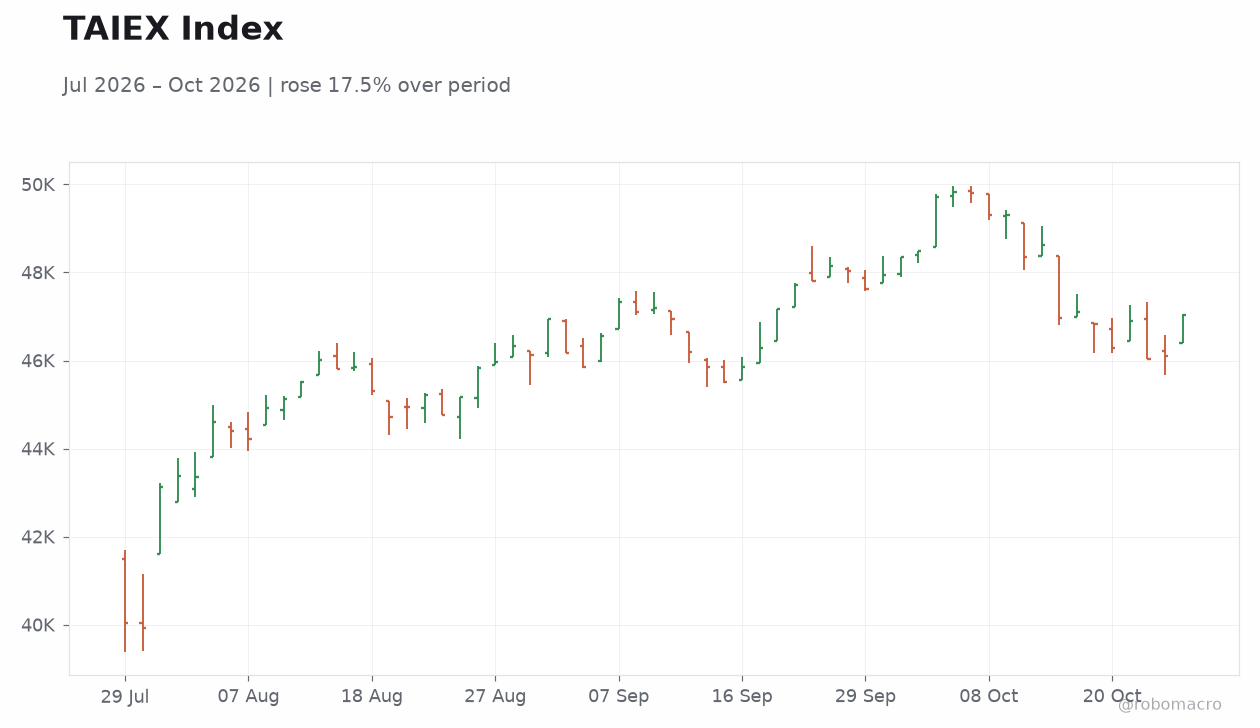
| TAIEX | 47,035.58 | +2.04% |
| USD/CNY | 6.66 | -0.11% |
| USD/HKD | 7.85 | +0.01% |
| Copper | 6.59 | -0.78% |
| Brent Crude | 111.54 | -3.28% |
| Gold | 4,033.30 | -0.45% |
| Bitcoin | 78,834.82 | -2.99% |
| China 2Y Govt Yield | - | - |
| China 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
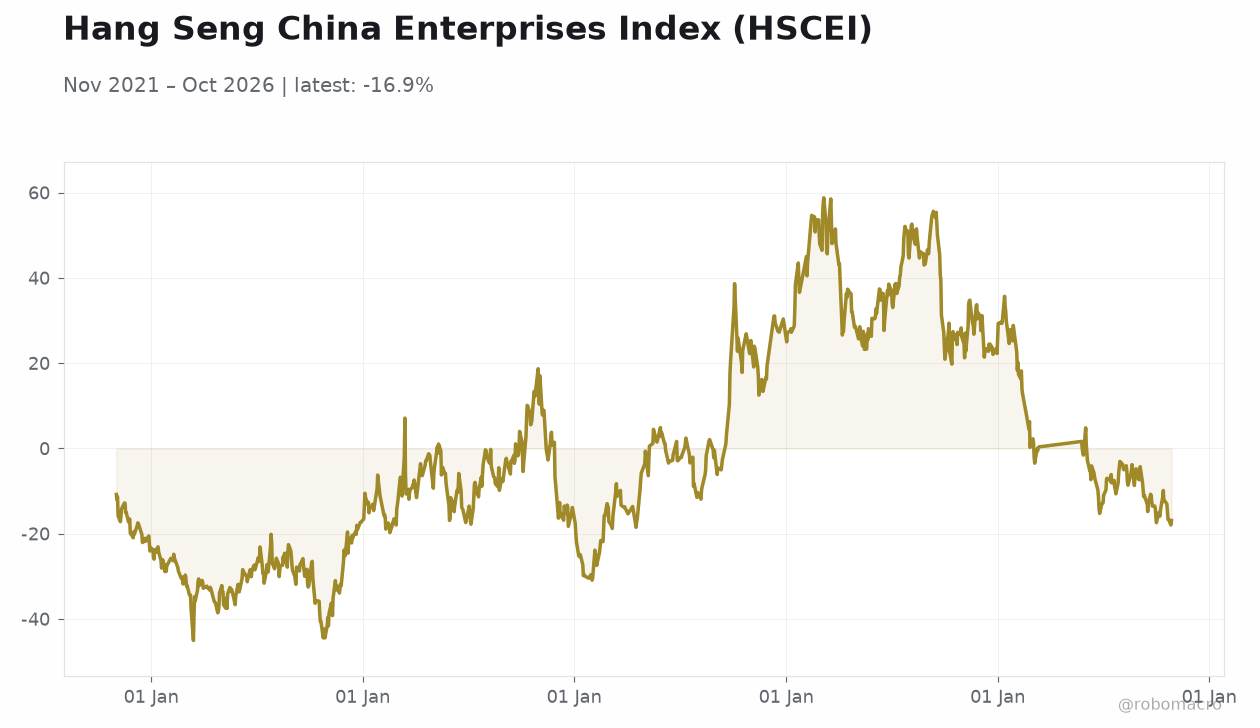 Hang Seng China Enterprises Index (HSCEI) | Type: macro_line | Hang Seng China Enterprises Index (HSCEI): -16.9 (2026-10-28) | Range: -45.05–58.79 | Trend(5pt): -10.8,-22.18,-23.86,36.99,-16.9
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Friday (2026-10-30) | |||
| NBS Manufacturing PMI | 50.10 | 50.10 | 21:30 |
| NBS Non-Manufacturing PMI | 50.20 | 50.50 | 21:30 |
- HKMA kept its base rate at 4.25% following the Fed's pause, warning the HK-US rate gap keeps carry-trade pressure on the HKD peg.
- Taiwan equities jumped 2.04% on an AI-driven semiconductor rally, while mainland benchmarks slipped (CSI 300 -1.03%) ahead of Friday's NBS PMIs.
- Brent crude fell 3.28% to $111.54 and copper eased 0.78%, softening China's imported cost backdrop as the yuan firmed to 6.66.
Yesterday's Recap
Hong Kong was the policy focal point, with the HKMA holding its base rate at 4.25% in lockstep with the Federal Reserve's decision to stand pat, and the authority explicitly flagging that the wide Hong Kong-US rate gap leaves the currency exposed to gradual weakening and carry-trade pressure. The HKD sat at the weak end of the band at 7.85, up 0.01% on the day, keeping intervention risk live. Mainland equities softened, with the CSI 300 down 1.03% to 4,041.84 and the Shanghai Composite off 0.68% to 3,656.53, as investors positioned defensively into Friday's manufacturing survey.
Taiwan was the clear outperformer, the TAIEX surging 2.04% to 47,035.58 on an AI-driven tech rally that also lifted South Korean stocks, reinforcing the island's centrality to the global AI chip supply chain. The yuan strengthened 0.11% to 6.66, a modest but notable firming against a backdrop of softer commodity inputs. Cross-asset signals were mixed: Brent slumped 3.28% to $111.54, copper slipped 0.78% to 6.59, gold eased 0.45% to $4,033.30, and bitcoin dropped 2.99% to 78,834.82, pointing to a broader risk-off tone outside Asian tech.
On the policy front, China's leadership vowed a tougher corruption crackdown, laying groundwork for next year's party congress.
The Day Ahead
The dominant event is Friday's NBS manufacturing PMI for mainland China, with consensus at 50.1, unchanged from the prior reading, alongside the non-manufacturing PMI where consensus sits at 50.5 versus 50.2 previously. A manufacturing print at or below the 50 boom-bust line would reinforce the narrative of a stalling industrial recovery and sharpen expectations for additional PBoC support. The non-manufacturing survey will be watched for any sign that services and construction are offsetting factory weakness, particularly given the property sector's drag.
No Hong Kong or Taiwan top-tier releases are scheduled, so flows will be driven by positioning around the mainland data and by follow-through in the AI-linked tech complex. Traders will also monitor the HKD's drift toward 7.85 for any HKMA aggregate-balance operations.
Other Economic Notes
China's external trade narrative continues to shift, with reports suggesting Beijing wants US soybeans but domestic buyers prefer Brazilian supply, a reminder that purchase commitments do not automatically translate into flows. ↓ p.2