Greater China Macro Daily(Beta Mode)
China PMIs Contract as Taiwan GDP Surges
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| Shanghai Composite | 3,599.02 | -1.44% |
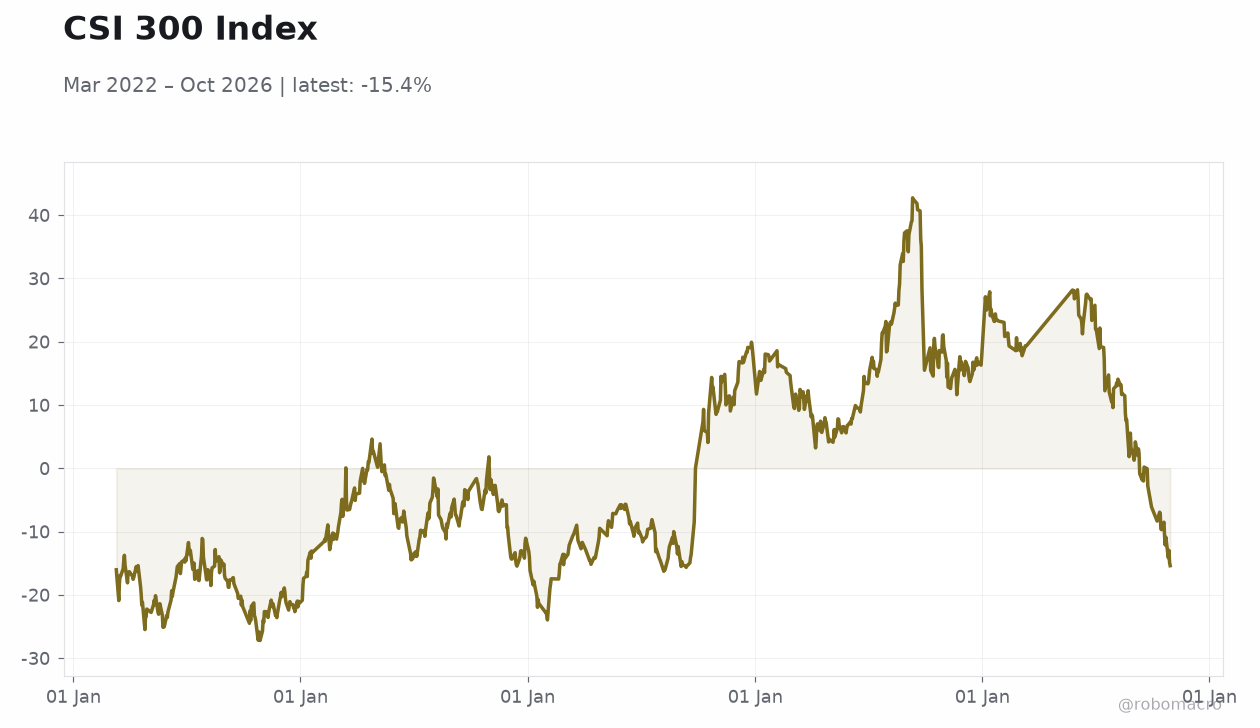
| CSI 300 | 3,985.50 | -1.39% |
| Hang Seng | 23,294.42 | +1.46% |
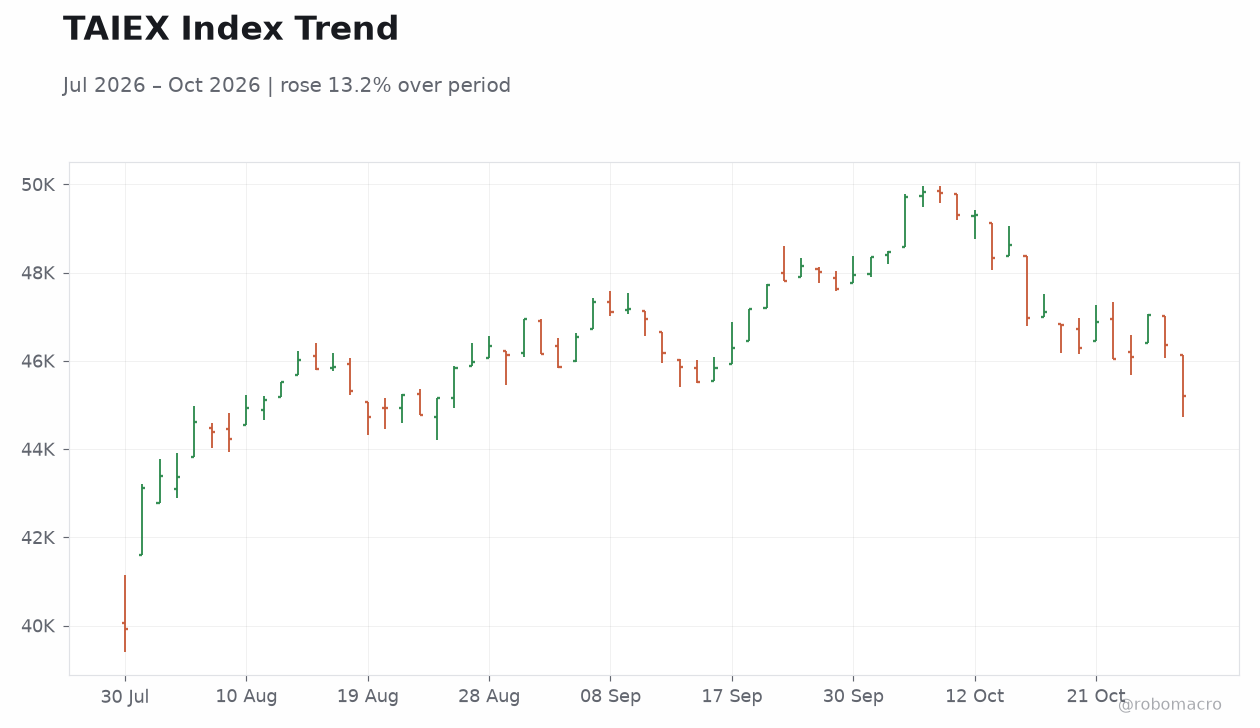
| TAIEX | 45,211.83 | -2.49% |
| USD/CNY | 6.64 | -0.24% |
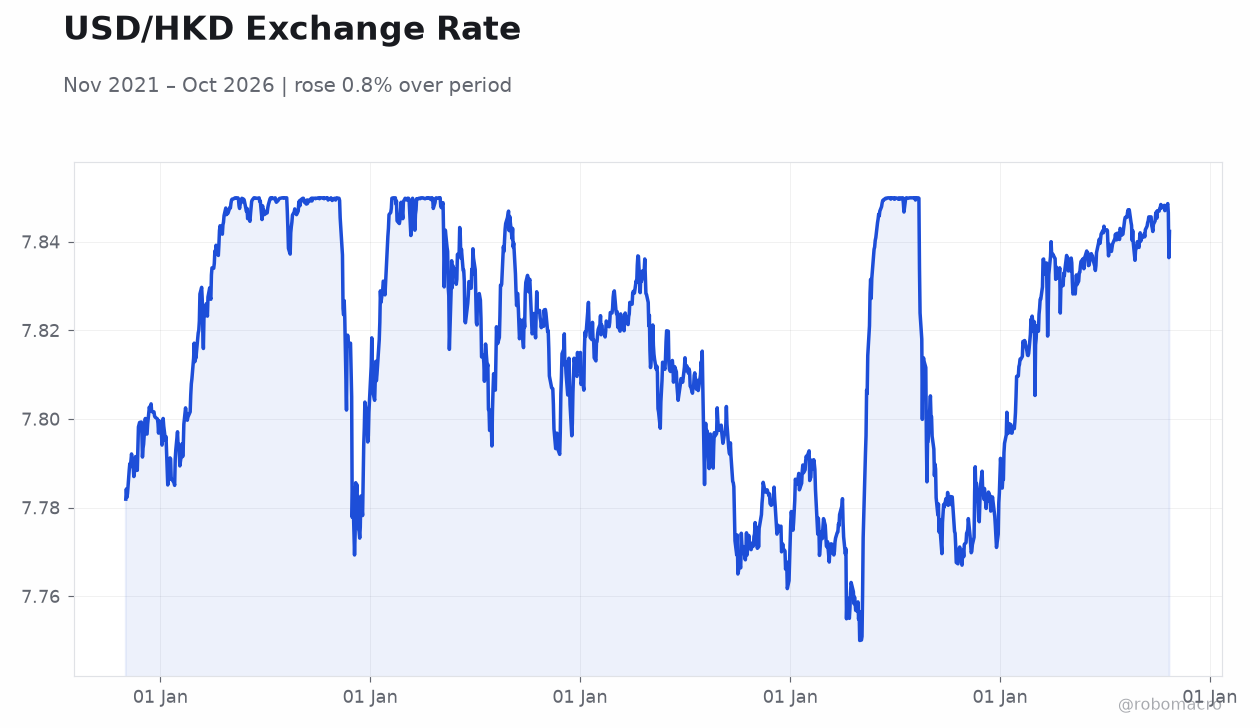
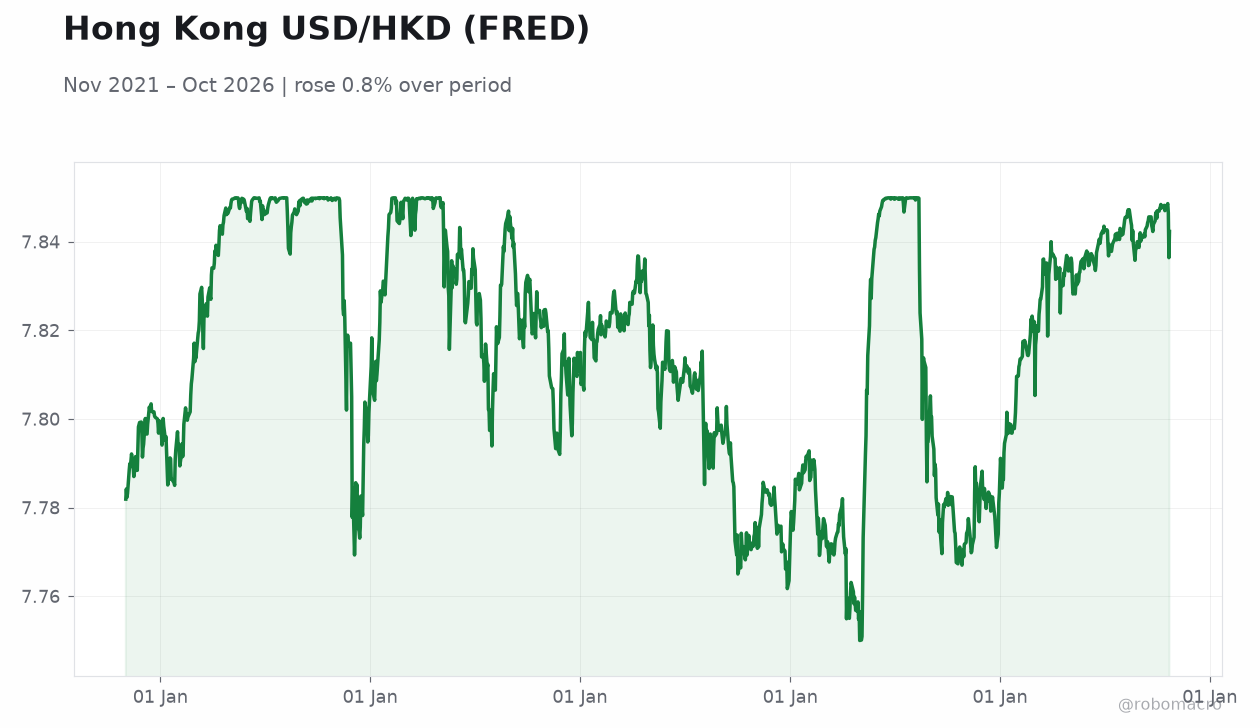
| USD/HKD | 7.84 | -0.02% |
| Copper | 6.48 | -1.50% |
| Brent Crude | 113.43 | -1.26% |
| Gold | 3,898.90 | -3.29% |
| Bitcoin | 77,801.42 | +0.47% |
| China 2Y Govt Yield | - | - |
| China 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| NBS Manufacturing PMI | 50.10 | 50 | 49.30 |
| NBS Non-Manufacturing PMI | 50.20 | 50.50 | 49.70 |
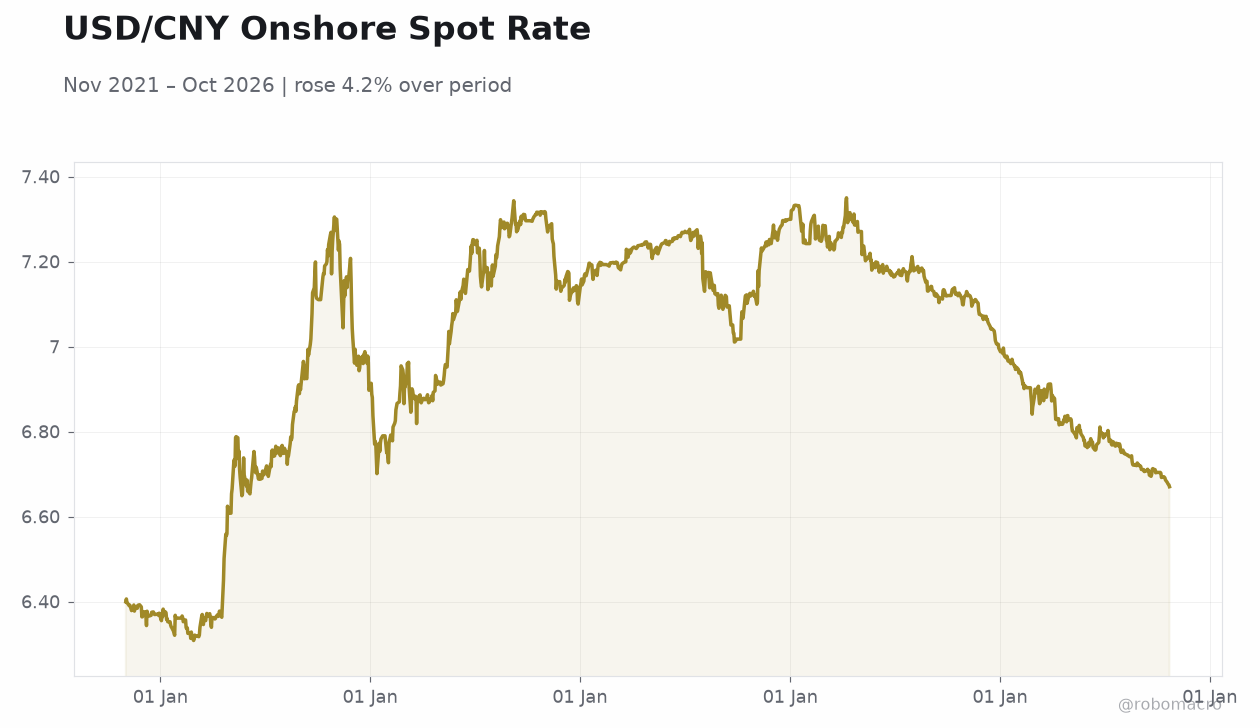 USD/CNY Onshore Spot Rate | Type: macro_line | USD/CNY Onshore Spot Rate: 6.67 (2026-10-23) | Range: 6.308–7.35 | Trend(5pt): 6.399,6.727,7.24,7.177,6.67
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- China's NBS manufacturing PMI fell to 49.3 in October from 50.1, slipping into contraction alongside a non-manufacturing reading of 49.7, undershooting consensus across both gauges.
- Mainland equities sold off on the weak activity data (Shanghai Composite -1.44%, CSI 300 -1.39%) while Hong Kong's Hang Seng bucked the trend with a 1.46% gain; TAIEX plunged 2.49% ahead of TSMC-linked selling.
- Taiwan's Q3 GDP surged 14.36% year-on-year, a 48-year high, powered by AI chip demand — a sharp divergence from the mainland's growth wobble.
Yesterday's Recap
Mainland China's October activity surveys printed decisively weak, with the NBS manufacturing PMI at 49.3 versus consensus of 50.0 and a prior 50.1, while the non-manufacturing gauge fell to 49.7 against expectations of 50.5. The dual sub-50 readings signal broad-based contraction across both factory and services activity, underscoring the fragility of Beijing's recovery push. Mainland equities reacted sharply, with the Shanghai Composite down 1.44% to 3,599.02 and the CSI 300 off 1.39% to 3,985.50.
Hong Kong diverged, with the Hang Seng adding 1.46% to 23,294.42, helped by record quarterly profits at China's mega banks on improved margins and bond-trading gains. Taiwan's TAIEX fell 2.49% to 45,211.83, bracing for TSMC-linked selling after the chipmaker slid in US trading. The yuan strengthened, with USD/CNY at 6.64 (-0.24%), while copper — a key China growth proxy — dropped 1.50% to 6.48, corroborating the soft factory data.
The Day Ahead
The calendar is empty for Greater China on November 1, with no scheduled top-tier releases across the mainland, Hong Kong, or Taiwan. Attention turns to the week ahead, with Hong Kong's financial summit and Indonesia's GDP print flagged as regional highlights. Taiwan's TAIEX reopens November 2 facing heavy selling pressure after TSMC's US-listed shares slid, per Intellinews.
Mainland markets will digest the PMI miss and watch for any policy response from Beijing. With no data to anchor sentiment, flows will likely track global risk appetite and semiconductor headlines.
Other Economic Notes
Taiwan's Q3 GDP growth of 14.36% year-on-year marks a 48-year high, with real private consumption up 5.37% and AI chip demand doing the heavy lifting — growth running roughly four times South Korea's pace. MediaTek is targeting about 20% of the global AI ASIC market, reinforcing Taiwan's centrality to the semiconductor supply chain. On the mainland, China's upgraded free-trade agreement with Peru took effect Sunday, widening ties across e-commerce, supply chains, and competition rules.
China's state-owned oil majors are gaining firepower for Beijing's energy-security push on improved profits, while Audi cut its full-year outlook on a worsening China slump.