Greater China Macro Daily(Beta Mode)
China Services PMI Dips; HK GDP Surges
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| Shanghai Composite | 3,677.14 | -0.25% |
| CSI 300 | 4,113.41 | +0.29% |
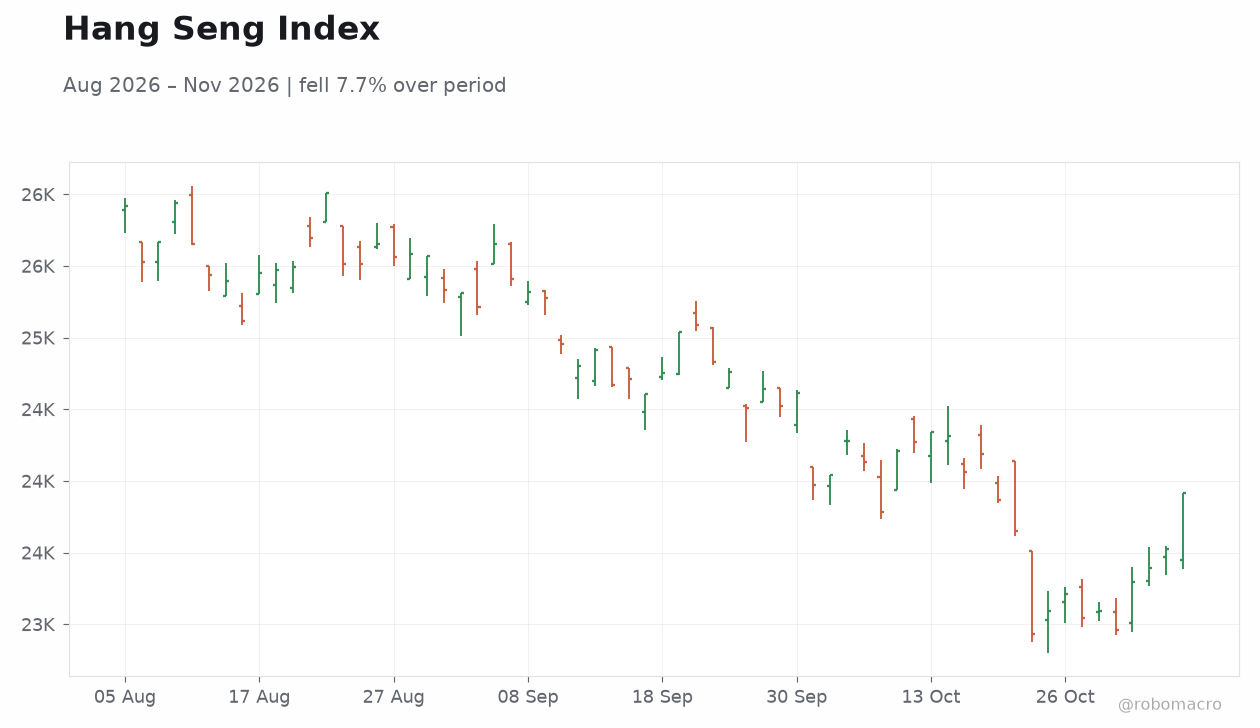
| Hang Seng | 23,919.50 | +1.67% |
| TAIEX | 42,948.91 | -0.83% |
| USD/CNY | 6.67 | -0.04% |
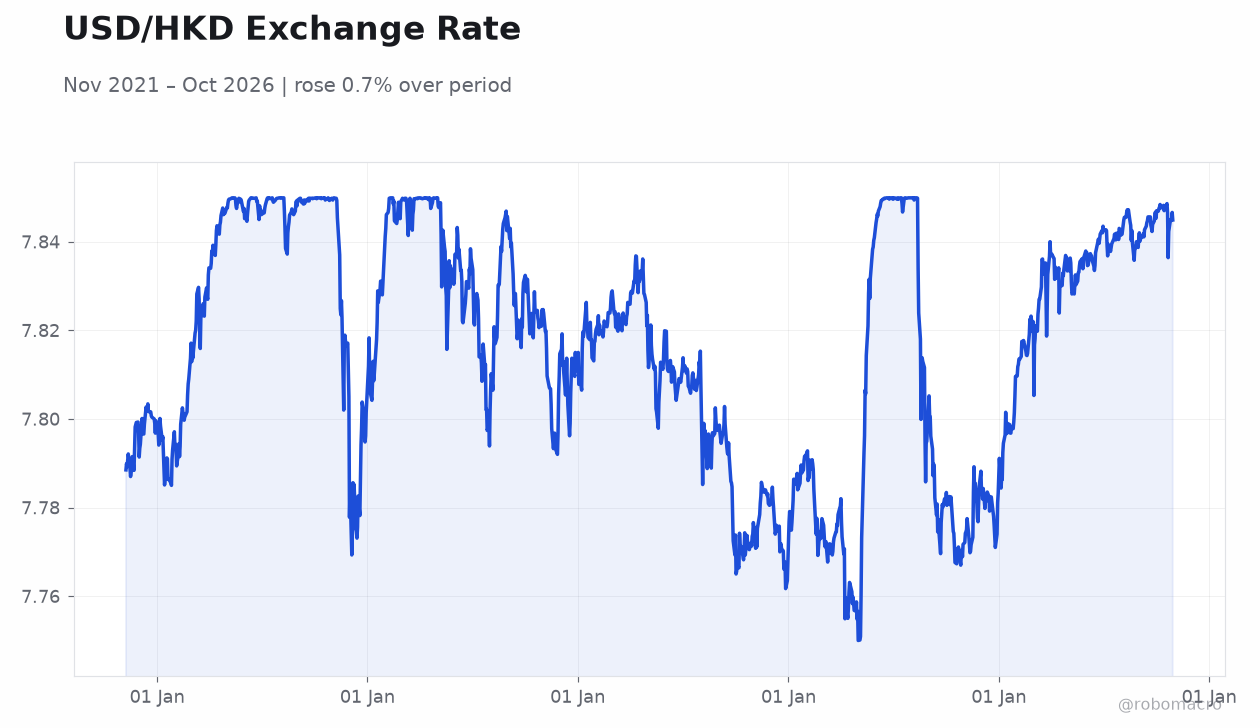
| USD/HKD | 7.84 | -0.07% |
| Copper | 6.20 | -3.12% |
| Brent Crude | 99.10 | +4.73% |
| Gold | 4,097.50 | +0.60% |
| Bitcoin | 75,698.26 | -5.85% |
| China 2Y Govt Yield | - | - |
| China 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| RatingDog Services PMI | 51.60 | 51.50 | 50.80 |
 Imports - Capital Goods | Type: macro_line | Imports - Capital Goods: 2.84e+04 (2026-09-01) | Range: 6444–2.84e+04 | Trend(6pt): 7295,6604,9095,1.692e+04,2.465e+04,2.84e+04
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- China's RatingDog Services PMI unexpectedly fell to 50.8 in November from 51.6, the first slowdown since July, signaling easing business confidence in the mainland services sector.
- Hong Kong GDP grew over 5% in Q3 2026, the strongest pace in five years, with nine-month growth also exceeding 5%, underscoring the SAR's robust recovery momentum.
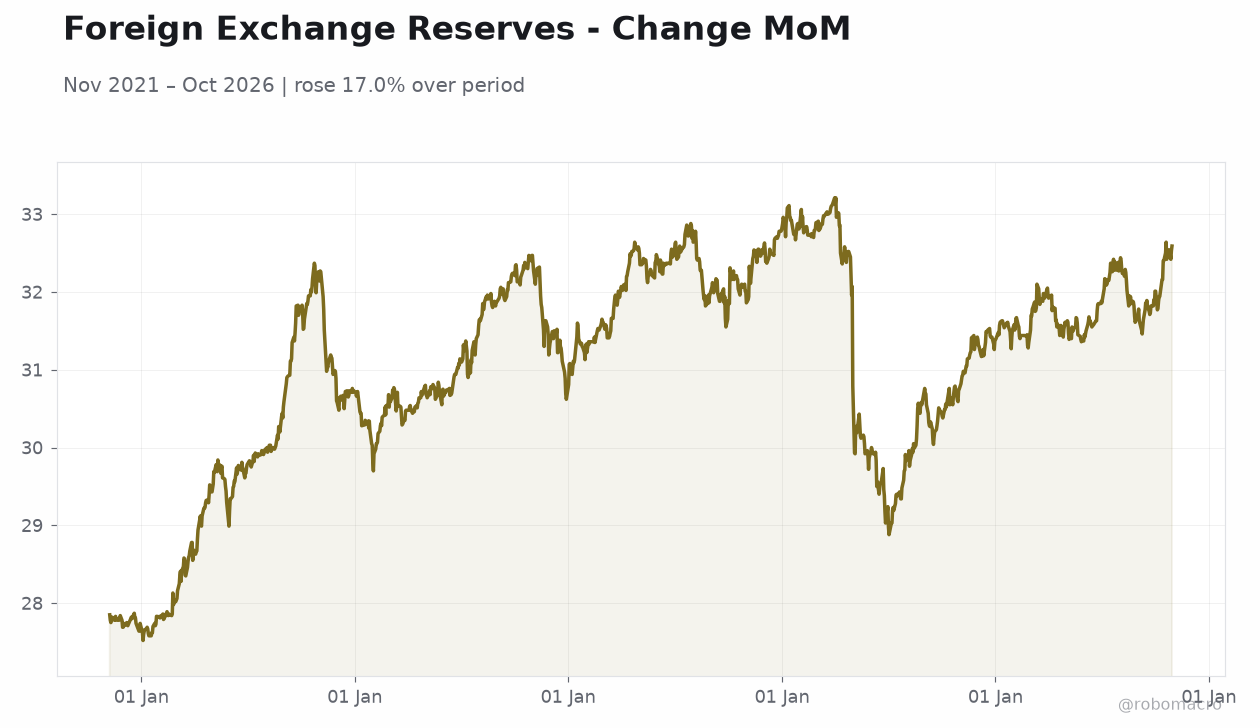
- The PBoC raised the FX reserve requirement ratio to 6%, a move that coincided with modest yuan weakness, while China bank funding costs hit record lows after the central bank shifted to the overnight repo rate as its primary policy tool.
Yesterday's Recap
Mainland China's private services gauge unexpectedly decelerated, with the RatingDog Services PMI printing 50.8 for November versus consensus of 51.5 and the prior 51.6 — the first slowdown since July — as business confidence eased and new order growth moderated. Equity markets diverged: the CSI 300 added 0.29% while the Shanghai Composite slipped 0.25%, reflecting rotation rather than broad risk appetite. Hong Kong was the standout, with the Hang Seng surging 1.67% to 23,919.50 as investors positioned around strong local growth data; Hong Kong GDP rose over 5% in Q3 2026, the strongest in five years, with nine-month growth also above 5%.
Taiwan's TAIEX fell 0.83% to 42,948.91, weighed by semiconductor weakness globally. In FX, USD/CNY edged 0.04% lower to 6.67 and USD/HKD slipped 0.07% to 7.84, both within familiar ranges. Commodities were volatile: copper plunged 3.12% to 6.20 — a cautionary signal on mainland construction and manufacturing demand — while Brent crude jumped 4.73% to 99.10 and gold added 0.60% to 4,097.50.
The Day Ahead
The Greater China calendar is empty for Thursday, November 05, with no scheduled mainland, Hong Kong, or Taiwan releases. Attention therefore shifts to secondary market flows and positioning ahead of Friday's void as well, leaving the region to trade on external cues. Mainland money-market pricing will be closely watched after bank funding costs printed at record lows following the PBoC's shift to the overnight repo rate as its primary policy lever.
Hong Kong interbank rates and the aggregate balance remain in focus given the HKMA's peg mechanics and recent HKD softness. Taiwan investors will track semiconductor supply-chain headlines and any cross-strait trade developments, with the TAIEX's 0.83% decline likely to invite dip-buying scrutiny.
Other Economic Notes
China is considering selling dollar- and offshore-yuan-denominated sovereign bonds as early as this month, alongside a debut yuan bond sale in Canada as bilateral ties warm — a dual signal of funding diversification and yuan internationalization. Beijing extended tariff relief for Canadian canola, lobster, and crab, easing trade friction with Ottawa. ↓ p.2