RoboMacro ResearchAlso todaySee the FX Daily

Greater China Macro Daily(Beta Mode)

November 09, 2026 robomacro.com

China Services PMI Misses; TAIEX Plunges on AI Rout

50.80 RatingDog Services PMI
Shanghai Composite3,649.18-1.10%
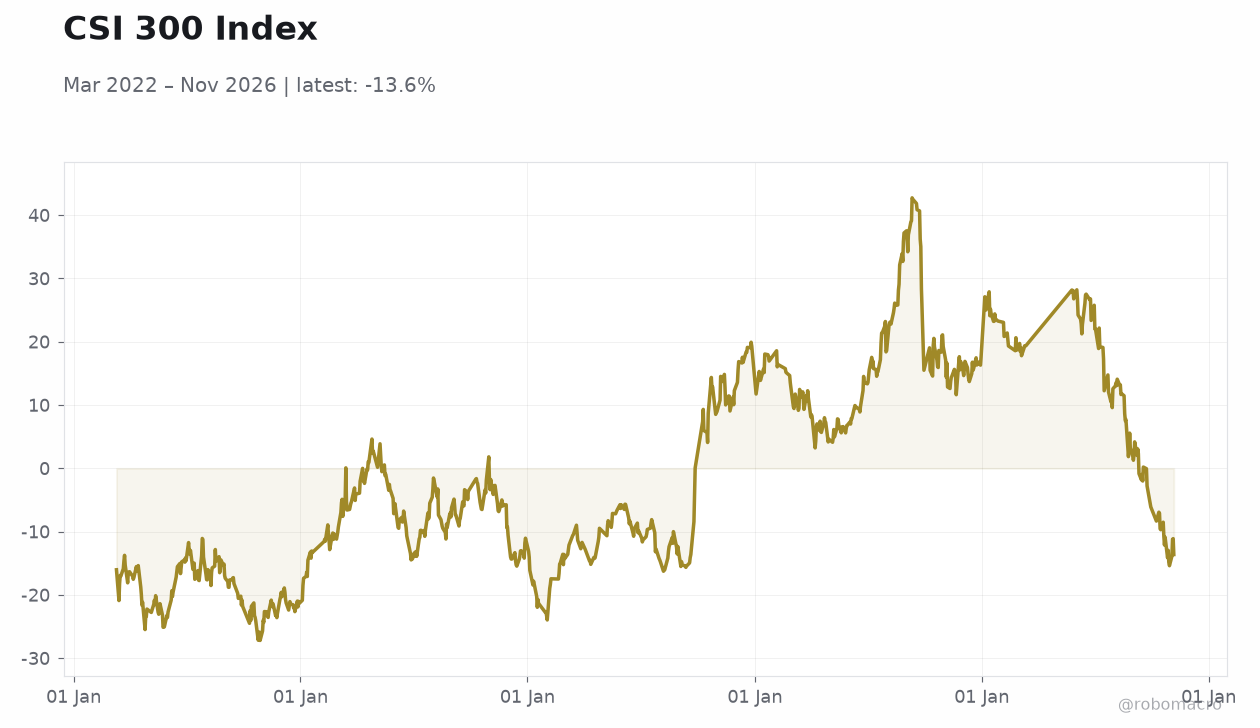
CSI 3004,054.28-1.44%
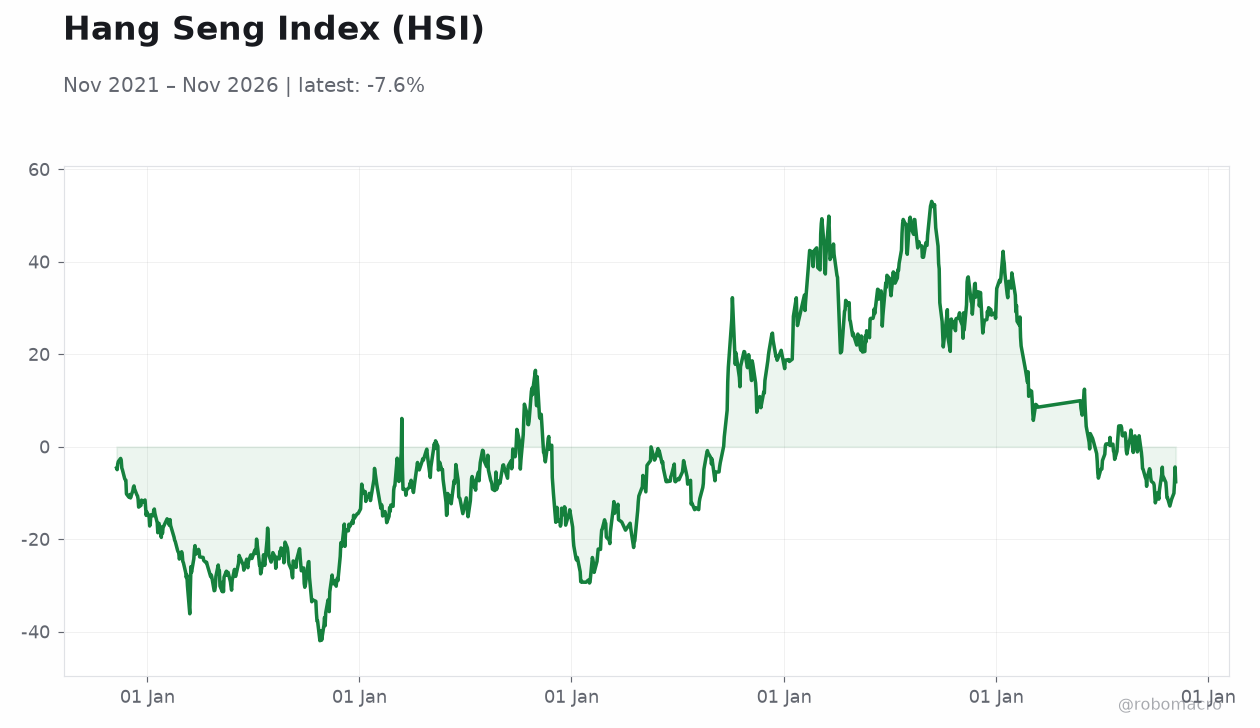
Hang Seng24,481.86-1.27%
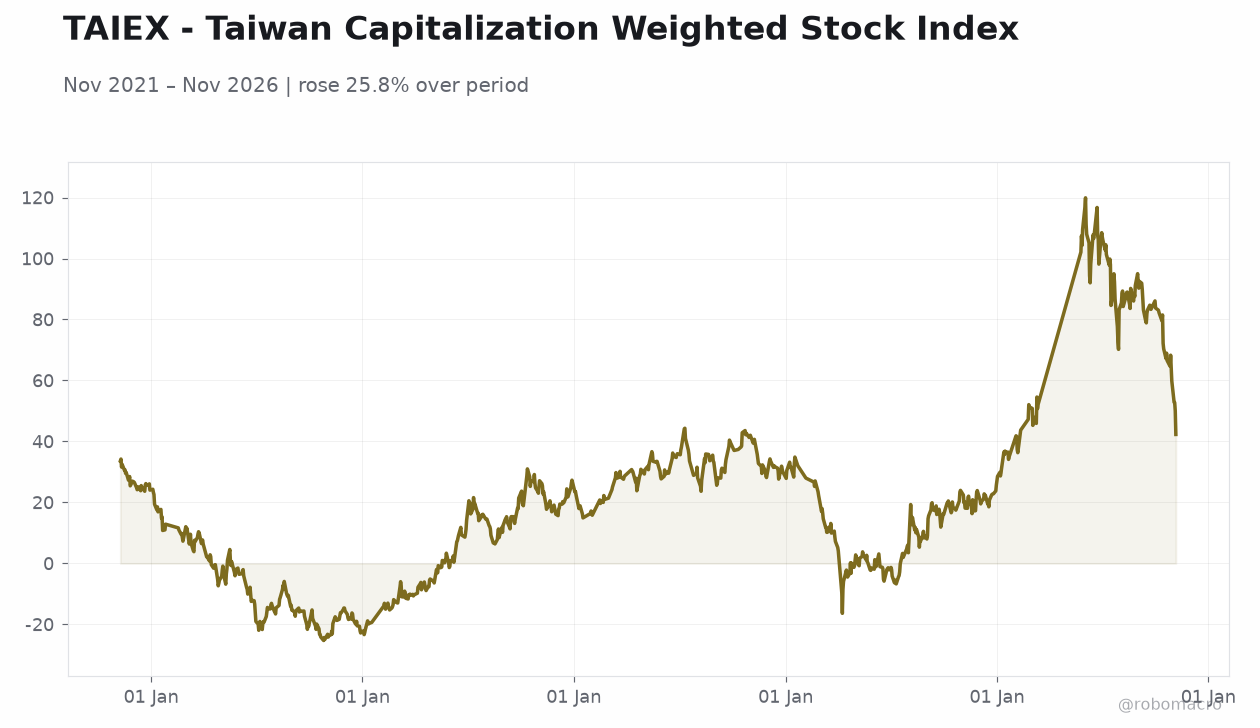
TAIEX39,701.64-4.51%

Market Snapshot

AssetLevelChange
Shanghai Composite3,649.18-1.10%
CSI 3004,054.28-1.44%
Hang Seng24,481.86-1.27%
TAIEX39,701.64-4.51%
USD/CNY6.66-0.35%
USD/HKD7.84+0.01%
Copper6.24-0.18%
Brent Crude98.32+0.03%
Gold4,074.90-0.94%
Bitcoin74,190.66-2.06%
China 2Y Govt Yield--
China 10Y Govt Yield--

Prior Economic Events

Data Prior Cons Actual
RatingDog Services PMI51.6051.5050.80
CSI 300 IndexCSI 300 Index | Type: macro_line | CSI 300 Index: -13.62 (2026-11-06) | Range: -27.2–42.74 | Trend(5pt): -16.02,-3.591,-9.02,21.38,-13.62

Today's Economic Events

Data Prior Cons Time
No events available
  • China's RatingDog Services PMI fell to 50.8 in November from 51.6 prior, missing consensus of 51.5, signaling softening services momentum alongside NDRC's explicit warning on weak domestic demand.
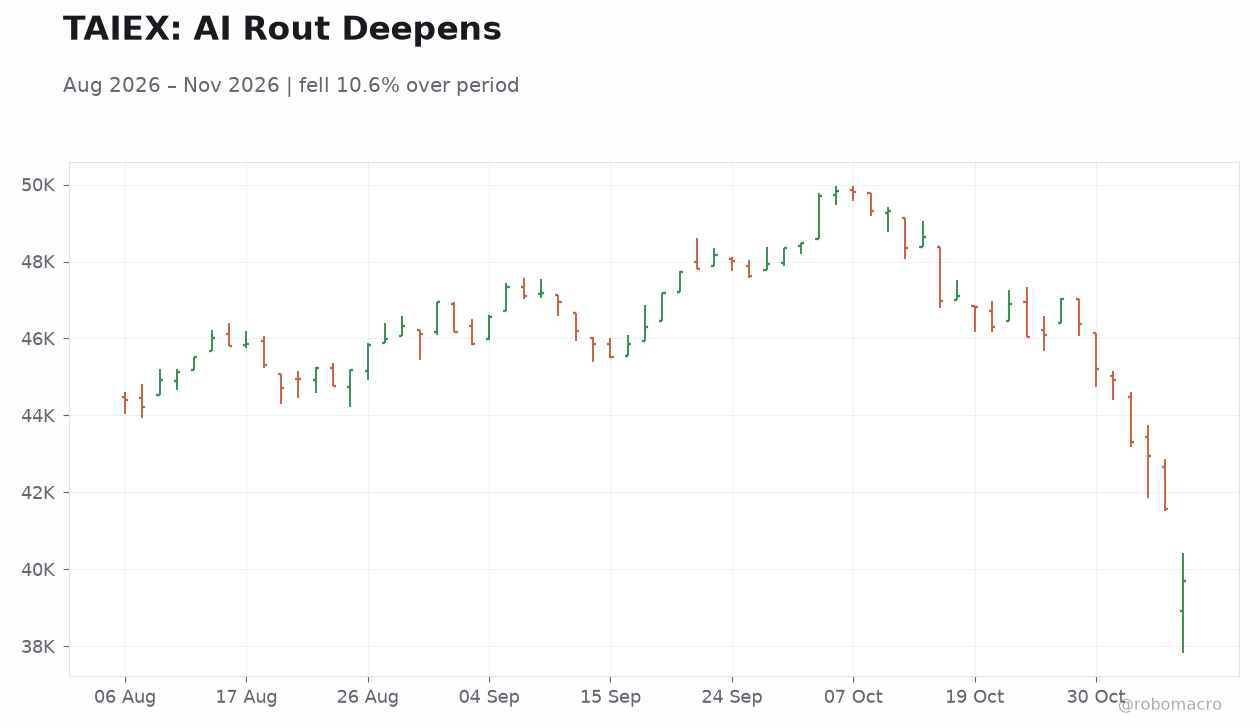
  • Taiwan's TAIEX crashed 4.51% as the global AI-related selloff deepened, prompting authorities to activate market-stabilization measures; BofA flags TWD dips as a buying opportunity.
  • Mainland equities tracked the regional risk-off, with CSI 300 down 1.44% and Hang Seng off 1.27%, while USD/CNY slipped 0.35% to 6.66 despite the broader dollar bid.

Yesterday's Recap

Mainland China's November RatingDog Services PMI printed at 50.8, down from 51.6 in October and below the 51.5 consensus, a clear deceleration in services activity that reinforces the demand-side weakness flagged by the NDRC this week. The reading lands alongside China's CPI at 0.90% YoY as of September, keeping the disinflation narrative intact and preserving room for further PBoC easing. Equity markets across Greater China sold off sharply: the CSI 300 fell 1.44% to 4,054.28 and the Shanghai Composite dropped 1.10% to 3,649.18, while Hong Kong's Hang Seng declined 1.27% to 24,481.86.

Taiwan was the epicenter of the risk-off, with the TAIEX plunging 4.51% to 39,701.64 as the global AI-related rout hit semiconductor-heavy names hardest; Taipei responded by activating market-stabilization measures, joining South Korea in attempting to stem the bleeding. FX markets diverged: USD/CNY fell 0.35% to 6.66, reflecting a firmer yuan fix and possible smoothing, while USD/HKD held essentially flat at 7.84, comfortably within the peg band. Commodity proxies were mixed, with copper down 0.18% at 6.24 and Brent crude marginally higher at 98.32, while gold slipped 0.94% to 4,074.90.

The Day Ahead

The Greater China calendar is empty for the next two sessions, with no tier-one releases scheduled for Monday, November 9. Attention will therefore rotate to secondary indicators and policy signaling, particularly any PBoC open-market operations and the daily yuan fixing, which will be scrutinized for signs of tolerance toward recent CNY strength. Hong Kong's HKMA has two RMB sovereign bond tenders slated for November 12 — a 3-year and a 10-year RMB government bond issue — which will be watched for demand signals and CNH curve pricing.

Taiwan markets will reopen after the stabilization measures, with investors focused on whether the AI-linked selloff extends or stabilizes and on any further FSC/TWSE intervention. Mainland credit and property data remain the key swing factors into mid-month, and NDRC commentary on next-year policy measures will be parsed for stimulus intent.

Page 1

Greater China Macro Daily(Beta Mode)

November 09, 2026 robomacro.com
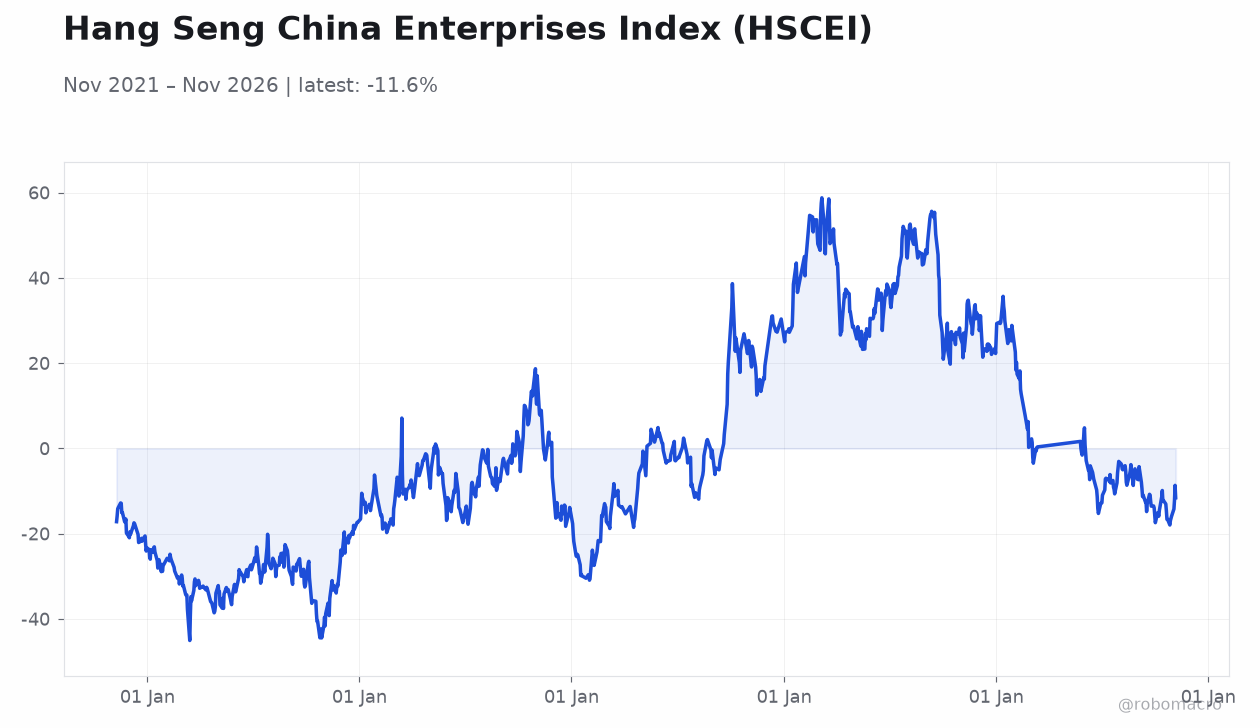
Hang Seng China Enterprises Index (HSCEI) Hang Seng China Enterprises Index (HSCEI) | Type: macro_line | Hang Seng China Enterprises Index (HSCEI): -11.56 (2026-11-06) | Range: -45.05–58.79 | Trend(5pt): -17.18,-19.53,-24.25,40.29,-11.56
Hang Seng Index (HSI) Hang Seng Index (HSI) | Type: macro_line | Hang Seng Index (HSI): -7.566 (2026-11-06) | Range: -41.97–53.06 | Trend(5pt): -4.624,-16.05,-24.79,38.3,-7.566
TAIEX - Taiwan Capitalization Weighted Stock Index TAIEX - Taiwan Capitalization Weighted Stock Index | Type: macro_line | TAIEX - Taiwan Capitalization Weighted Stock Index: 42.3 (2026-11-06) | Range: -25.27–119.9 | Trend(5pt): 33.62,-18.31,15.8,-5.745,42.3
TAIEX: AI Rout Deepens TAIEX: AI Rout Deepens | Type: market_hloc | TAIEX Index: 3.97e+04 (2026-11-06) | Range: 3.97e+04–4.982e+04 | Trend(6pt): 4.44e+04,4.598e+04,4.629e+04,4.834e+04,4.157e+04,3.97e+04

Other Economic Notes

The NDRC's explicit acknowledgment of weak demand as a challenge marks a notable shift in official tone, suggesting next year's policy package may lean more heavily on consumption support rather than supply-side tools. China's push to expand yuan usage in Africa continues to gain traction, part of a broader strategy to deepen trade and financial linkages and reduce dollar dependence in commodity settlement. The EU Chamber of Commerce in China highlighted persistent trade tensions with Brussels, a reminder that external demand faces headwinds even as domestic stimulus is calibrated.

Hong Kong's SME credit sentiment improved modestly in Q3 per the HKMA survey, though the success rate for new loan applications fell to 78%, pointing to tighter credit conditions despite easier sentiment. China's state refiners are expected to trim diesel exports this month on tight inventories, a signal of domestic demand resilience in the industrial chain.

Global Macro News

The dominant global theme is the sharp AI-related equity selloff, which has cascaded through Asian markets and forced stabilization action in Taiwan and South Korea. US Treasury Secretary Bessent and USTR Greer raised concerns with Vice Premier He Lifeng over China's compliance with the trade deal, reintroducing a geopolitical risk premium into the bilateral relationship. BofA's Asia FX strategy desk recommends buying dips in the Korean won and Taiwan dollar, arguing the AI-driven weakness has created an opportunity rather than a structural break.

↓ p.3

Sponsored by Arbitrage Search
Page 2

Greater China Macro Daily(Beta Mode)

November 09, 2026 robomacro.com

Continuation

Global Macro News (continued)

The Korean won surged past 1,357 per dollar amid an AI-regulation shock that triggered a KOSPI circuit breaker, illustrating how policy-driven volatility is transmitting across the region. OCBC expects US Treasury yields to settle at lower levels following the recent bond rally, a backdrop that could ease pressure on PBOC rate differentials. The ringgit closed lower amid the semiconductor selloff, confirming that the AI trade unwinding is a regional, not purely Taiwan-specific, phenomenon.

Greater China Central Banks Watch

The PBoC set the dollar-yuan reference rate at 6.7168, a firmer fix than the 6.66 spot level, suggesting a continued preference for stability and possibly a bias toward allowing modest CNY appreciation. With CPI at 0.90% YoY and services PMI softening to 50.8, the case for further modest easing remains intact, though the PBoC has shown reluctance to move aggressively while managing yuan stability. Liquidity operations will be the near-term tell, with any uptick in open-market injections signaling a dovish tilt ahead of year-end.

The HKMA faces no immediate peg pressure, with USD/HKD at 7.84 well inside the 7.75–7.85 band and the aggregate balance stable; the November 12 RMB bond tenders will be a useful gauge of CNH demand. Taiwan's CBC is on hold for now, but the TAIEX's 4.51% plunge and the activation of market-stabilization measures put FX intervention and semiconductor export outlook squarely back on the radar. The CBC will be watching whether the AI selloff proves transient or structural, as that determines both the export trajectory and the appropriate policy stance.

Sponsored by Arbitrage Search
Page 3