RoboMacro ResearchAlso todaySee the FX Daily

Greater China Macro Daily(Beta Mode)

November 10, 2026 robomacro.com

China Trade Data Eyed; AI Rout Hits TAIEX

Shanghai Composite3,649.18-1.10%
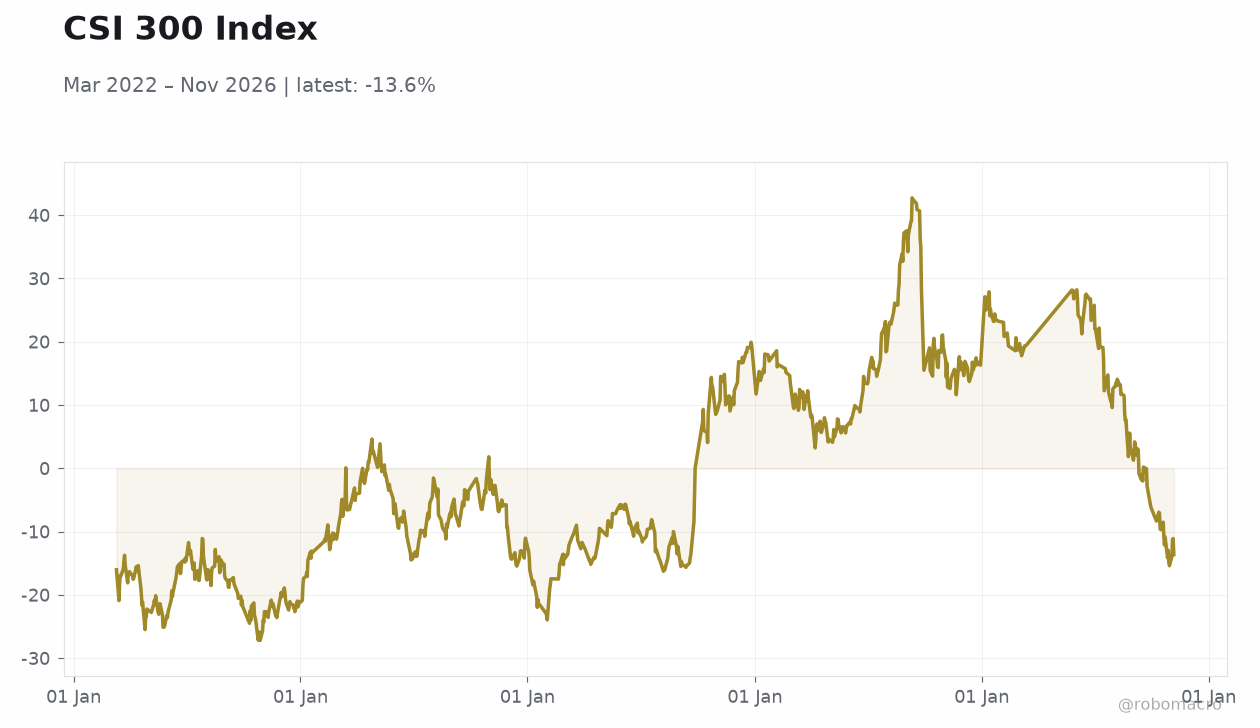
CSI 3004,054.28-1.44%
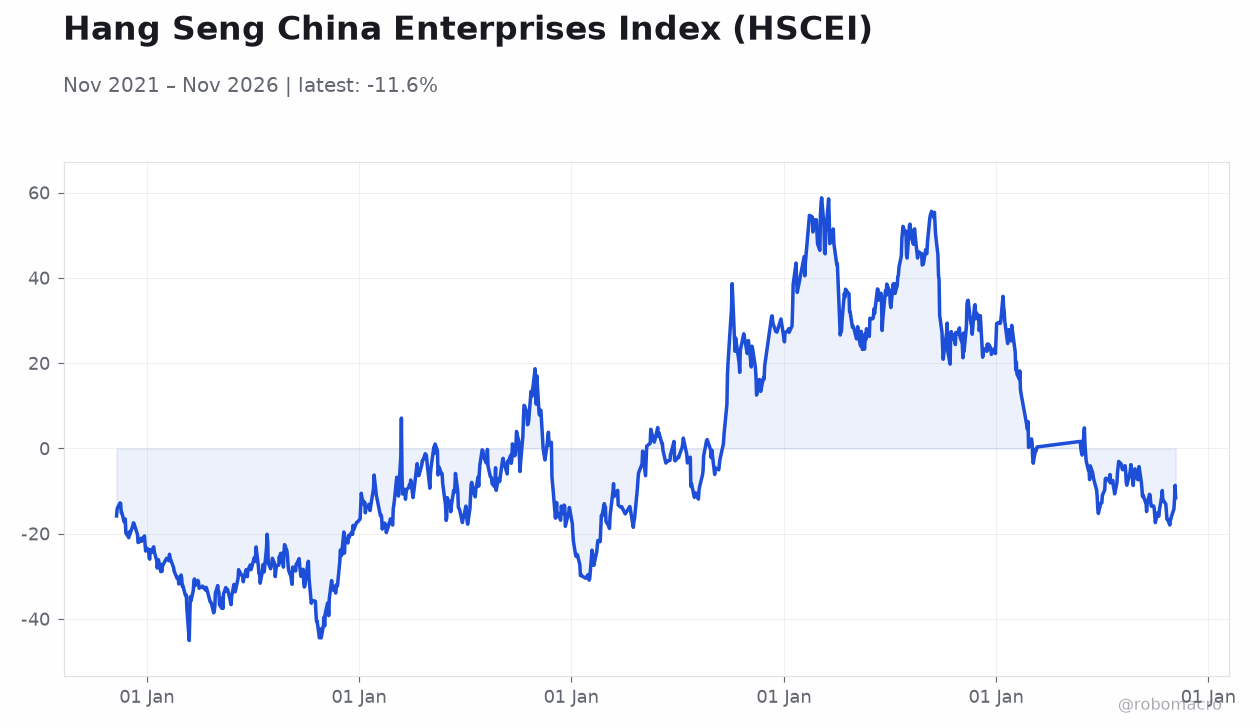
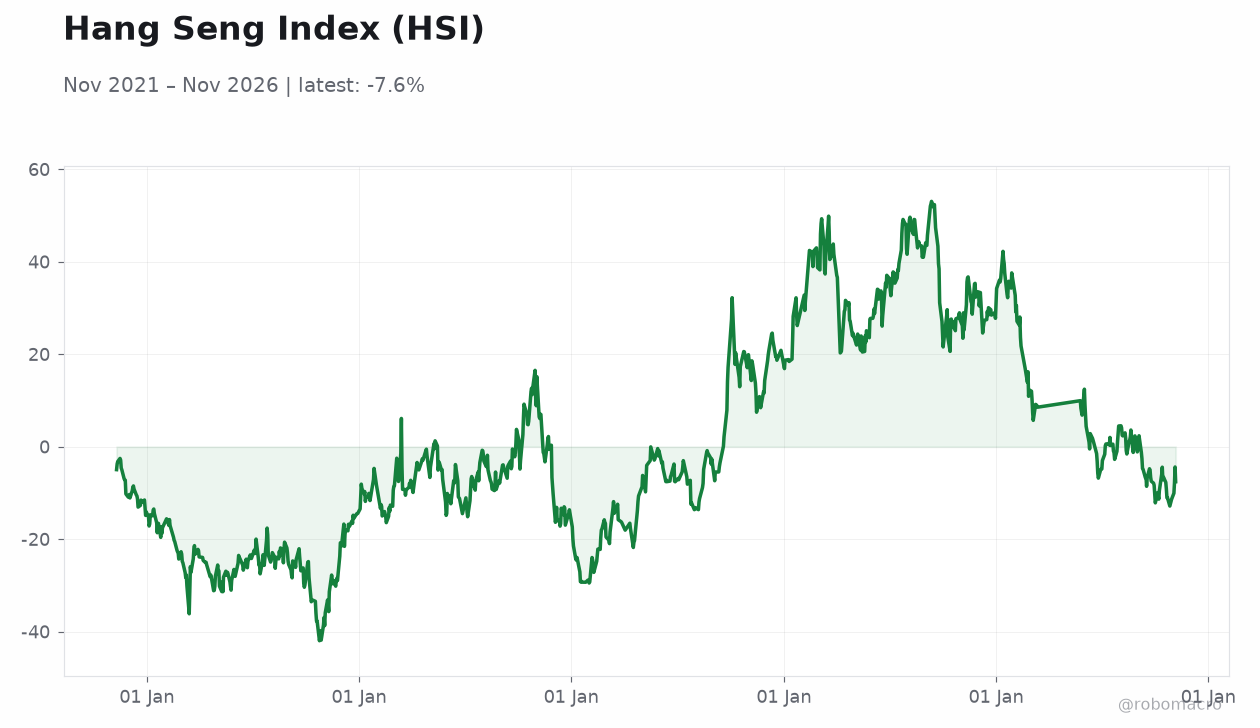
Hang Seng24,481.86-1.27%
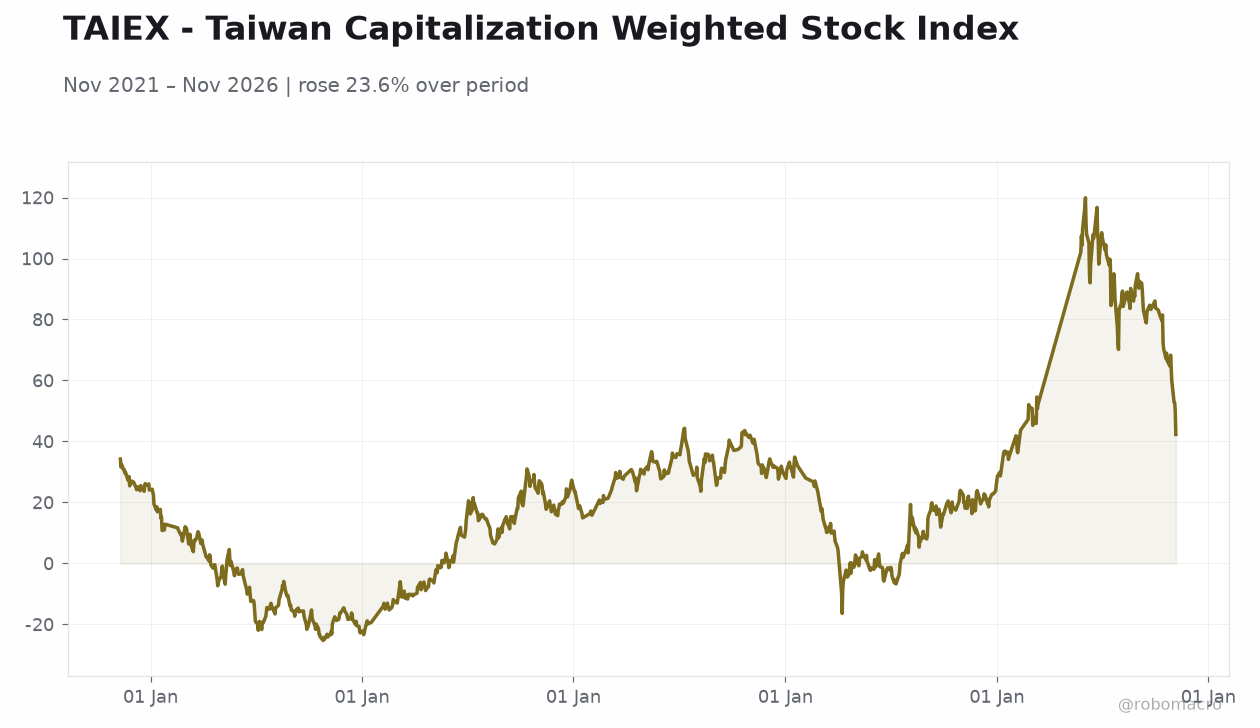
TAIEX39,701.64-4.51%

Market Snapshot

AssetLevelChange
Shanghai Composite3,649.18-1.10%
CSI 3004,054.28-1.44%
Hang Seng24,481.86-1.27%
TAIEX39,701.64-4.51%
USD/CNY6.67-0.23%
USD/HKD7.84+0.04%
Copper6.38+2.57%
Brent Crude92.14-6.29%
Gold4,151.00+1.87%
Bitcoin74,925.96+0.46%
China 2Y Govt Yield--
China 10Y Govt Yield--

Prior Economic Events

Data Prior Cons Actual
No events available
CSI 300 IndexCSI 300 Index | Type: macro_line | CSI 300 Index: -13.62 (2026-11-06) | Range: -27.2–42.74 | Trend(5pt): -16.02,-3.591,-9.02,21.38,-13.62

Today's Economic Events

Data Prior Cons Time
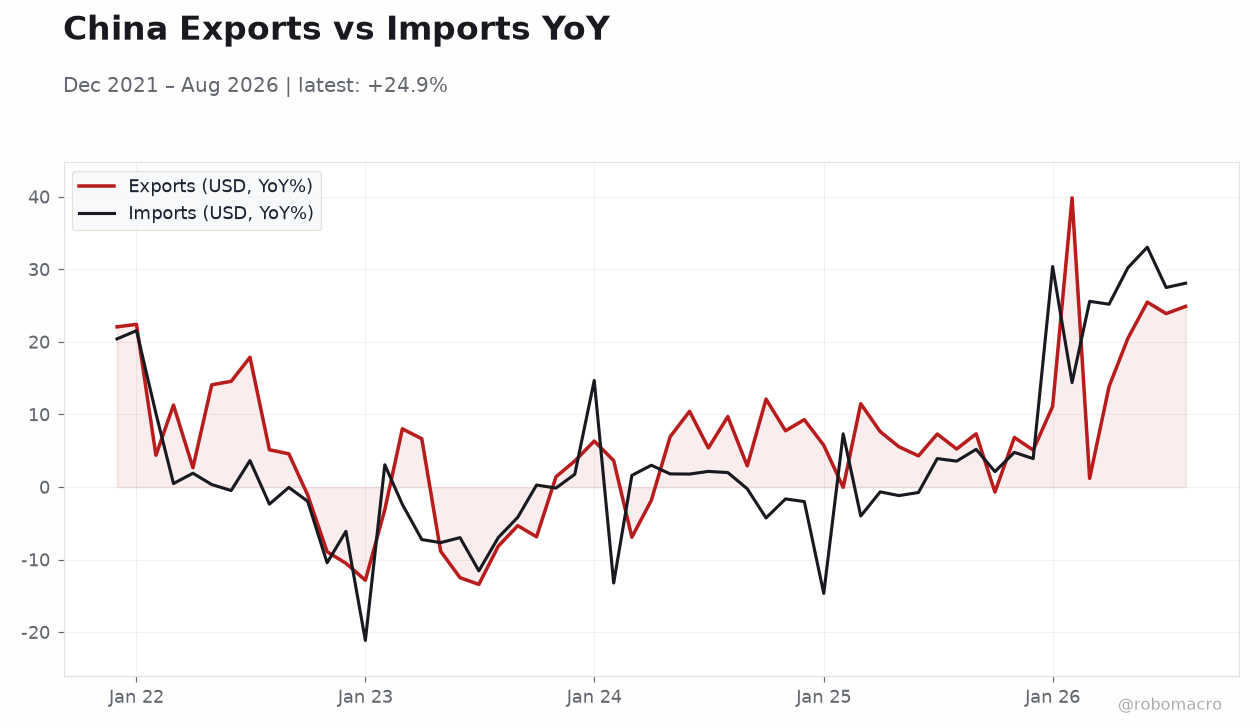
Exports Year-over-Year36.30-22:00
Imports Year-over-Year31-22:00
Trade Balance133,530m126,500m22:00
  • China releases October trade data tonight (22:00 ET); exports previously +36.3% YoY, imports +31%, with consensus trade surplus of $126.5bn versus $133.5bn prior.
  • Taiwan's TAIEX plunged 4.51% amid a global AI-related selloff, prompting authorities to activate market-stabilization measures.
  • China extended suspension of its 24% retaliatory tariff on US goods and special port fees on US-linked ships, easing trade tensions; NDRC flags weak demand as a key economic challenge.

Yesterday's Recap

Greater China markets sold off sharply on Monday, led by Taiwan, where the TAIEX collapsed 4.51% to 39,701.64 as a global rout in artificial-intelligence-related shares deepened — the island's benchmark suffered its worst session in recent memory, forcing authorities to activate market-stabilization measures and join South Korea in attempting to calm investors. Mainland China equities also weakened, with the Shanghai Composite falling 1.10% to 3,649.18 and the CSI 300 dropping 1.44% to 4,054.28, while Hong Kong's Hang Seng declined 1.27% to 24,481.86. On the macro side, China's NDRC publicly flagged weak demand as a challenge for the economy as policymakers study measures for next year, and producer prices reportedly hit a four-year high even as weak domestic demand weighs on activity.

In FX, the yuan strengthened, with USD/CNY down 0.23% to 6.67, while the PBoC set the daily dollar-yuan fixing at 6.7168. The HKMA reported a slight improvement in SME credit conditions for Q3 2026, though the success rate for new loan applications fell to 78%. Commodities diverged sharply: copper, a key China growth proxy, jumped 2.57% to 6.38, gold rose 1.87% to 4,151, while Brent crude plunged 6.29% to 92.14.

The Day Ahead

The dominant event is China's October trade release, scheduled for 22:00 ET tonight, covering exports, imports, and the trade balance. Exports are coming off a strong 36.3% YoY prior reading and imports off 31%, with consensus looking for a trade surplus of $126.5bn versus the prior $133.5bn. These figures will be scrutinized for signs of whether external demand is holding up amid the global AI-driven equity turbulence and lingering US-China trade friction.

No major Hong Kong or Taiwan data releases are scheduled for Tuesday, so attention will center on whether Taiwan's stabilization measures succeed in arresting the AI-linked selloff and on follow-through in mainland equities after Monday's decline. Markets will also watch for any PBoC liquidity operations or signals on next-year policy support following the NDRC's weak-demand commentary.

Other Economic Notes

China's cross-border yuan payment system is heading for its busiest year since its 2015 launch, driven by robust trade and greater international use of the currency — a structural theme reinforced by Beijing's push to expand yuan usage in Africa for trade and financial influence. ↓ p.2
Page 1

Greater China Macro Daily(Beta Mode)

November 10, 2026 robomacro.com
Hang Seng China Enterprises Index (HSCEI) Hang Seng China Enterprises Index (HSCEI) | Type: macro_line | Hang Seng China Enterprises Index (HSCEI): -11.56 (2026-11-06) | Range: -45.05–58.79 | Trend(5pt): -15.83,-20.16,-22.9,40.58,-11.56
Hang Seng Index (HSI) Hang Seng Index (HSI) | Type: macro_line | Hang Seng Index (HSI): -7.566 (2026-11-06) | Range: -41.97–53.06 | Trend(5pt): -4.963,-16.59,-23.39,38.1,-7.566
TAIEX - Taiwan Capitalization Weighted Stock Index TAIEX - Taiwan Capitalization Weighted Stock Index | Type: macro_line | TAIEX - Taiwan Capitalization Weighted Stock Index: 42.3 (2026-11-06) | Range: -25.27–119.9 | Trend(5pt): 34.23,-19.8,20.81,-5.473,42.3
China Exports vs Imports YoY China Exports vs Imports YoY | Type: macro_line | Exports (USD, YoY%): 24.9 (2026-08-01) | Range: -13.41–39.85 | Trend(5pt): 22.08,-3.12,-1.835,4.3,24.9 | Imports (USD, YoY%): 28.09 (2026-08-01) | Range: -21.14–33.05 | Trend(5pt): 20.42,3.068,3.005,-0.7467,28.09

Other Economic Notes (continued)

The NDRC's explicit acknowledgment of weak demand as an economic challenge signals that next year's policy package may lean toward demand-support measures, though details remain scarce. Producer prices at a four-year high, driven partly by energy costs, contrast with soft consumer inflation — verified CPI stood at 0.50% YoY as of end-October — highlighting the margin squeeze facing Chinese manufacturers. In Hong Kong, the HKMA's SME survey showing improved sentiment but a lower new-loan success rate (78%) points to cautious bank lending even as credit conditions ease modestly.

Taiwan's equity volatility, meanwhile, underscores its deep sensitivity to the global semiconductor and AI supply chain.

Global Macro News

A broad global selloff in artificial-intelligence-related equities is the dominant cross-market force, hammering Taiwan and Korean tech shares and spilling into Greater China markets. Taiwan and South Korea have both moved to stem the bleeding in local equities, an unusual coordinated stabilization effort in Asia. BofA's Asia FX strategy team sees the AI-driven weakness in the Korean won and Taiwan dollar as a buying opportunity, recommending long positions on dips.

In rates, OCBC expects US Treasury yields to settle at lower levels following the recent bond rally, a backdrop that could ease pressure on Asian currencies and the HKMA's peg mechanics. China's extension of its 24% tariff suspension on US goods and suspension of special port fees on US-linked ships removes a near-term escalation risk in US-China trade. The EU Chamber of Commerce in China continues to engage on trade tensions between Brussels and Beijing.

↓ p.3

Sponsored by Arbitrage Search
Page 2

Greater China Macro Daily(Beta Mode)

November 10, 2026 robomacro.com

Continuation

Global Macro News (continued)

Brent crude's 6.29% plunge and gold's 1.87% rally reflect a risk-off rotation with deflationary commodity undertones.

Greater China Central Banks Watch

The PBoC set the dollar-yuan reference rate at 6.7168, with USD/CNY trading stronger at 6.67, indicating the central bank is tolerating modest yuan appreciation. No MLF or LPR decision is scheduled today, but the NDRC's weak-demand warning raises expectations that the PBoC may lean toward further liquidity support or a reserve-requirement adjustment to bolster next-year growth. The HKMA, operating the USD/HKD peg within its 7.75–7.85 band, saw the pair at 7.84 with a marginal 0.04% rise; the authority announced tenders for 3-year and 10-year RMB government bonds on November 12, continuing its role in deepening Hong Kong's offshore yuan market.

The HKMA also launched a post-quantum cryptography toolkit with HKUST to accelerate banking-sector transition by 2030. Taiwan's CBC has not issued a fresh rate decision, but its market-stabilization posture amid the AI rout and BofA's constructive TWD view suggest the central bank will monitor FX volatility closely, particularly given the semiconductor export outlook that anchors Taiwan's economy.

Sponsored by Arbitrage Search
Page 3