RoboMacro ResearchAlso todaySee the Commodities Daily

Greater China Macro Daily(Beta Mode)

November 11, 2026 robomacro.com

China Exports Beat, Imports Surge; TAIEX Jumps

35.20 Exports Year-over-Year41.60 Imports Year-over-Year105,280m Trade Balance
Shanghai Composite3,666.87+0.17%
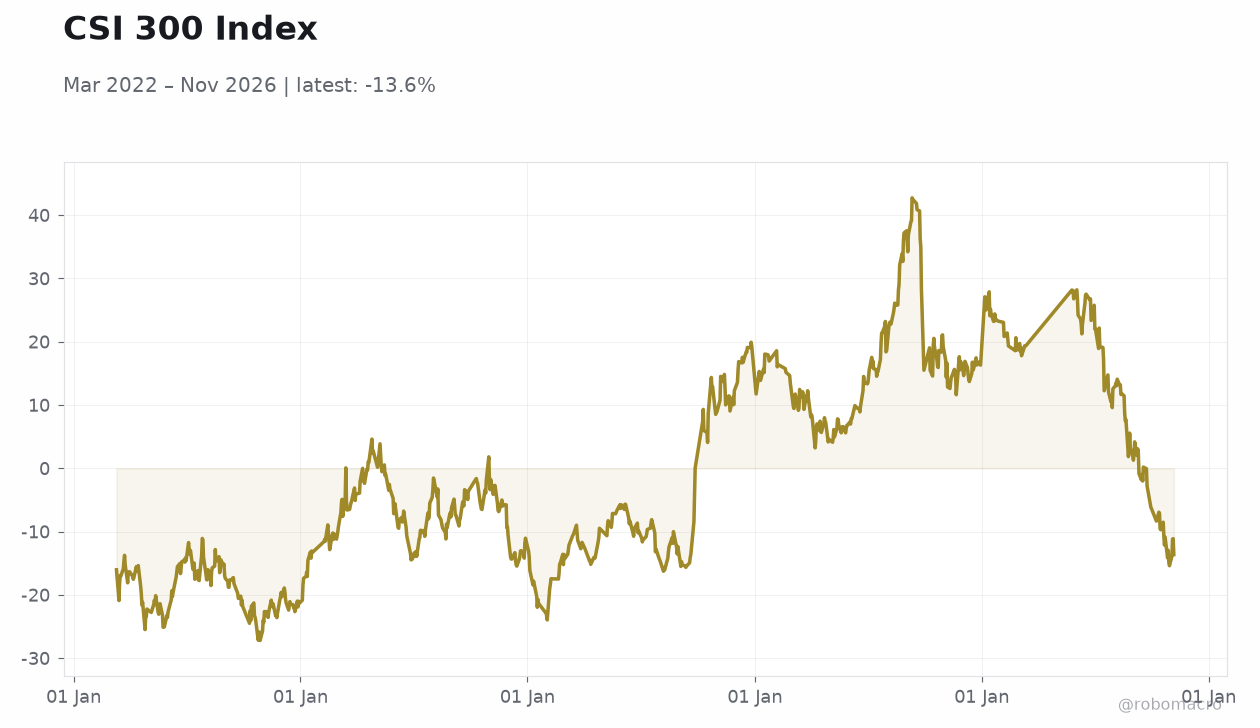
CSI 3004,059.11+0.12%
Hang Seng24,448.95-0.13%
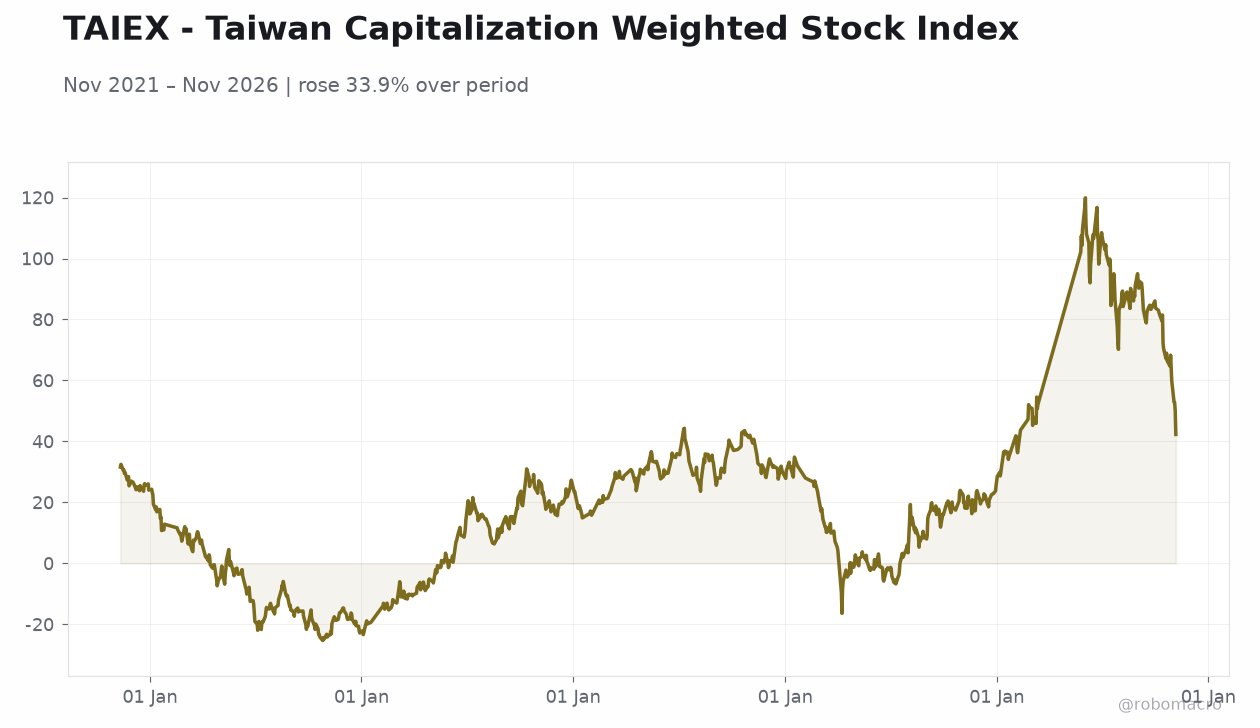
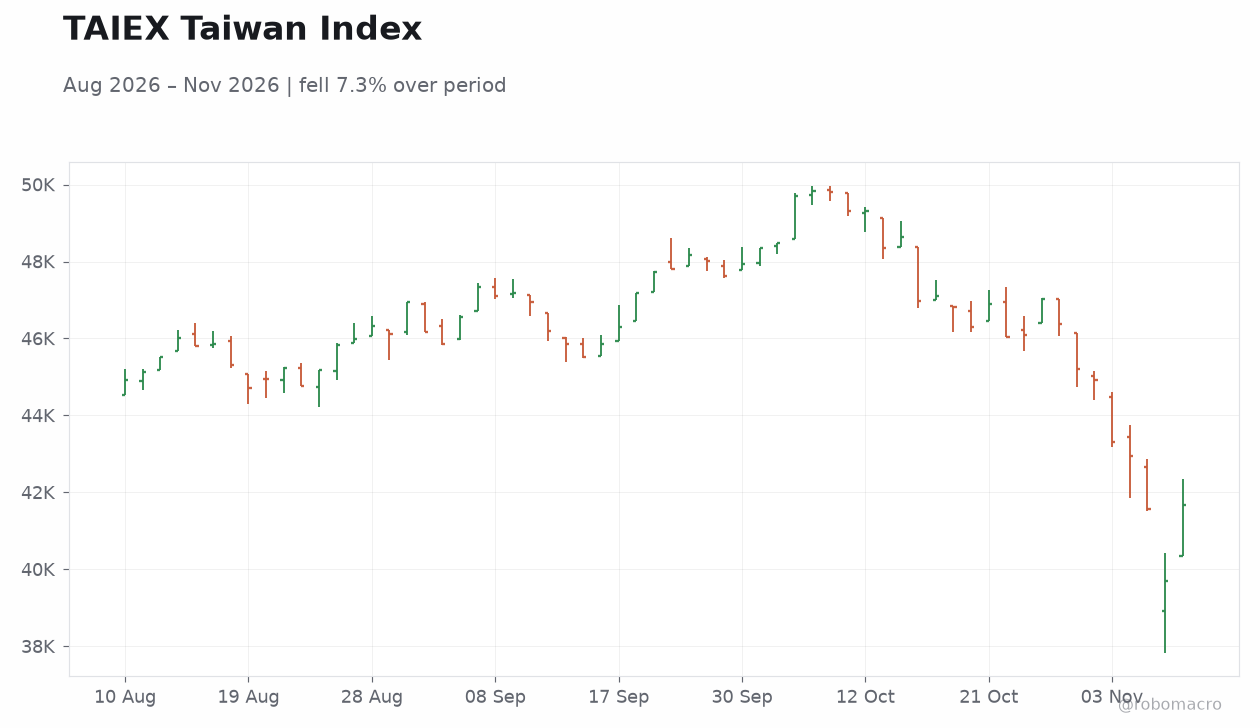
TAIEX41,661.70+4.94%

Market Snapshot

AssetLevelChange
Shanghai Composite3,666.87+0.17%
CSI 3004,059.11+0.12%
Hang Seng24,448.95-0.13%
TAIEX41,661.70+4.94%
USD/CNY6.67-0.09%
USD/HKD7.85+0.08%
Copper6.28-0.85%
Brent Crude91.99-0.63%
Gold4,039.20-1.83%
Bitcoin73,773.99-1.93%
China 2Y Govt Yield--
China 10Y Govt Yield--

Prior Economic Events

Data Prior Cons Actual
Exports Year-over-Year36.3033.5035.20
Imports Year-over-Year313241.60
Trade Balance133,530m125,800m105,280m
Exports Year-over-Year36.3033.50-
Imports Year-over-Year3132-
Trade Balance133,530m125,800m-
CSI 300 IndexCSI 300 Index | Type: macro_line | CSI 300 Index: -13.62 (2026-11-06) | Range: -27.2–42.74 | Trend(5pt): -16.02,-3.591,-9.02,21.38,-13.62

Today's Economic Events

Data Prior Cons Time
No events available
  • China October exports rose 35.2% YoY, beating consensus of 33.5%, while imports surged 41.6% versus 32% expected, pushing the trade surplus to $105.28bn.
  • Taiwan's TAIEX jumped 4.94% to 41,661.70, leading regional gains, while mainland benchmarks edged higher and the Hang Seng slipped 0.13%.
  • China extended its suspension of the 24% additional tariff on US goods and special port fees on US-linked ships, keeping trade tensions in a holding pattern ahead of a possible Trump-Xi-Putin summit.

Yesterday's Recap

China's October trade data dominated the session, with exports rising 35.2% YoY against a 33.5% consensus and imports surging 41.6% versus 32% expected — a striking import acceleration that suggests either stronger domestic absorption or front-loading ahead of tariff deadlines. The trade surplus narrowed to $105.28bn from $133.53bn previously, below the $125.8bn consensus, as import growth outpaced exports. Mainland equities were muted in response: the Shanghai Composite added 0.17% to 3,666.87 and the CSI 300 gained 0.12% to 4,059.11, with state-led "National Team" ETF buying reportedly hitting a record high last week to stem a bruising selloff.

Hong Kong's Hang Seng slipped 0.13% to 24,448.95, while Taiwan's TAIEX surged 4.94% to 41,661.70 — a standout move likely tied to semiconductor sentiment despite lingering doubts over Nvidia's CEO. The yuan firmed modestly, with USD/CNY at 6.67 (-0.09%), while USD/HKD held at the 7.85 weak-side peg convertibility level (+0.08%). Commodities flagged caution on China demand: copper fell 0.85% to 6.28, Brent eased 0.63% to $91.99, and gold dropped 1.83% to $4,039.20.

The Day Ahead

No Greater China macro releases are scheduled for today (November 10) or tomorrow (November 11), leaving markets to digest Monday's trade print and positioning ahead of the next data window. Attention turns to China's October CPI and credit data later this week, with producer prices already reported at a four-year high per FT coverage — a signal that energy-driven cost pressures are building even as weak domestic demand caps consumer inflation (September CPI was 0.90% YoY). Hong Kong markets will watch for any HKMA commentary on aggregate balance dynamics as the HKD sits pinned at 7.85.

Taiwan traders will monitor semiconductor supply-chain headlines and the fallout from Nvidia-related sentiment, which drove the TAIEX's near-5% rally. Cross-border yuan flow data will also be in focus after reports that the CIPS system is heading for a record year.

Other Economic Notes

China's cross-border yuan payment system (CIPS) is on track for its busiest year since launching in 2015, reflecting robust trade settlement and growing currency internationalization — though a new report notes adoption in Africa faces hurdles from weak banking rules and high debt levels. ↓ p.2
Page 1

Greater China Macro Daily(Beta Mode)

November 11, 2026 robomacro.com
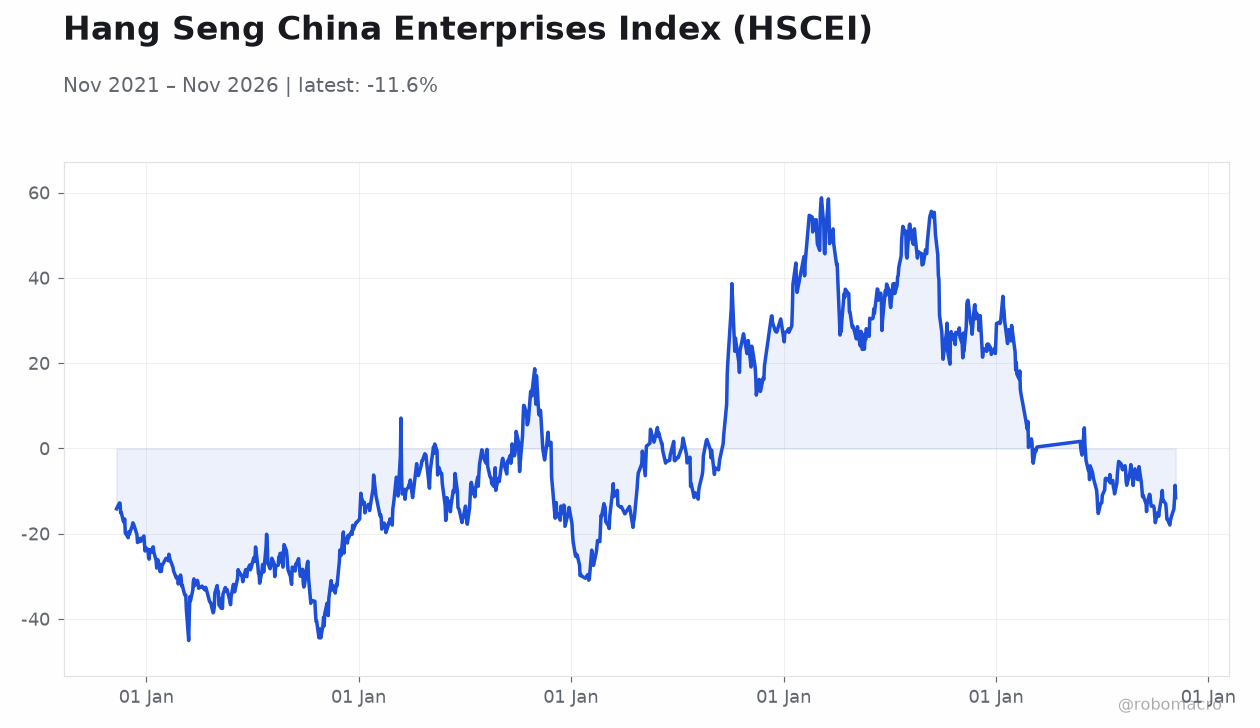
Hang Seng China Enterprises Index (HSCEI) Hang Seng China Enterprises Index (HSCEI) | Type: macro_line | Hang Seng China Enterprises Index (HSCEI): -11.56 (2026-11-06) | Range: -45.05–58.79 | Trend(6pt): -14.16,-20.16,-24.25,38.24,-12.16,-11.56
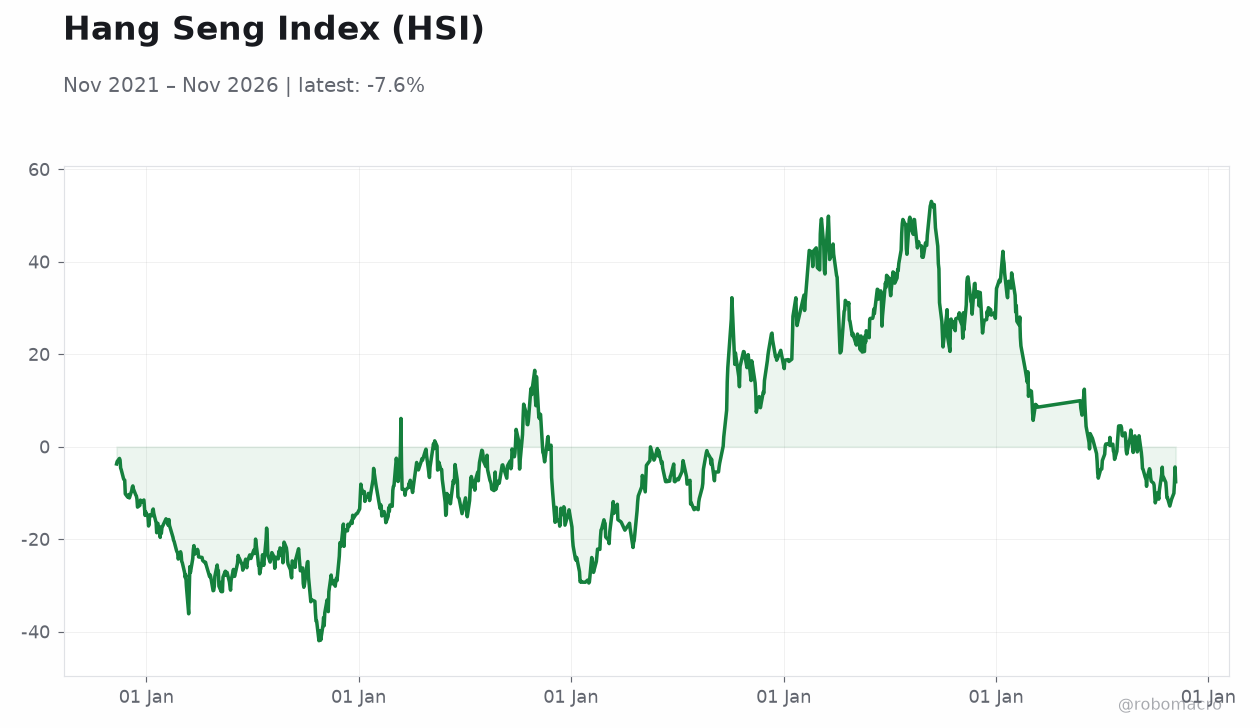
Hang Seng Index (HSI) Hang Seng Index (HSI) | Type: macro_line | Hang Seng Index (HSI): -7.566 (2026-11-06) | Range: -41.97–53.06 | Trend(6pt): -3.733,-16.59,-24.79,36.49,-7.833,-7.566
TAIEX - Taiwan Capitalization Weighted Stock Index TAIEX - Taiwan Capitalization Weighted Stock Index | Type: macro_line | TAIEX - Taiwan Capitalization Weighted Stock Index: 42.3 (2026-11-06) | Range: -25.27–119.9 | Trend(6pt): 31.6,-19.8,15.8,-6.348,52.75,42.3
TAIEX Taiwan Index TAIEX Taiwan Index | Type: market_hloc | Index Level: 4.166e+04 (2026-11-09) | Range: 3.97e+04–4.982e+04 | Trend(5pt): 4.493e+04,4.613e+04,4.772e+04,4.697e+04,4.166e+04

Other Economic Notes (continued)

Beijing is making it easier for African nations to pay for Chinese-led infrastructure in yuan, a slow but deliberate push to expand the renminbi's footprint beyond Asia. The FT's report that producer prices hit a four-year high underscores a bifurcated inflation picture: energy-cost pass-through is lifting factory-gate prices while subdued consumer demand keeps CPI anchored near 0.9%. Meanwhile, China's trade surplus is passing $1 trillion at a record pace, fueling concerns among trading partners about the export boom's impact — a theme likely to intensify into year-end.

Global Macro News

US inflation continues to challenge the economy per NYT coverage, keeping Fed policy expectations volatile and by extension shaping yuan and HKD dynamics. Chicago Fed President Goolsbee said the data-center buildout is "overheating" the economy, a notable signal that AI capex is now a macro variable in its own right — directly relevant to Taiwan's semiconductor complex. On the trade front, Washington is balking at China's demand for a tightly scripted Trump-Xi-Putin summit, with Trump wanting arms-control talks that Beijing has long resisted, adding a geopolitical layer to market risk.

House Minority Leader Jeffries pushed tighter China chip restrictions amid the Nvidia CEO scandal, a reminder that US export-control politics remain a live tail risk for Taiwan suppliers. Japan's finance minister flagged faster BOJ ETF sales yielding roughly $6.3bn a year, while Citibank Korea warned that if semiconductors falter, the Bank of Korea's November hike would end the cycle — regional tech-cycle sensitivity is running high.

Sponsored by Arbitrage Search
Page 2

Greater China Macro Daily(Beta Mode)

November 11, 2026 robomacro.com

Continuation

Greater China Central Banks Watch

The PBoC has no scheduled MLF or LPR decision today, leaving its recent liquidity posture — record state-led ETF purchases and continued yuan fixing near 6.67 — as the operative signal; the central bank appears to be prioritizing stability and equity-market support over aggressive easing. The State Council's tariff-suspension extension on US goods keeps Beijing's trade policy in a conciliatory holding pattern, reducing near-term escalation risk. In Hong Kong, the HKMA faces persistent weak-side pressure as USD/HKD trades at 7.85, the edge of the peg band; intervention and aggregate-balance drainage remain the key mechanics to watch, with HKD rates likely to stay elevated while the peg is defended.

The HKMA also continues its fintech agenda, proposing to designate post-secondary institutions and park companies as domestic public sector entities and convening its taskforce on Northern Metropolis financing. Taiwan's CBC is in a holding phase, with no meeting on the immediate calendar; the TAIEX's 4.94% surge and semiconductor export outlook will be the dominant inputs for its next policy assessment, particularly given US chip-restriction headlines.

Sponsored by Arbitrage Search
Page 3