RoboMacro ResearchAlso todaySee the FX Daily

Greater China Macro Daily(Beta Mode)

November 13, 2026 robomacro.com

China Trade Surplus Narrows as Imports Surge; PBoC Signals Patience

35.20 Exports Year-over-Year41.60 Imports Year-over-Year105,280m Trade Balance
Shanghai Composite3,659.68-0.57%
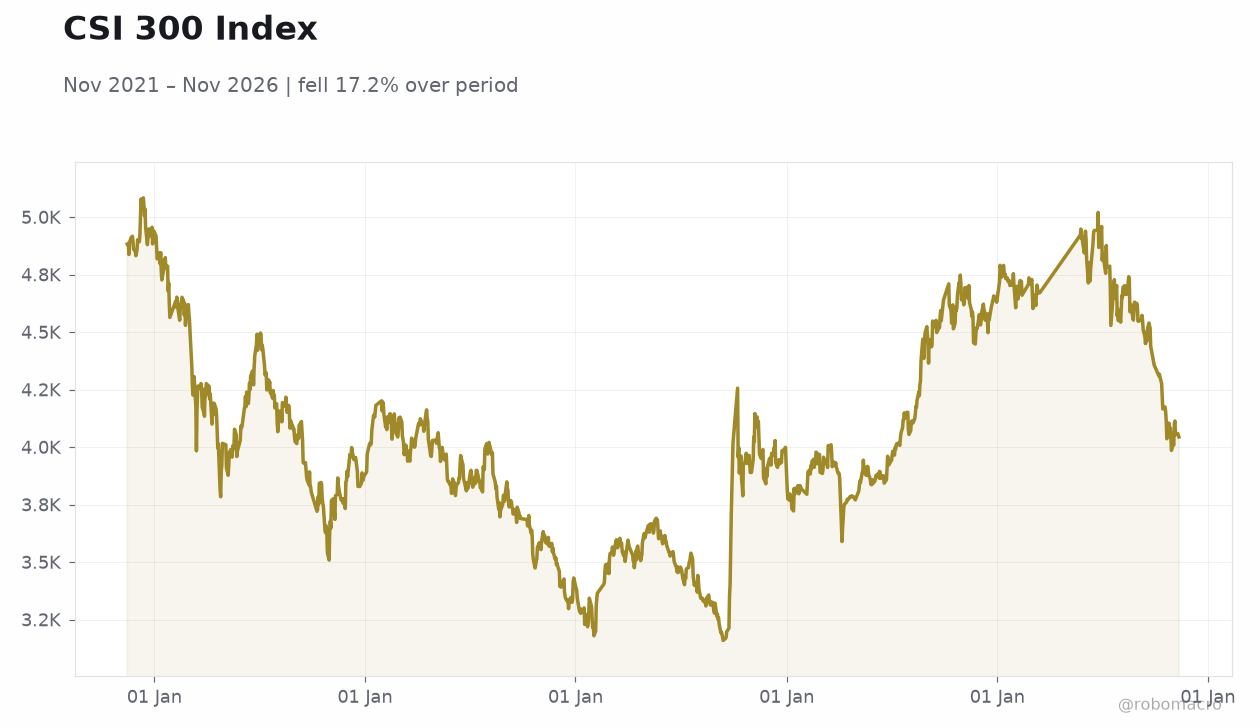
CSI 3004,043.93-0.78%
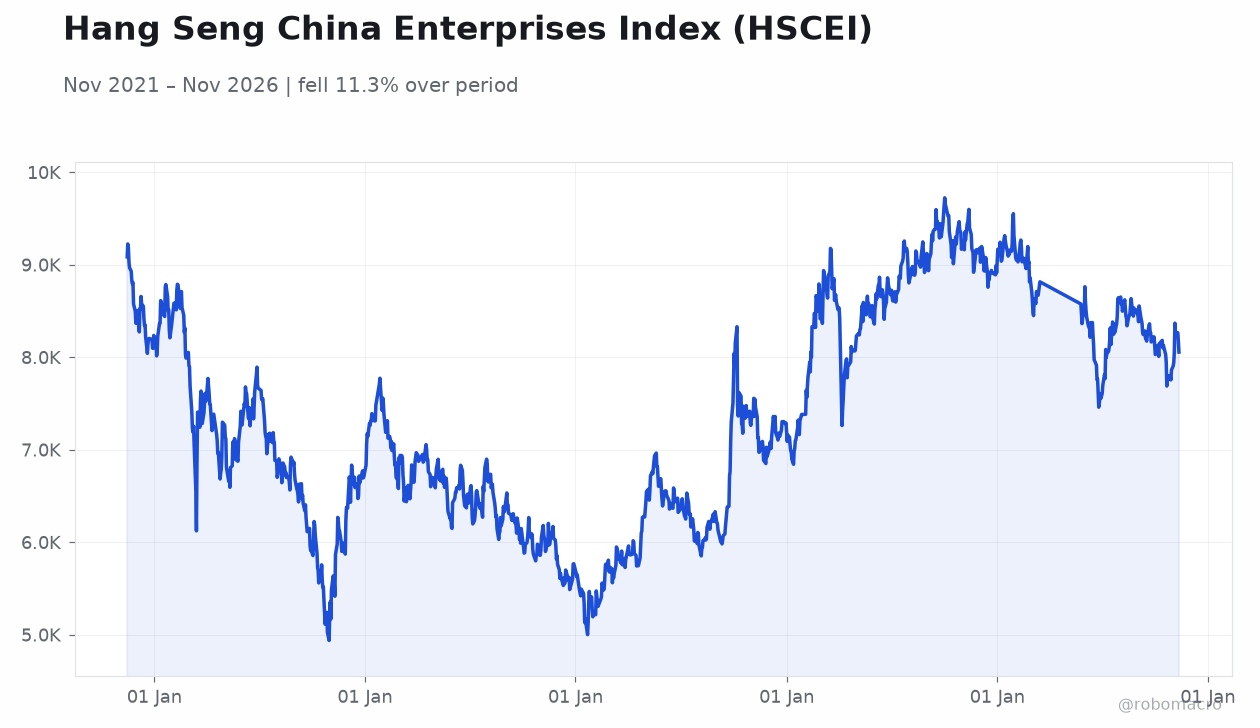
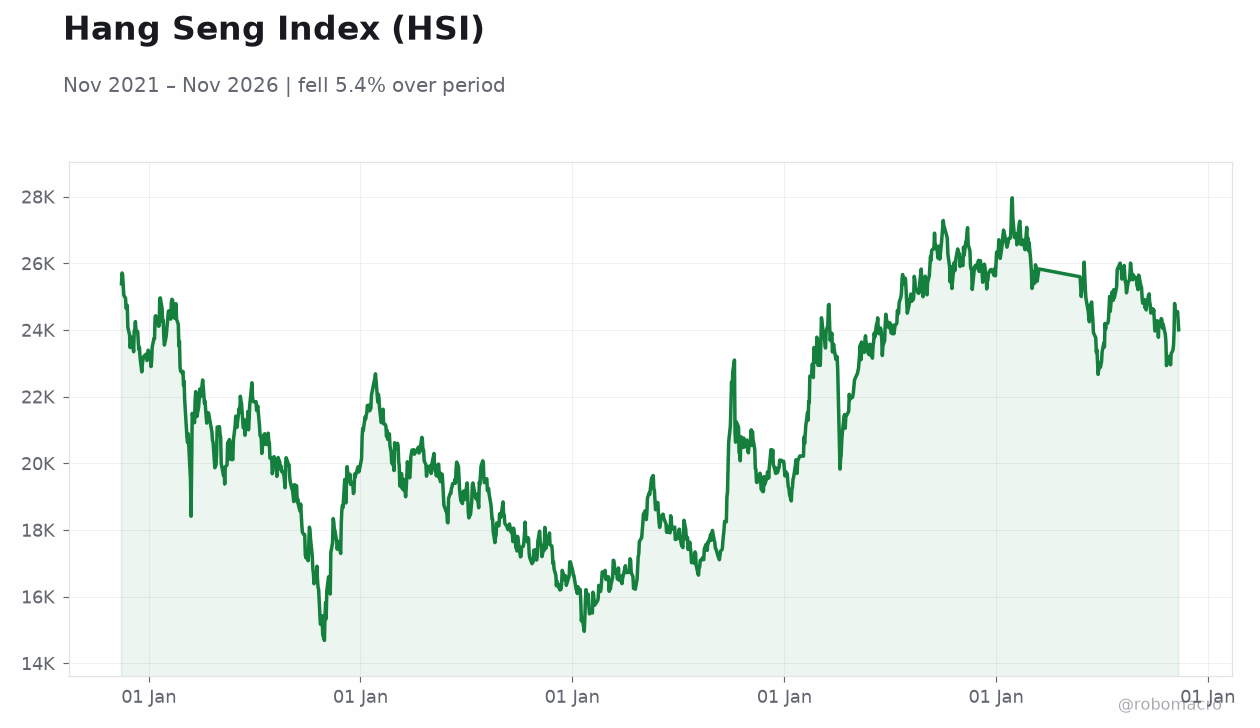
Hang Seng24,315.92-0.98%
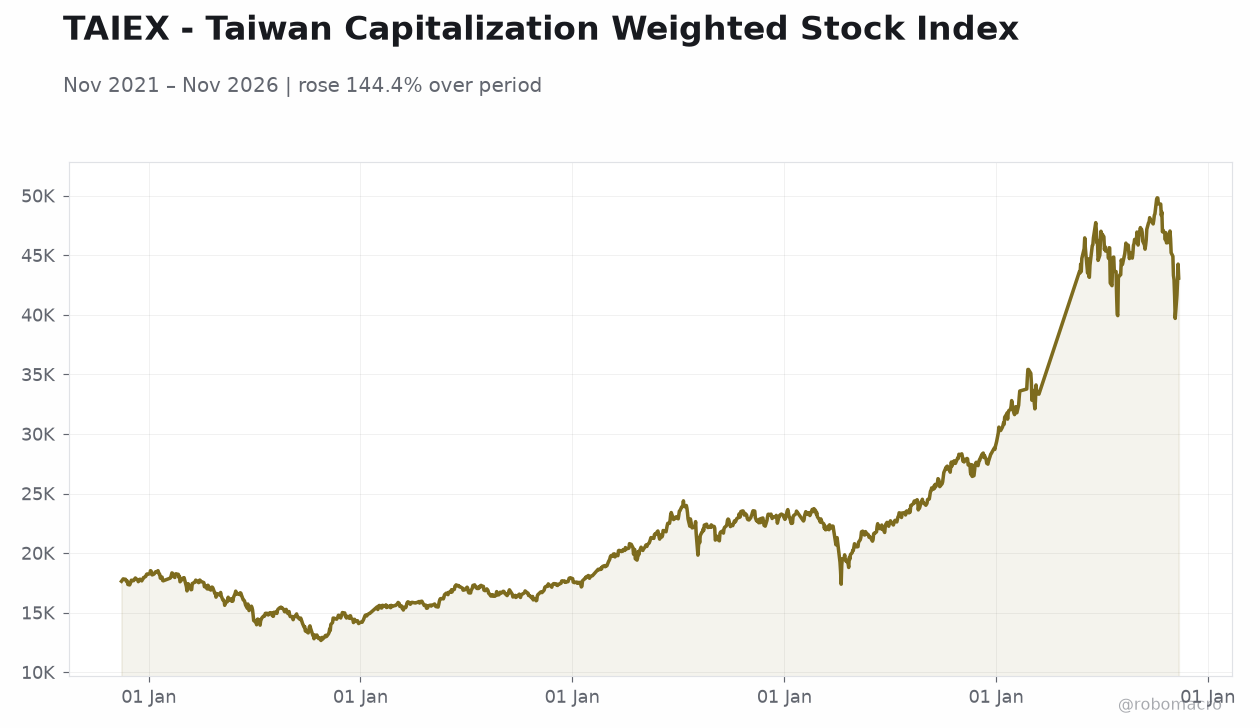
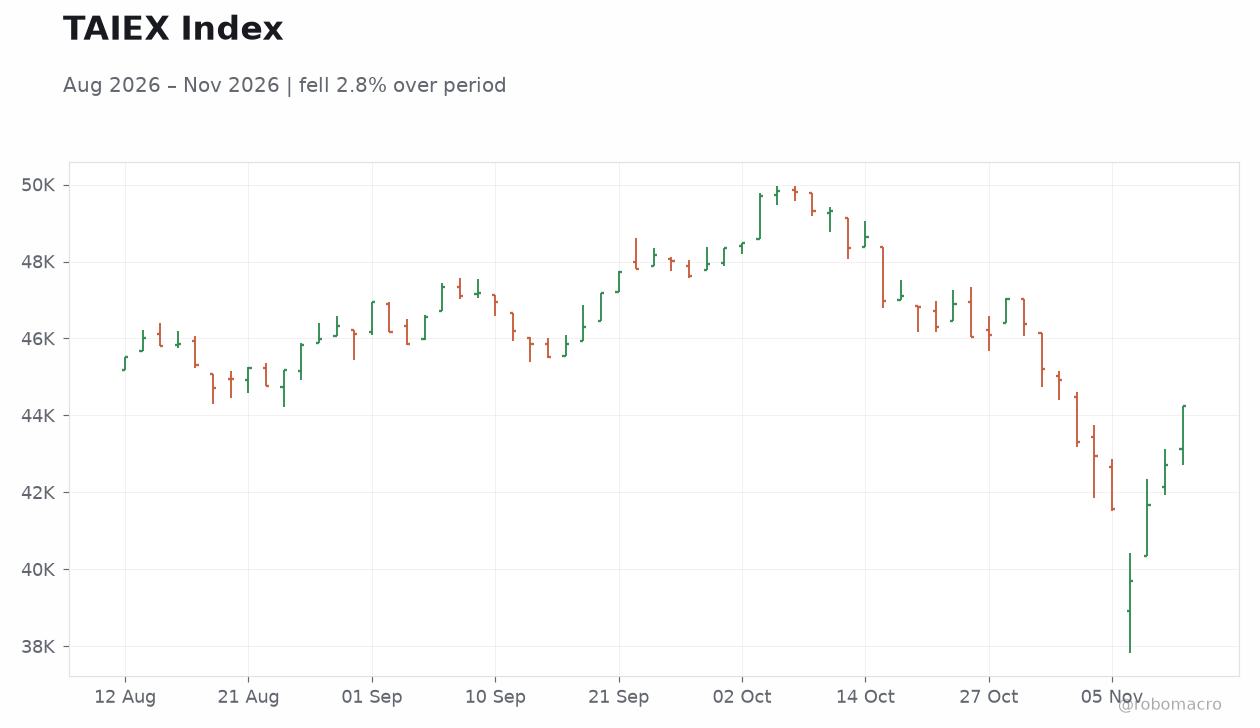
TAIEX44,257.15+3.62%

Market Snapshot

AssetLevelChange
Shanghai Composite3,659.68-0.57%
CSI 3004,043.93-0.78%
Hang Seng24,315.92-0.98%
TAIEX44,257.15+3.62%
USD/CNY6.67-0.01%
USD/HKD7.84-0.01%
Copper6.20-1.27%
Brent Crude95.77+3.24%
Gold3,880.70-2.99%
Bitcoin71,392.29-3.48%
China 2Y Govt Yield--
China 10Y Govt Yield--

Prior Economic Events

Data Prior Cons Actual
Exports Year-over-Year36.3033.5035.20
Imports Year-over-Year313241.60
Trade Balance133,530m125,800m105,280m
CSI 300 IndexCSI 300 Index | Type: macro_line | CSI 300 Index: 4044 (2026-11-12) | Range: 3159–5084 | Trend(5pt): 4882,4137,3503,3874,4044

Today's Economic Events

Data Prior Cons Time
Friday (2026-11-13)
Current Account Prel193,700m-04:00
  • China's November trade surplus narrowed to $105.28bn, well below the $125.8bn consensus, as imports surged 41.6% YoY versus 32% expected while exports rose 35.2% YoY, above the 33.5% consensus but below the 36.3% prior.
  • The PBoC's Q3 monetary policy report vows ample liquidity and yuan stability but hints at a pause in the easing cycle, with the USD/CNY reference rate fixed at 6.7191 versus 6.7167 previously.
  • Mainland equities softened (CSI 300 -0.78%, Shanghai Composite -0.57%) and Hong Kong's Hang Seng fell 0.98%, while Taiwan's TAIEX surged 3.62% on AI-driven semiconductor optimism.

Yesterday's Recap

China's November trade data dominated the session, with exports rising 35.2% YoY (consensus 33.5%, previous 36.3%) and imports surging 41.6% YoY against a 32% consensus and 31% prior — a striking import acceleration that points to resilient domestic demand and front-loaded commodity purchases. The trade surplus narrowed sharply to $105.28bn versus the $125.8bn consensus and $133.53bn prior, a compression that should ease some external rebalancing pressure ahead of the Trump-Xi talks. Mainland equities reacted defensively, with the CSI 300 down 0.78% to 4,043.93 and the Shanghai Composite off 0.57% to 3,659.68, while Hong Kong's Hang Seng fell 0.98% to 24,315.92.

Taiwan was the standout, with the TAIEX surging 3.62% to 44,257.15 on continued AI and semiconductor demand optimism. The yuan was essentially flat, USD/CNY at 6.67 (-0.01%), and USD/HKD held at 7.84 (-0.01%) near the strong side of the peg band. Commodities diverged sharply: Brent crude jumped 3.24% to $95.77 while copper fell 1.27% to $6.20, gold slid 2.99% to $3,880.70 and Bitcoin dropped 3.48% to $71,392.29.

The Day Ahead

The calendar is light, with China's preliminary current account for Q3 due Friday at 04:00 ET (previous $193.7bn), the only scheduled Greater China release and one without a consensus estimate. With no tier-one data on the docket, markets will likely trade on the PBoC's Q3 policy report language and follow-through from the trade print. Hong Kong flows warrant monitoring after the HKMA's successful 3-year RMB sovereign bond tender, which drew a 7.37 bid-to-cover ratio on RMB1.5bn issued against RMB5.335bn in applications — a strong signal of offshore RMB demand.

Taiwan's TAIEX momentum and semiconductor supply-chain headlines remain the key regional swing factor. Attention also turns to the upcoming Trump-Xi talks, with Treasury Secretary Bessent's call for "more balanced" trade framing the backdrop.

Other Economic Notes

The import surge of 41.6% YoY is the most consequential detail in the trade release, suggesting domestic absorption is strengthening even as the surplus compresses — a combination that complicates the external-balance narrative Washington has pressed. ↓ p.2
Page 1

Greater China Macro Daily(Beta Mode)

November 13, 2026 robomacro.com
Hang Seng China Enterprises Index (HSCEI) Hang Seng China Enterprises Index (HSCEI) | Type: macro_line | Hang Seng China Enterprises Index (HSCEI): 8057 (2026-11-12) | Range: 4939–9724 | Trend(6pt): 9086,7774,6004,8859,8266,8057
Hang Seng Index (HSI) Hang Seng Index (HSI) | Type: macro_line | Hang Seng Index (HSI): 2.401e+04 (2026-11-12) | Range: 1.469e+04–2.797e+04 | Trend(6pt): 2.539e+04,2.269e+04,1.71e+04,2.447e+04,2.456e+04,2.401e+04
TAIEX - Taiwan Capitalization Weighted Stock Index TAIEX - Taiwan Capitalization Weighted Stock Index | Type: macro_line | TAIEX - Taiwan Capitalization Weighted Stock Index: 4.309e+04 (2026-11-12) | Range: 1.267e+04–4.982e+04 | Trend(5pt): 1.763e+04,1.549e+04,2.074e+04,2.243e+04,4.309e+04
TAIEX Index TAIEX Index | Type: market_hloc | TAIEX: 4.426e+04 (2026-11-11) | Range: 3.97e+04–4.982e+04 | Trend(5pt): 4.552e+04,4.616e+04,4.816e+04,4.682e+04,4.426e+04

Other Economic Notes (continued)

China's CPI at 0.90% YoY (September, OECD) remains well below target, leaving ample room for further stimulus if growth falters. The renminbi's internationalization dilemma remains a structural theme: Beijing cannot easily open its capital account without ceding control over the exchange rate, and the PBoC's emphasis on yuan stability reflects that trade-off. Nissan's weaker China sales forecast underscores intensifying competitive pressure in the mainland auto market.

Stanbic IBTC's new naira-yuan payment platform is a small but telling step in RMB settlement expansion across emerging markets.

Global Macro News

Oil's 3.24% jump to $95.77 is the dominant global macro input for Greater China, raising imported energy costs just as the import bill surges. Gold's 2.99% slide to $3,880.70 and Bitcoin's 3.48% drop to $71,392.29 signal a broader risk-off rotation into cyclicals and away from defensive hedges. Treasury Secretary Bessent's call for a "more balanced" US-China trading relationship ahead of the Trump-Xi talks sets expectations for the bilateral agenda, with the narrowed surplus potentially easing friction.

The AI-driven capex cycle continues to power Taiwan's export outlook. China and Korea are being favored over Taiwan by some strategists on relative valuation, a rotation worth watching given the TAIEX's sharp rally. The energy shock and AI's labor-market disruption were flagged by Taiwan's CBC governor as fresh challenges for monetary policy globally.

Sponsored by Arbitrage Search
Page 2

Greater China Macro Daily(Beta Mode)

November 13, 2026 robomacro.com

Continuation

Greater China Central Banks Watch

The PBoC's Q3 monetary policy report vows to step up policy support for the economy while pledging ample liquidity and yuan stability, but the language hints the current easing cycle may be nearing a pause — a signal markets read as patience rather than pivot. The central bank fixed the USD/CNY reference rate at 6.7191 versus 6.7167 previous, a modestly firmer bias consistent with its stability pledge. No MLF or LPR decision is scheduled imminently, leaving the report's forward guidance as the key policy signal.

In Hong Kong, the HKMA's 3-year RMB sovereign bond tender drew a 7.37 bid-to-cover ratio on RMB1.5bn issued against RMB5.335bn in applications, reflecting robust offshore RMB demand, while USD/HKD at 7.84 sits near the strong side of the 7.75-7.85 band. The HKMA and SFC co-hosted a Project Ensemble seminar advancing tokenisation, including tokenized funds with 24-hour trading — a structural deepening of Hong Kong's fintech infrastructure. Taiwan's CBC held steady with no scheduled decision, its governor flagging energy shocks and AI as fresh monetary policy challenges while the semiconductor export outlook remains the dominant variable for the island's rate path.

Sponsored by Arbitrage Search
Page 3