Greater China Macro Daily(Beta Mode)
PBOC Sets Strongest Yuan Fixing Since July 2022
Market Snapshot
| Asset | Level | Change |
|---|---|---|
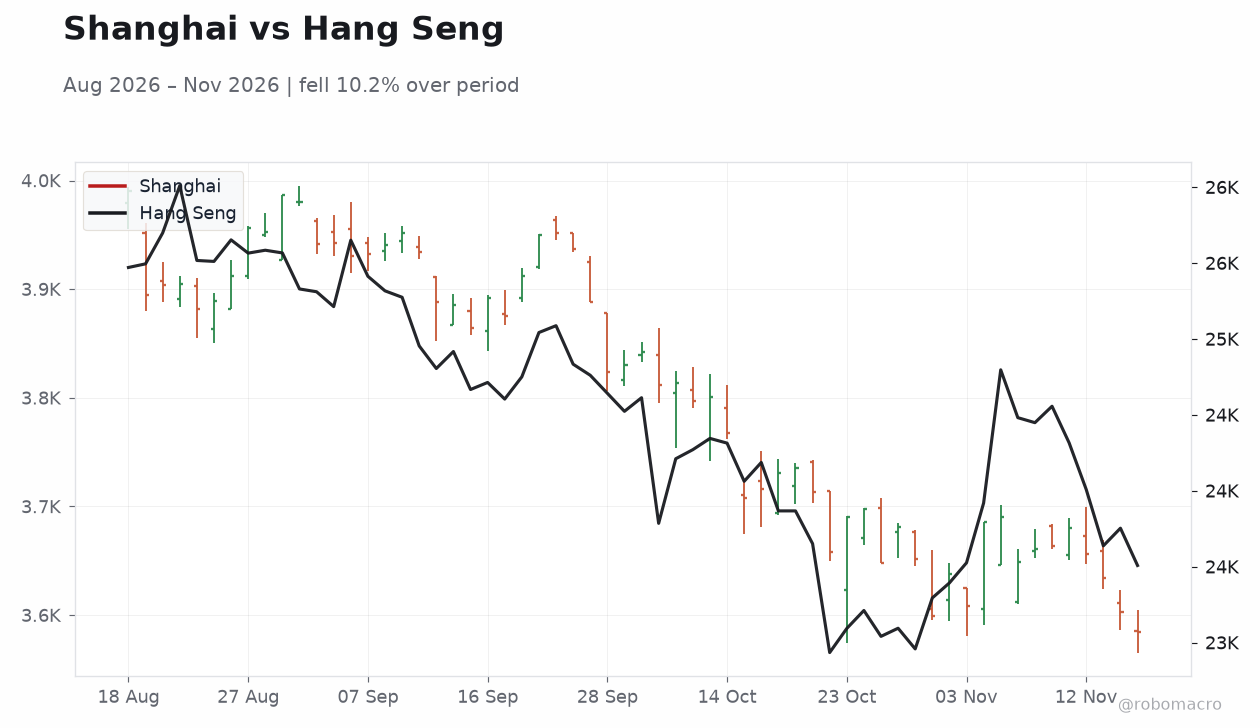
| Shanghai Composite | 3,581.69 | -0.08% |
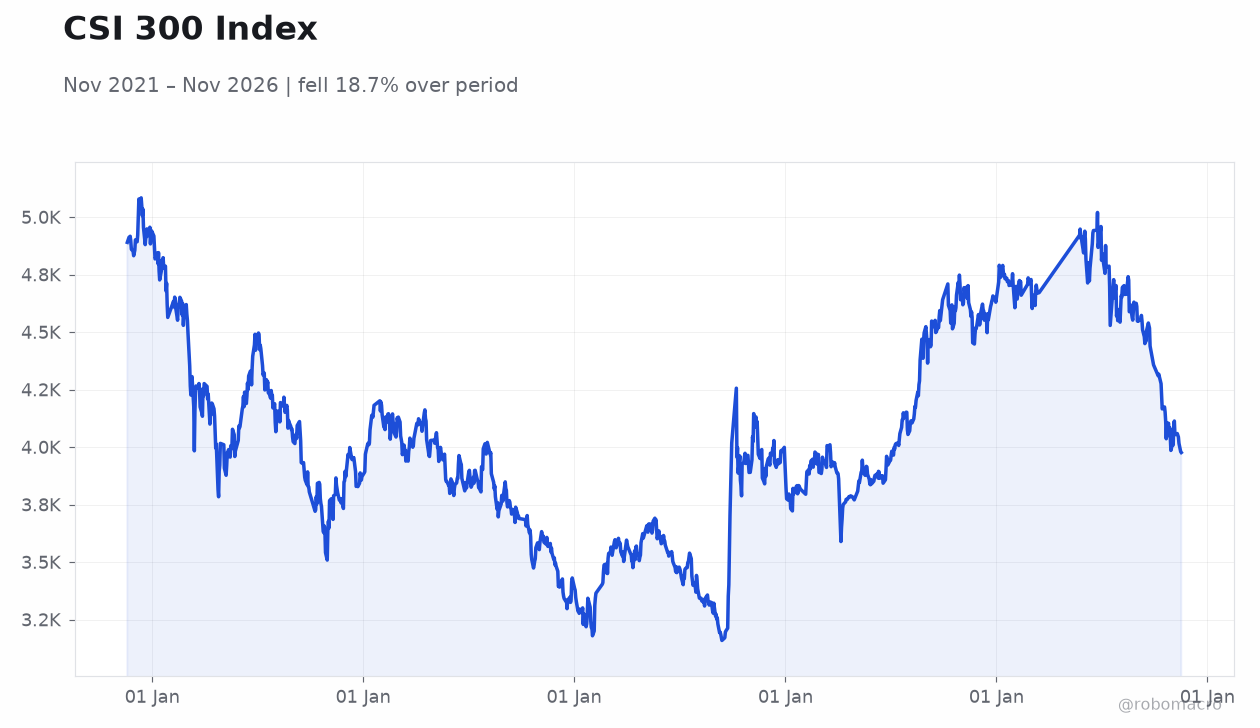
| CSI 300 | 3,983.77 | +0.18% |
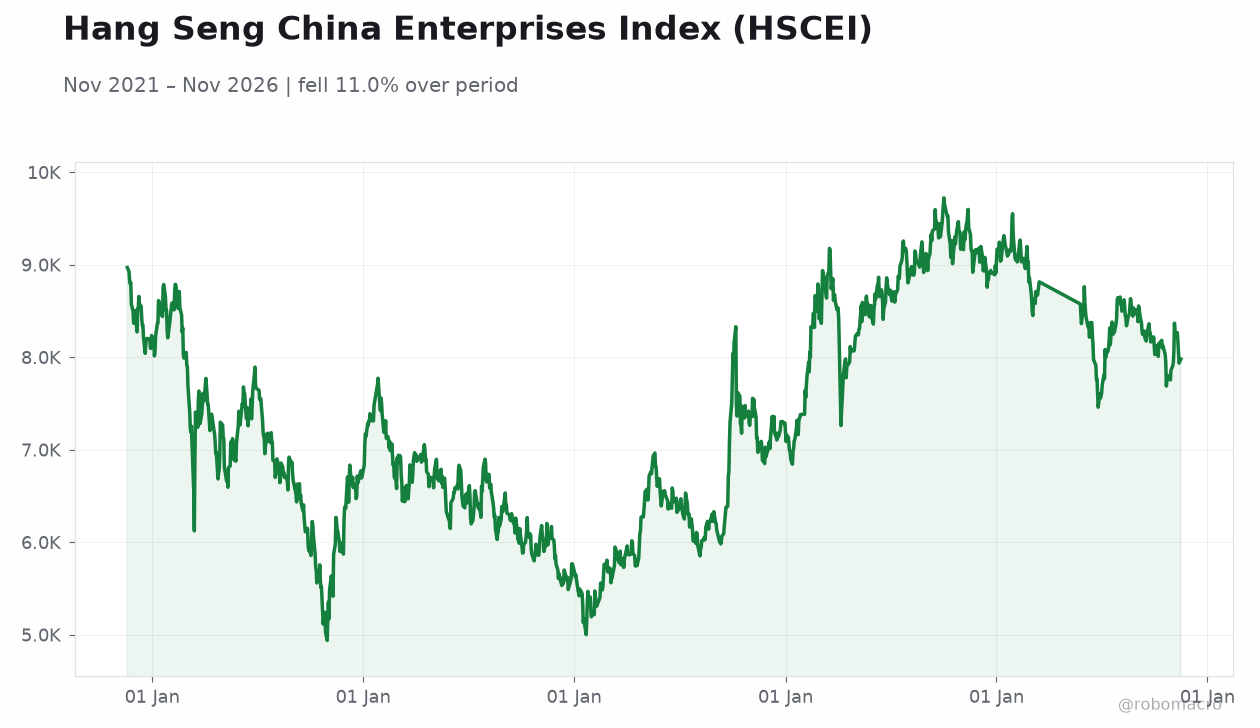
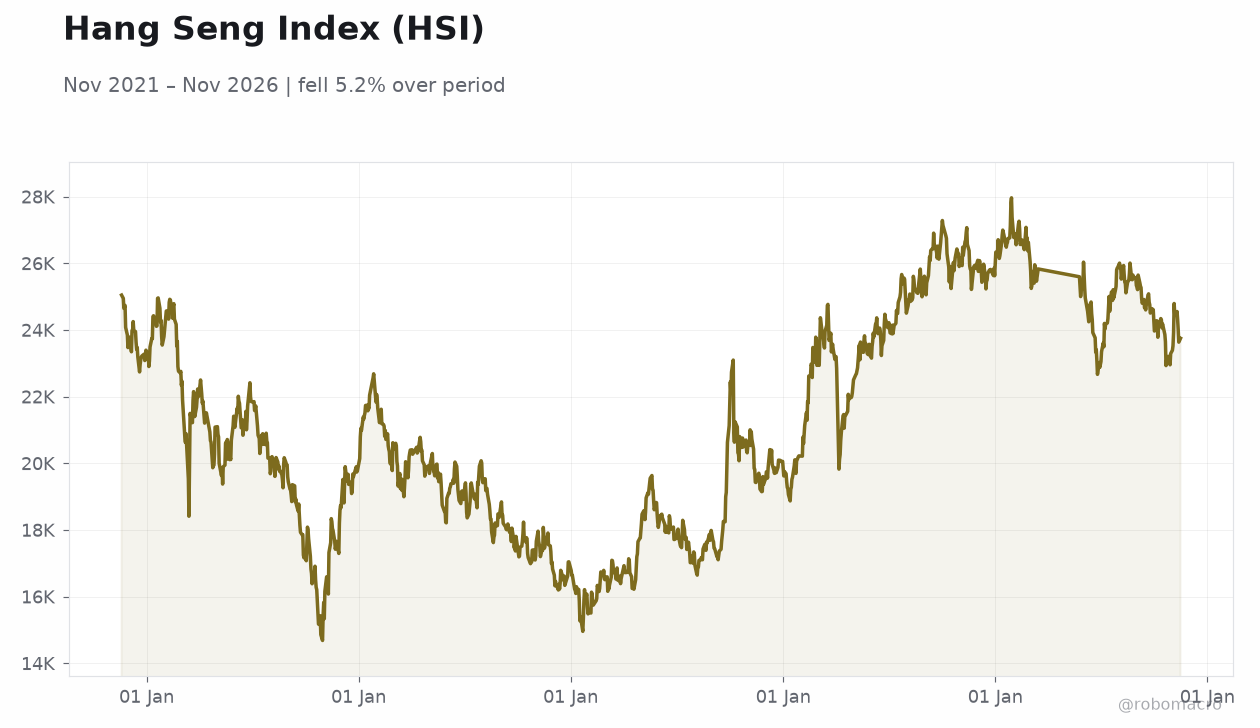
| Hang Seng | 23,508.17 | -1.03% |
| TAIEX | 40,092.11 | -2.31% |
| USD/CNY | 6.66 | -0.10% |
| USD/HKD | 7.85 | -0.02% |
| Copper | 5.68 | -4.99% |
| Brent Crude | 88.89 | -4.56% |
| Gold | 3,734.30 | -3.36% |
| Bitcoin | 62,639.53 | -3.47% |
| China 2Y Govt Yield | - | - |
| China 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
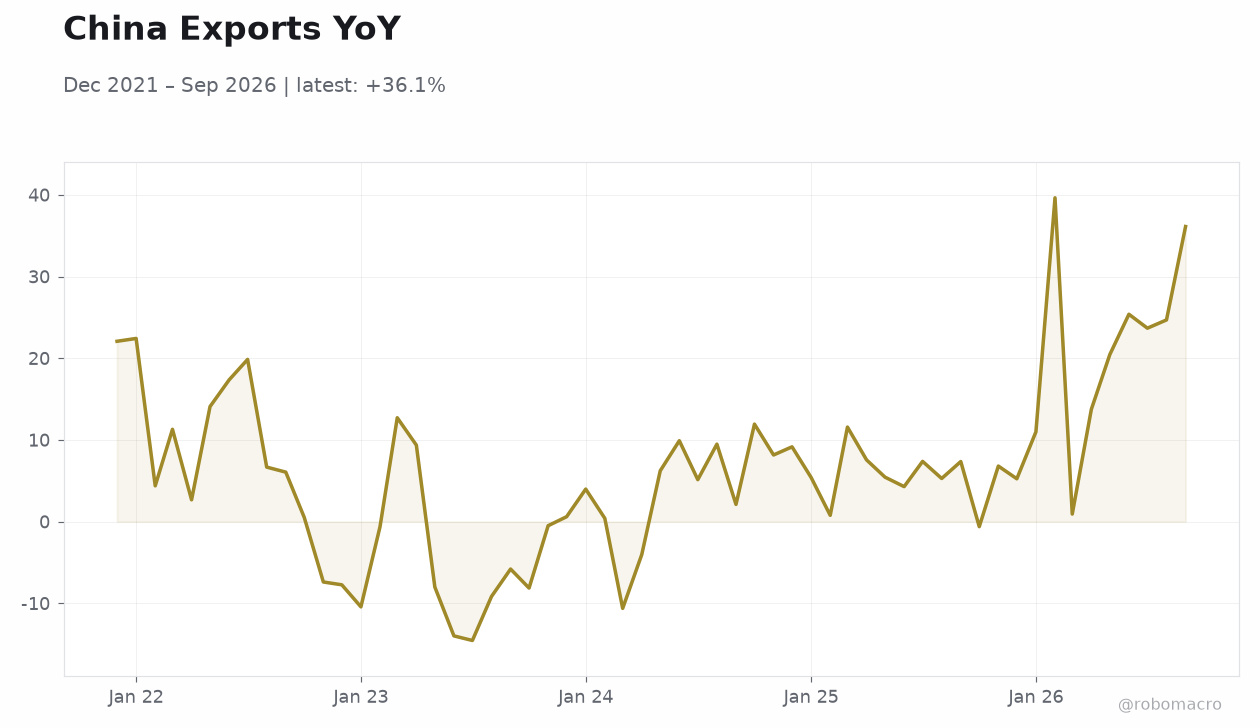 China Exports YoY | Type: macro_line | XTEXVA01CNM667S: 36.12 (2026-09-01) | Range: -14.55–39.64 | Trend(6pt): 22.08,-0.6198,-4.032,4.287,24.69,36.12
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Thursday (2026-11-19) | |||
| Loan Prime Rate 1Y | 3 | 3 | 20:15 |
| Loan Prime Rate 5Y | 3.50 | 3.50 | 20:15 |
- PBOC set the daily yuan fixing at its strongest level since July 2022 ahead of the APEC summit in Shenzhen.
- Foreign investors bought the most onshore Chinese government bonds since May, drawn by haven appeal amid global volatility.
- Equity markets diverged with CSI 300 edging higher while Hang Seng and TAIEX posted sharp losses.
Yesterday's Recap
Mainland China equity benchmarks closed mixed as the Shanghai Composite slipped 0.08 percent to 3,581.69 while the CSI 300 advanced 0.18 percent to 3,983.77. Hong Kong’s Hang Seng Index fell 1.03 percent to 23,508.17 and Taiwan’s TAIEX dropped 2.31 percent to 40,092.11 amid semiconductor sector weakness. The PBOC fixed the yuan at its strongest level since July 2022, supporting USD/CNY which eased 0.10 percent to 6.66.
Global investors added onshore Chinese government bonds at the fastest pace since May, reflecting haven demand. Copper fell 4.99 percent to 5.68 and Brent crude declined 4.56 percent to 88.89, both serving as proxies for softer near-term Chinese industrial demand. No major data releases printed in Greater China yesterday.
Canada and China agreed further tariff reductions on seafood and steel, extending bilateral trade liberalization. Property sector deleveraging continues to weigh on sentiment, with developers exploring asset spin-offs to manage debt. Semiconductor supply chains remain central to Taiwan’s export outlook and broader regional growth prospects.
The Day Ahead
Markets will focus on the PBOC’s Loan Prime Rate decisions scheduled for tomorrow evening. The 1-year LPR is expected to hold at 3.0 percent and the 5-year LPR at 3.5 percent, consistent with the current policy stance. Analysts will parse any accompanying guidance for signals on liquidity operations ahead of year-end.
APEC summit discussions in Shenzhen on trade and security may produce incremental policy language affecting cross-border flows. No data releases are scheduled for Hong Kong or Taiwan tomorrow. Domestic demand trends will determine the pace of any further yuan appreciation through 2027.
Other Economic Notes
Foreign inflows into Chinese bonds underscore the appeal of onshore yields relative to global alternatives. UBS economist Song Yu projected the yuan could reach 6.25 against the dollar by end-2027 if domestic demand recovers. Broader risk-off flows supported haven assets including Chinese government bonds.
The HKMA continues to advance work with Swift on tokenized deposits to improve cross-border payment efficiency and is studying agentic AI tools to detect crypto-related financial crime. Aggregate balance and USD/HKD peg mechanics remain stable near 7.85.