India Macro Daily(Beta Mode)
Forex Reserves Hit Record High as Oil Rises
Market Snapshot
| Asset | Level | Change |
|---|---|---|
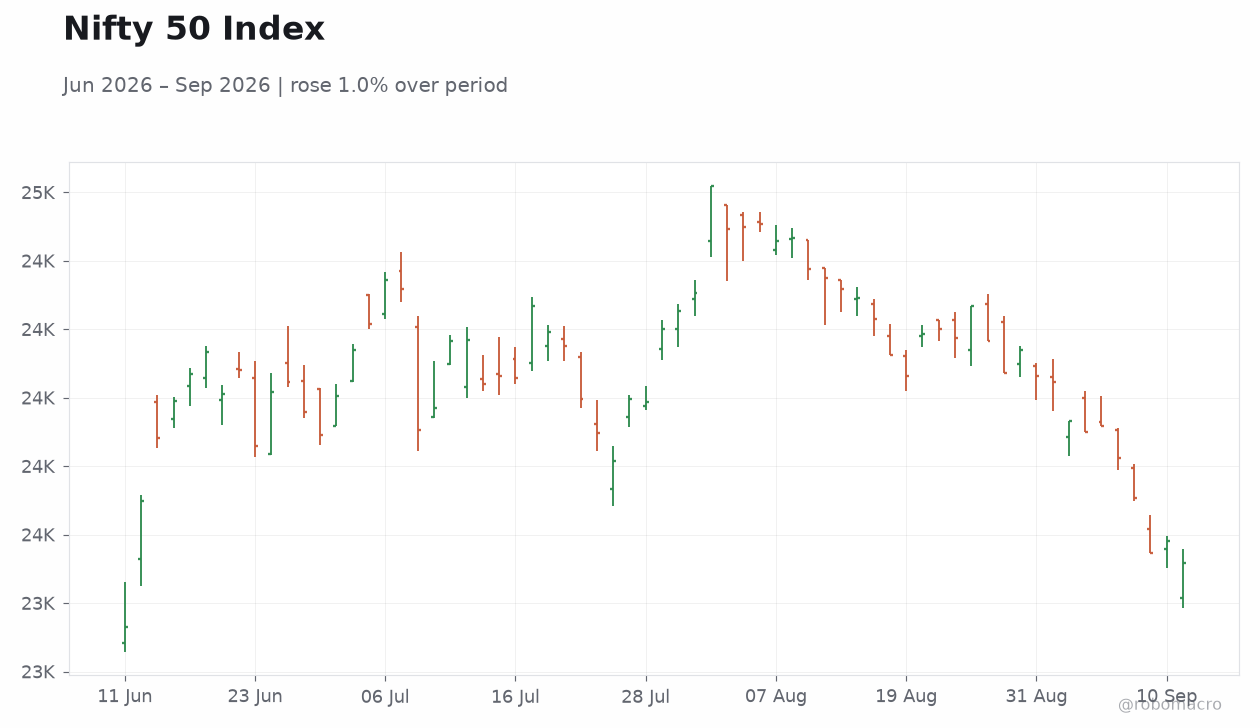
| Nifty 50 | 23,398.10 | -0.34% |
| Sensex | 74,781.76 | -0.16% |
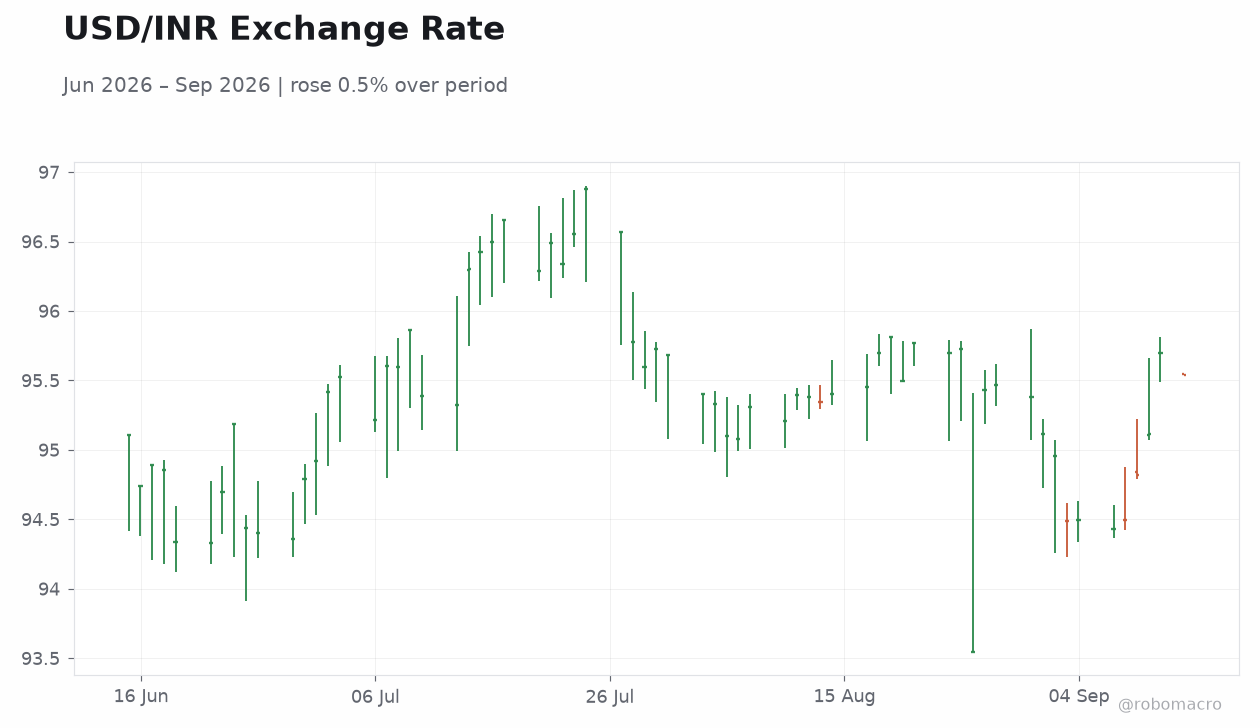
| USD/INR | 95.54 | -0.16% |
| EUR/INR | 110.80 | +0.06% |
| Reliance | 1,257.50 | -1.30% |
| HDFC Bank | 708.25 | +2.08% |
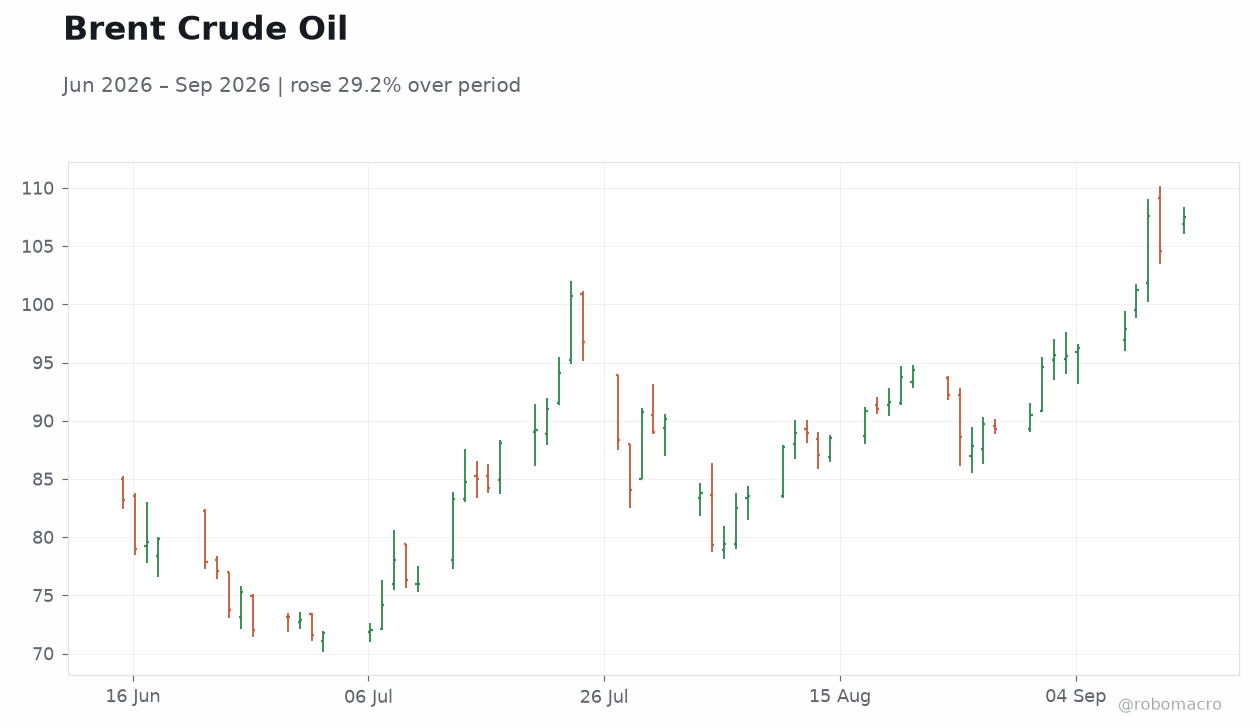
| Brent Crude | 107.44 | +2.71% |
| Gold | 4,380.90 | +0.34% |
| Bitcoin | 76,517.53 | -0.97% |
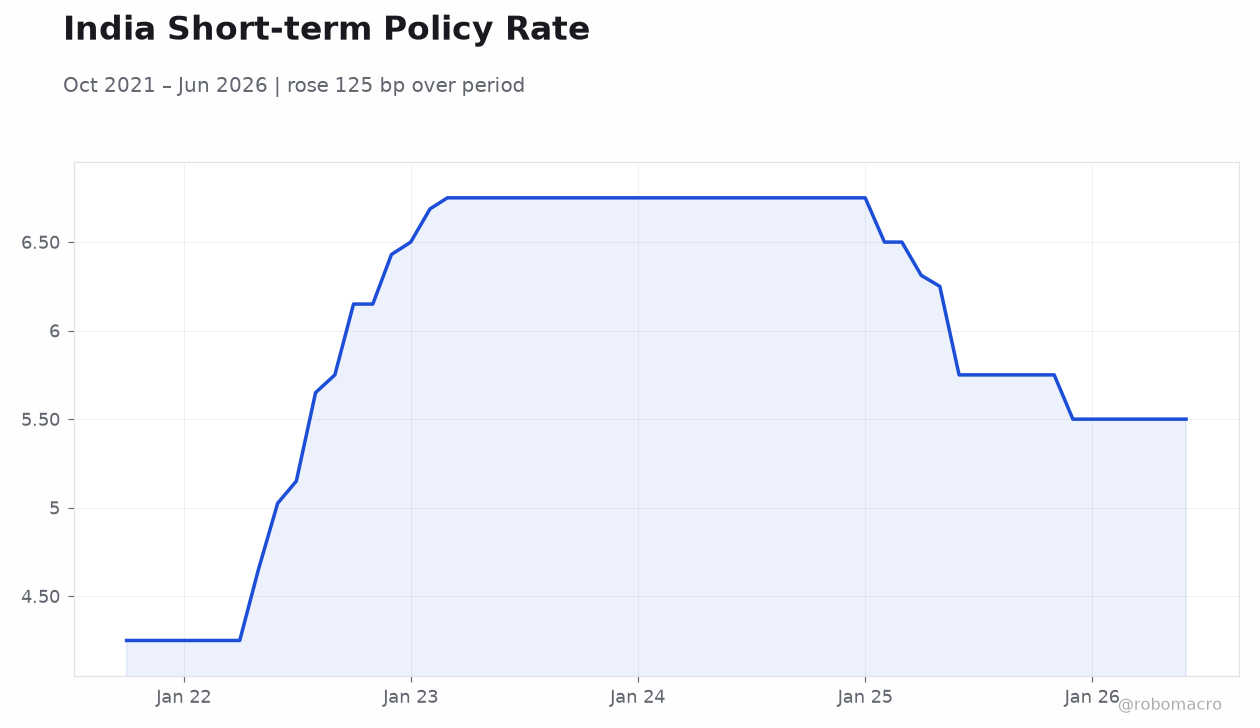
| India Short-term Rate | 5.50% | +0.00% |
| India Long-term Rate | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
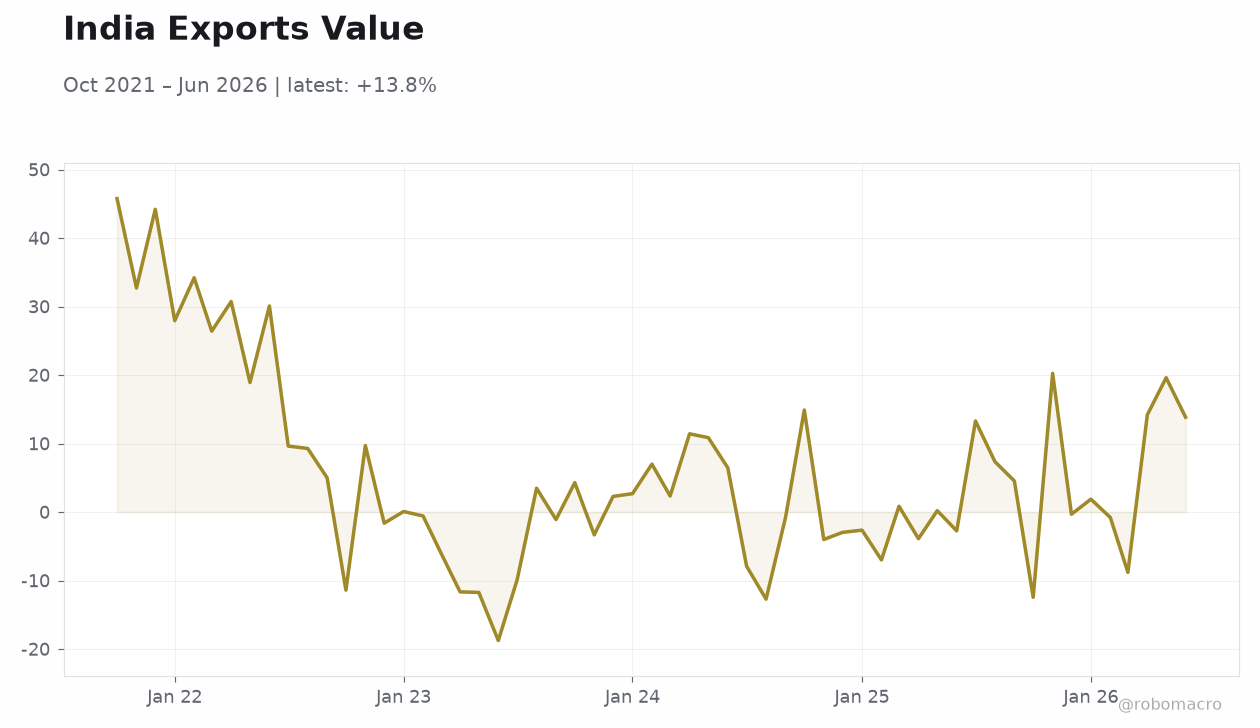 India Exports Value | Type: macro_line | Exports (USD mn): 13.85 (2026-06-01) | Range: -18.76–45.75 | Trend(5pt): 45.75,-1.63,6.995,-3.89,13.85
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Monday (2026-09-14) | |||
| Inflation Rate Year-over-Year | 4.45 | 4.80 | 06:30 |
- India ranks as world’s fourth-largest forex holder after record dollar inflows
- Equity benchmarks slip as Brent crude jumps 2.71% to $107.44
- September CPI release tomorrow carries medium impact on rate expectations
Yesterday's Recap
Equity indices closed lower with Nifty 50 at 23,398.10, down 0.34%, and Sensex at 74,781.76, down 0.16%. Reliance Industries fell 1.30% to 1,257.50 while HDFC Bank gained 2.08% to 708.25. The rupee firmed modestly, with USD/INR closing at 95.54, down 0.16%, and EUR/INR at 110.80, up 0.06%.
Brent crude rose 2.71% to 107.44 and gold advanced 0.34% to 4,380.90. No economic data releases occurred on 12 September, leaving market pricing for the RBI unchanged. India’s short-term rate held steady at 5.50%.
Reports highlighted ongoing pressure on the rupee from the oil rally and rising US yields eroding RBI support.
The Day Ahead
Markets will focus on the Inflation Rate YoY release scheduled for 06:30 ET on 14 September. Consensus expects 4.8% versus the prior 4.45%. The print marks the first inflation reading since the last MPC meeting and could shift near-term rate expectations.
Any material upside surprise may support G-Sec yields and weigh on the rupee. Traders will also monitor global oil prices and US Treasury yields for spillover effects on Indian assets. Tokenized government bond settlements via CBDC remain in focus following the recent launch.
Other Economic Notes
India became the world’s fourth-largest foreign-exchange holder after record dollar inflows, bolstering external buffers. Finance Minister Sitharaman urged the RBI to sharpen the digital-rupee platform’s capabilities and expand CBDC adoption amid the tokenized bonds rollout. The US Commerce Department finalized anti-dumping duties of 123.04% on solar imports from India, creating headwinds for the sector.
These developments underscore India’s push toward digital finance while exposing export vulnerabilities to trade measures. Broader growth momentum remains supported by strong capital inflows despite external risks.
Global Macro News
Surging Brent crude above $107 and firmer US yields are cited as chipping away at RBI support for the rupee. Hawkish Fed bets have extended the Indian currency’s recent decline. ↓ p.2