India Macro Daily(Beta Mode)
CPI Overshoot Curbs RBI Easing Odds
Market Snapshot
| Asset | Level | Change |
|---|---|---|
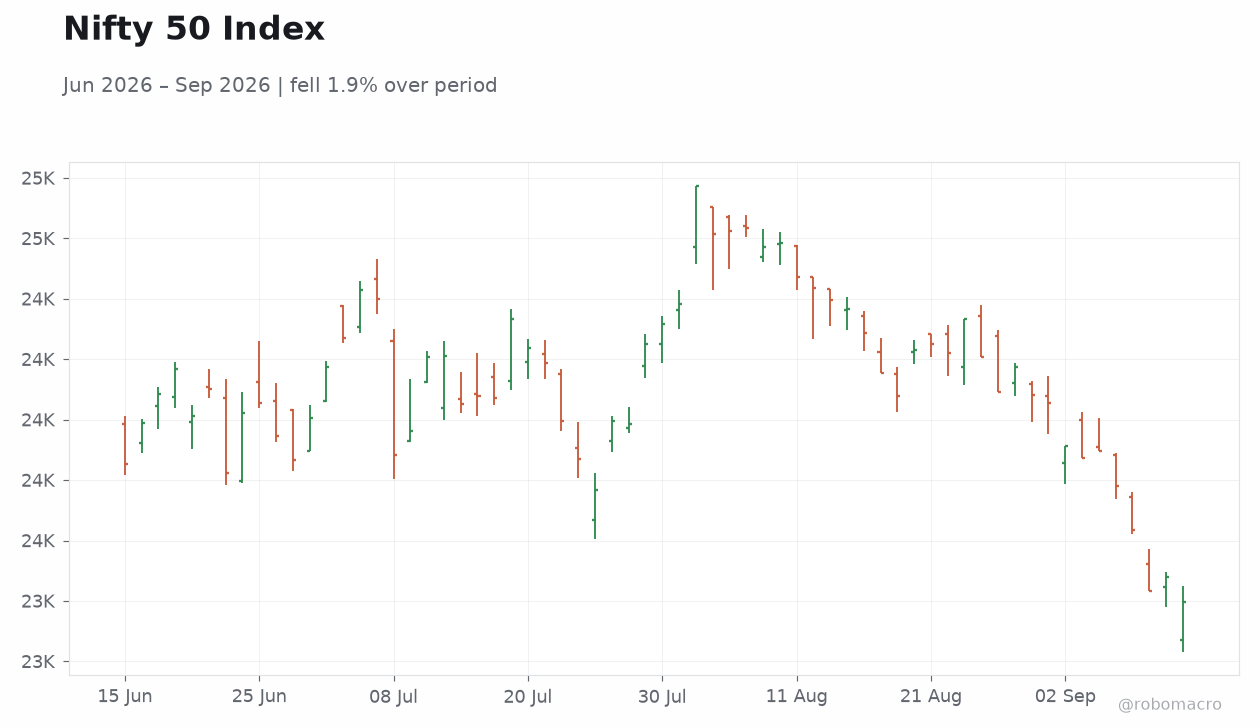
| Nifty 50 | 23,398.10 | -0.34% |
| Sensex | 74,781.76 | -0.16% |
| USD/INR | 95.03 | -0.69% |
| EUR/INR | 107.44 | -2.98% |
| Reliance | 1,257.50 | -1.30% |
| HDFC Bank | 708.25 | +2.08% |
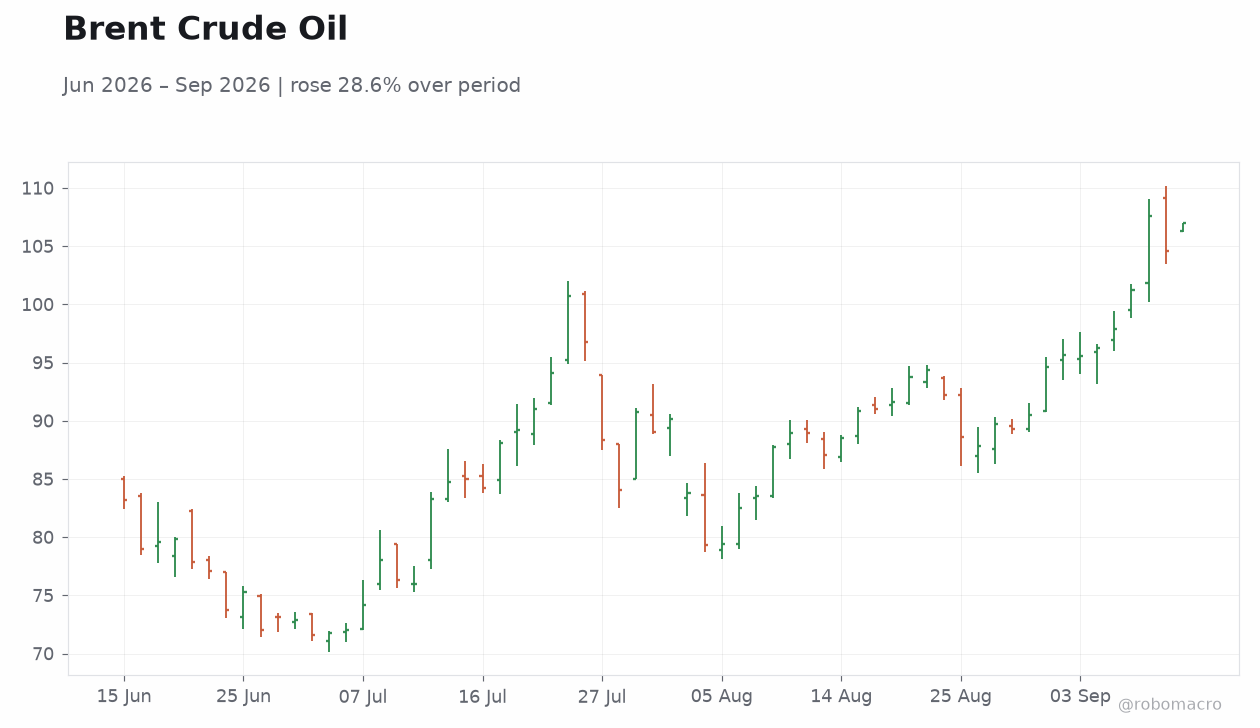
| Brent Crude | 106.93 | +2.22% |
| Gold | 4,324.70 | -1.91% |
| Bitcoin | 78,010.78 | +1.53% |
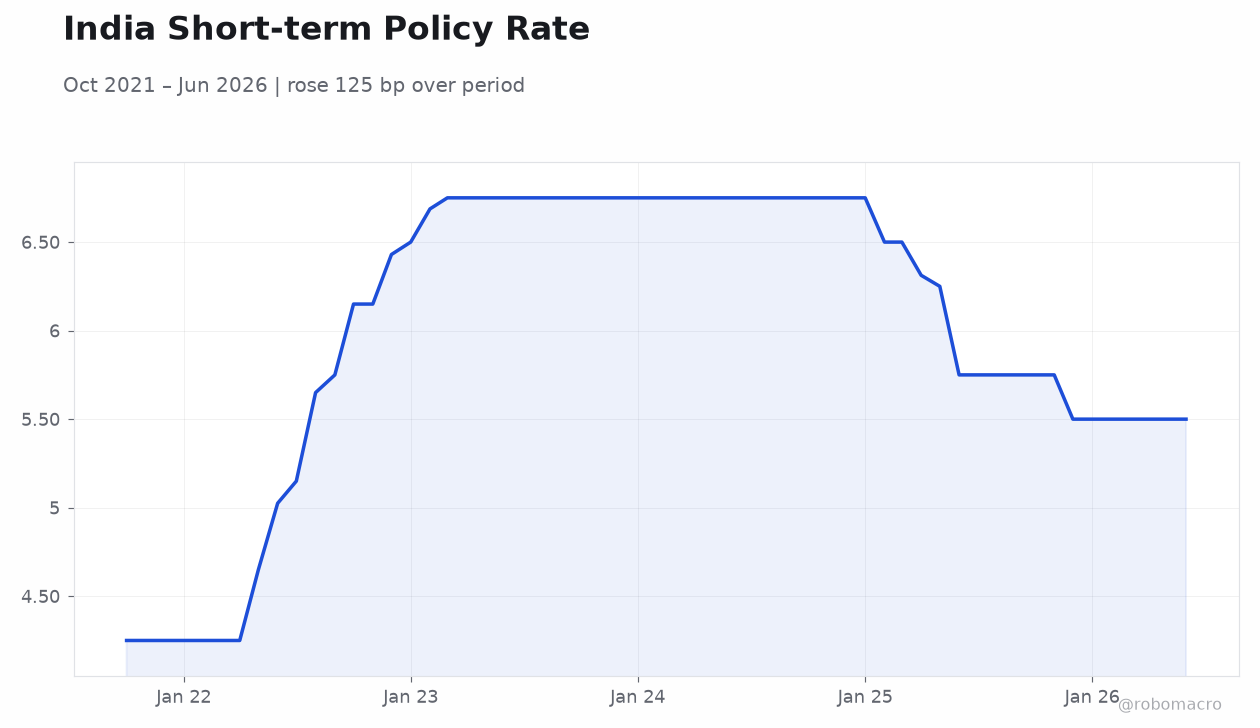
| India Short-term Rate | 5.50% | +0.00% |
| India Long-term Rate | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Inflation Rate Year-over-Year | 4.45 | 4.80 | 4.82 |
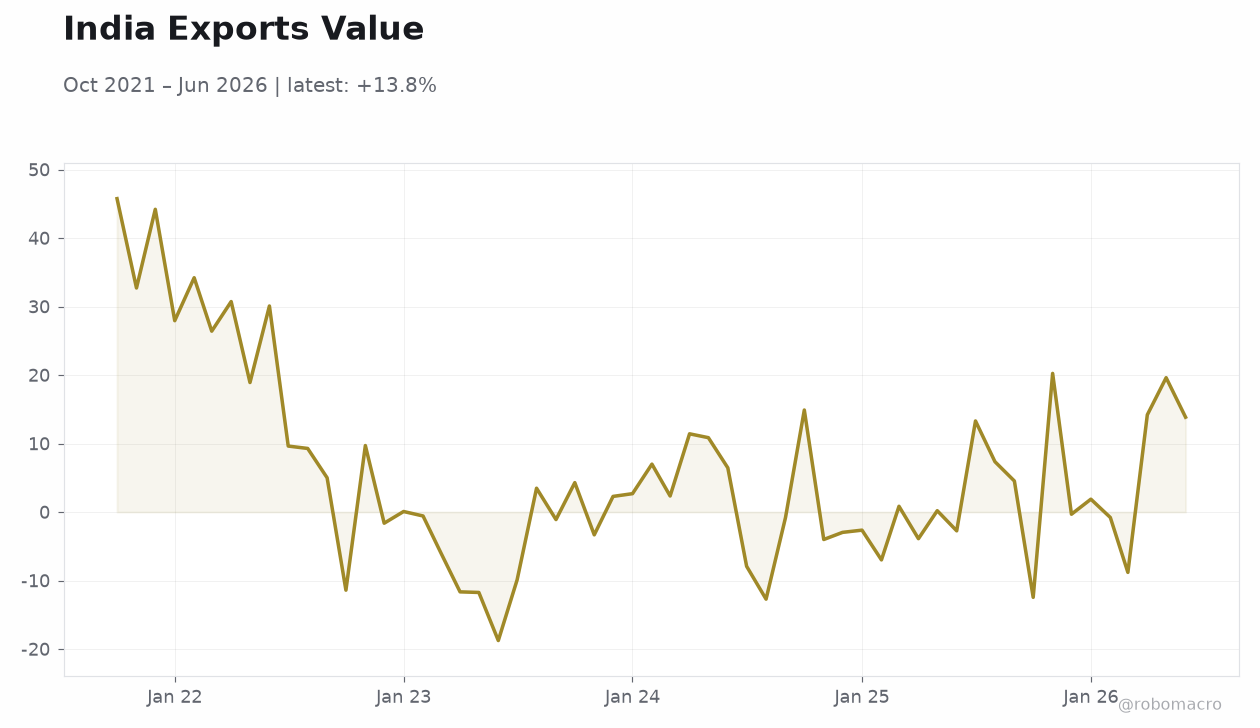 India Exports Value | Type: macro_line | Exports (USD mn): 13.85 (2026-06-01) | Range: -18.76–45.75 | Trend(5pt): 45.75,-1.63,6.995,-3.89,13.85
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- August CPI rises to 4.82% YoY, exceeding consensus and prior print
- Nifty falls 0.34% while rupee strengthens 0.69% against USD
- India ranks as fourth-largest forex holder amid tokenized bond launch
Yesterday's Recap
India’s August inflation rate printed at 4.82% YoY, above the 4.80% consensus and the prior 4.45% reading. The modest overshoot narrows the window for near-term RBI easing. Nifty 50 closed at 23,398.10, down 0.34%, while Sensex ended at 74,781.76, off 0.16%.
Reliance Industries declined 1.30% to 1,257.50 and HDFC Bank gained 2.08% to 708.25. Brent crude rose 2.22% to 106.93, supporting the case for persistent price pressures. USD/INR fell to 95.03, reflecting a 0.69% appreciation of the rupee, while EUR/INR dropped 2.98% to 107.44.
Gold declined 1.91% to 4,324.70 and Bitcoin rose 1.53% to 78,010.78. India’s short-term rate remained at 5.50% with no change in the policy corridor. The inflation beat was cited in market commentary as reducing the likelihood of near-term easing.
The Day Ahead
No major economic releases or RBI communications are scheduled for 14 September. Markets will focus on follow-through from the inflation print and external drivers such as US Treasury yields. Oil prices and Fed policy signals are expected to influence rupee trading ranges.
Equity investors will monitor sectoral rotation after mixed moves in energy and banking names. The absence of domestic data leaves global risk sentiment as the dominant driver for INR and Nifty direction. Participants await any updates on CBDC rollout or tokenized bond settlement volumes.
Attention will also stay on how the 123.04% US anti-dumping margin on Indian solar exports affects exporter margins and broader trade sentiment.
Other Economic Notes
India’s foreign-exchange reserves now rank fourth globally, providing a buffer against external shocks. Finance Minister Sitharaman called on the RBI to sharpen the digital-rupee platform’s capabilities during the Global Fintech Fest. Tokenized government bonds settled via CBDC were launched, marking a concrete step toward programmable money markets.
The US Commerce Department imposed a 123.04% anti-dumping margin on Indian solar exports, raising costs for domestic manufacturers. These developments underscore India’s push into digital finance while highlighting trade vulnerabilities in green-energy supply chains. CBDC outreach across Asia continues in parallel with the tokenized-bond pilot.