India Macro Daily(Beta Mode)
Hotter CPI Keeps RBI Hawkish, Rupee Slides
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| Nifty 50 | 23,398.10 | -0.34% |
| Sensex | 74,781.76 | -0.16% |
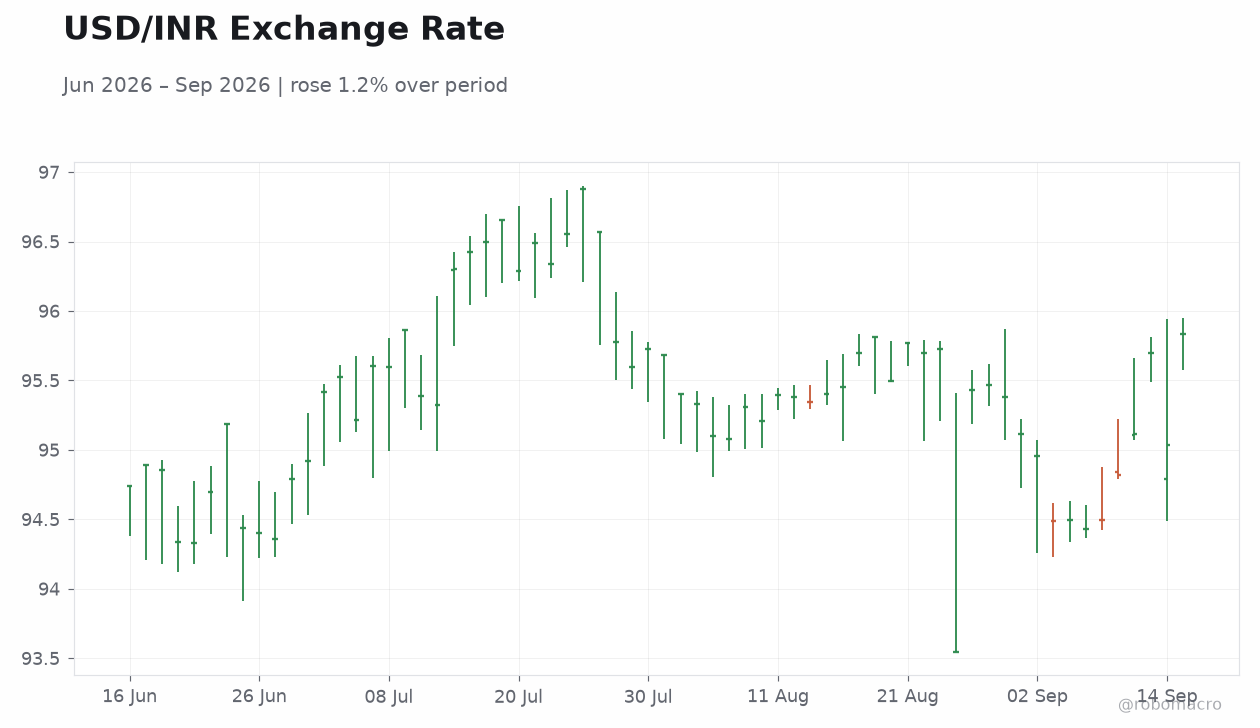
| USD/INR | 95.84 | +0.84% |
| EUR/INR | 110.29 | +2.66% |
| Reliance | 1,235.30 | -1.77% |
| HDFC Bank | 716.55 | +1.17% |
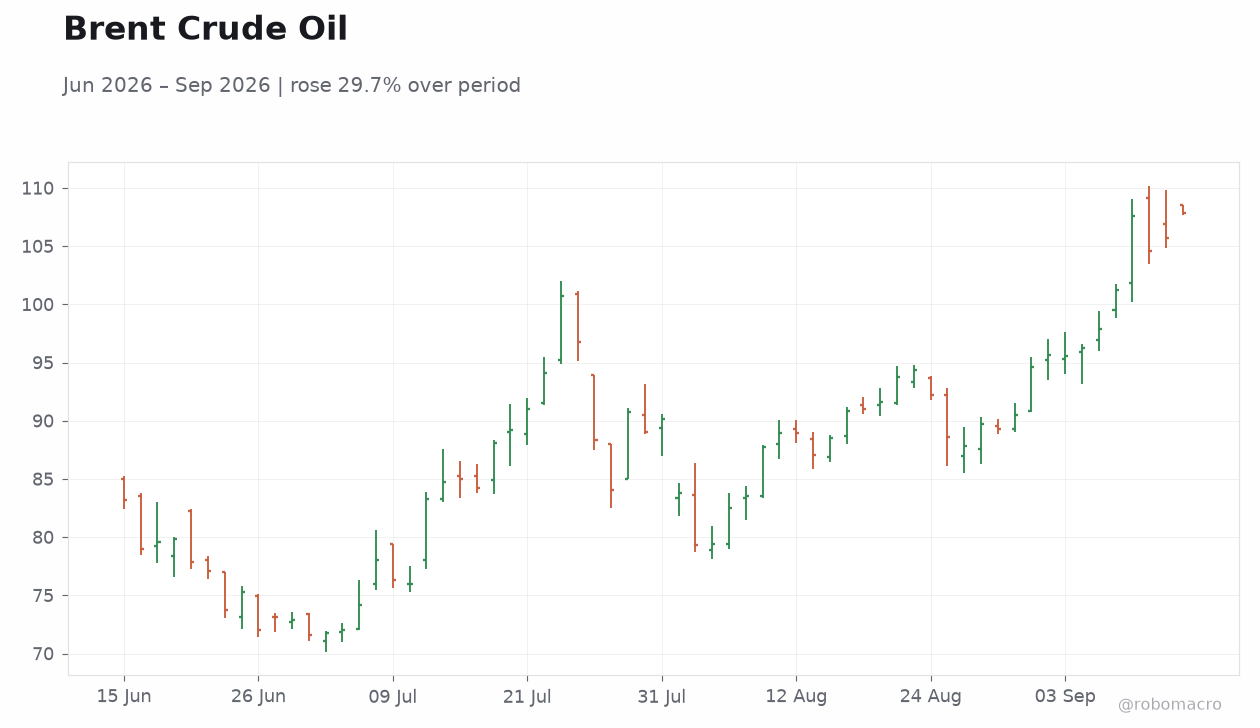
| Brent Crude | 107.77 | +1.98% |
| Gold | 4,325.70 | -0.60% |
| Bitcoin | 75,808.48 | -3.01% |
| India 2Y Govt Yield | - | - |
| India 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Inflation Rate Year-over-Year | 4.45 | 4.80 | 4.82 |
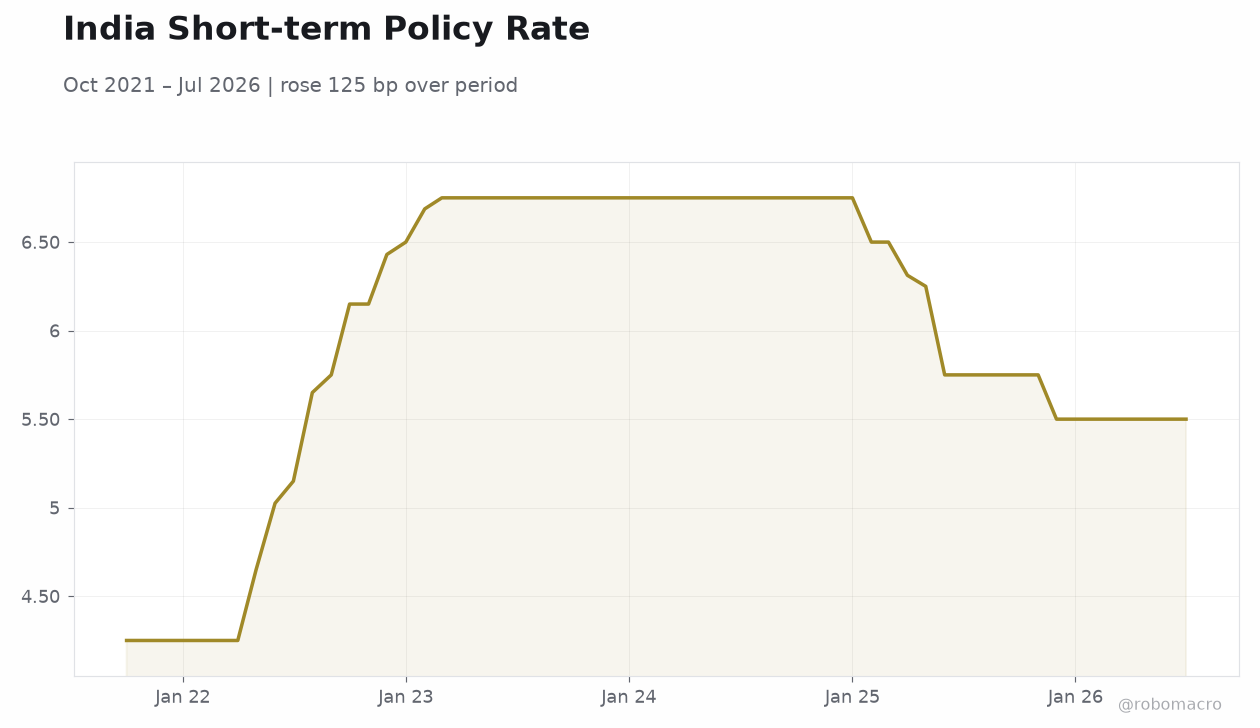 India Short-term Policy Rate | Type: macro_line | Policy Rate %: 5.5 (2026-07-01) | Range: 4.25–6.75 | Trend(5pt): 4.25,6.43,6.75,6.312,5.5
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- India inflation rose to 4.82% YoY, above consensus and prior print, reinforcing RBI hawkishness.
- Nifty fell 0.34% and Sensex declined 0.16% as Brent crude climbed 1.98% to 107.77.
- USD/INR rose 0.84% to 95.84 amid higher US yields and oil-price pressure.
Yesterday's Recap
India’s inflation rate printed at 4.82% YoY on 14 September, exceeding the 4.8% consensus and the previous 4.45% reading. The hotter outcome added to bond-yield volatility and weighed on the rupee. Nifty 50 closed at 23,398.10, down 0.34%, while Sensex ended at 74,781.76, off 0.16%.
Reliance Industries dropped 1.77% to 1,235.30, whereas HDFC Bank gained 1.17% to 716.55. USD/INR advanced 0.84% to 95.84 and EUR/INR jumped 2.66% to 110.29. July’s current-account deficit widened to $7 billion even as the balance-of-payments surplus expanded to $20.8 billion.
Telangana remained the highest-inflation state for the eighth straight month. No closing levels were available for India 2Y or 10Y G-Sec yields.
The Day Ahead
No major Indian data releases or RBI events are scheduled for 15 September. Markets will monitor US Treasury yield movements and Brent crude prices for further rupee direction. Traders also await any follow-up comments from RBI officials on liquidity operations.
Equity flows and FII positioning may influence Nifty and Sensex intraday swings. Elevated oil prices could prompt domestic fuel price adjustments and keep RBI policy on a tighter bias.
Other Economic Notes
July’s wider current-account deficit and larger balance-of-payments surplus highlight India’s external resilience despite rising oil costs. Analysts note that high interest-to-revenue ratios still require gradual public-debt reduction to preserve investor confidence. Cash usage remains robust even as digital payments expand, reflecting structural preferences in parts of the economy.
NSE’s upcoming listing is expected to place it among India’s top-15 companies by market value. Recent dollar inflows have created a roughly Rs 15 trillion liquidity-management task for policymakers. Industry executives expect LNG imports in China and India to rebound once the Middle East supply crunch eases.