India Macro Daily(Beta Mode)
Hotter CPI, Rupee Weakens Ahead of Fed
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| Nifty 50 | 23,118.60 | -1.19% |
| Sensex | 74,003.82 | -1.04% |
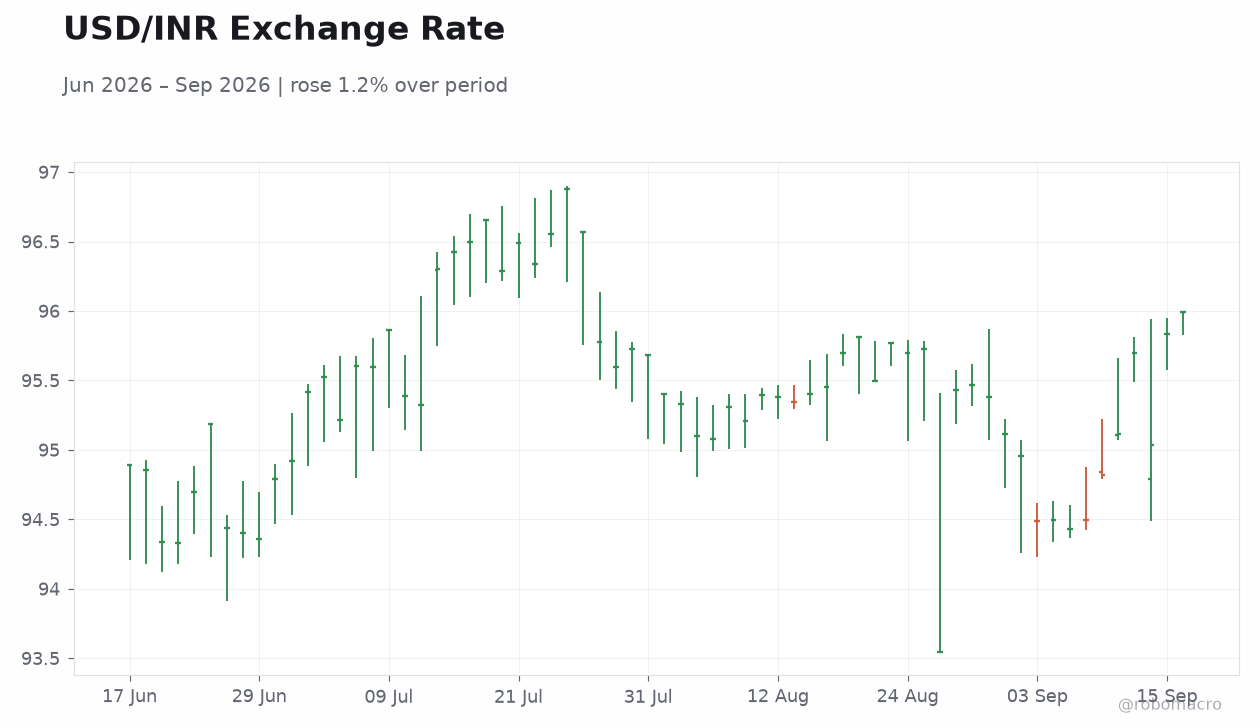
| USD/INR | 95.99 | +0.16% |
| EUR/INR | 110.64 | +0.31% |
| Reliance | 1,240.00 | +0.38% |
| HDFC Bank | 721.50 | +0.69% |
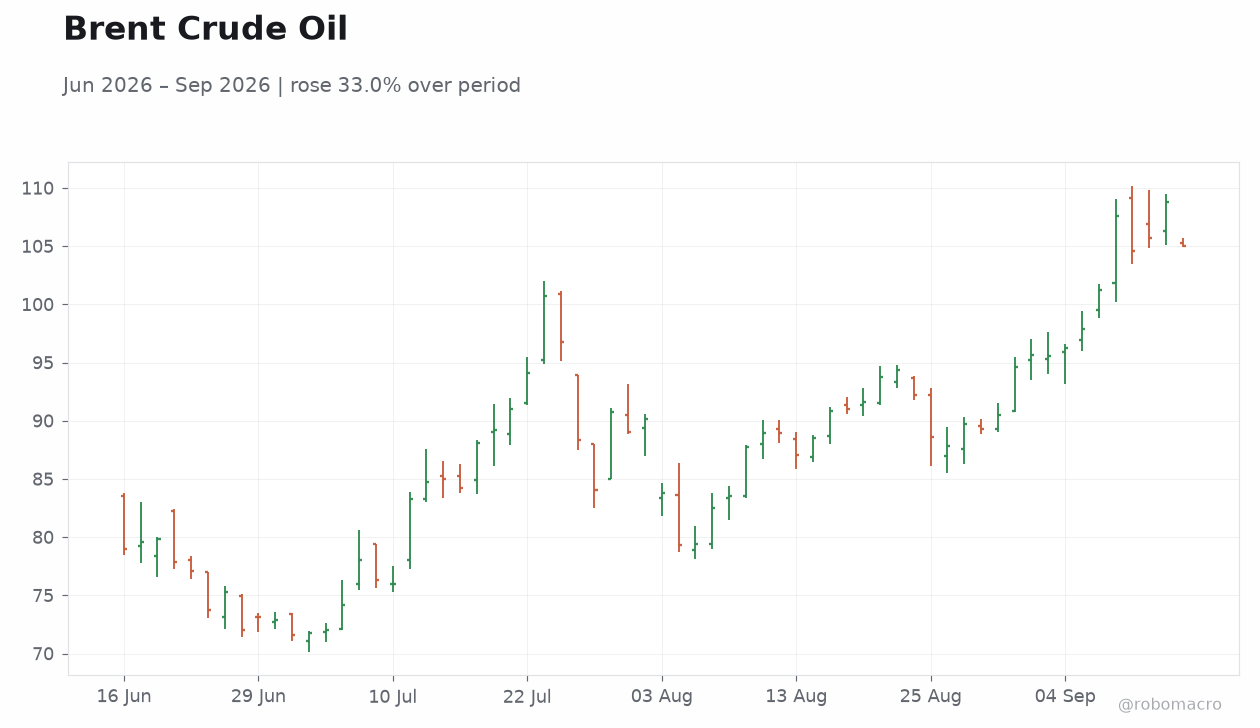
| Brent Crude | 105.13 | -3.33% |
| Gold | 4,324.10 | -0.20% |
| Bitcoin | 76,318.85 | +0.93% |
| India 2Y Govt Yield | - | - |
| India 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Inflation Rate Year-over-Year | 4.45 | 4.80 | 4.82 |
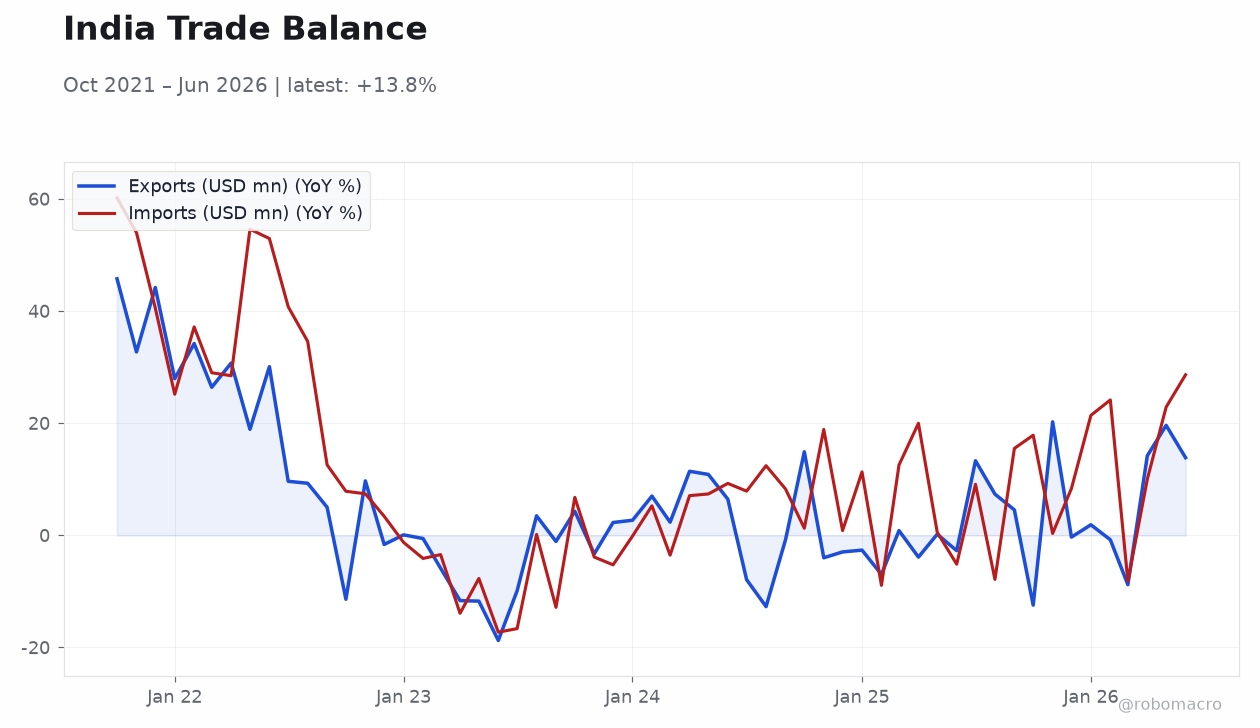
| Trade Balance | -31,980m | - | -26,860m |
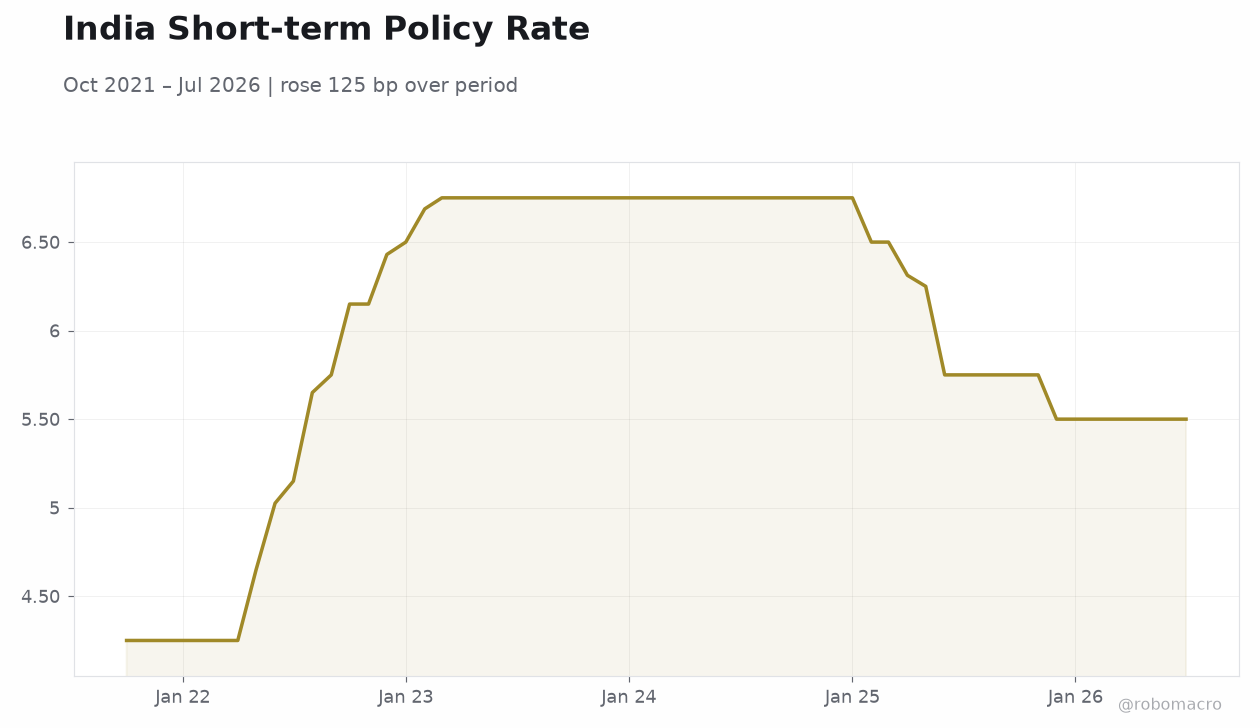 India Short-term Policy Rate | Type: macro_line | %: 5.5 (2026-07-01) | Range: 4.25–6.75 | Trend(5pt): 4.25,6.43,6.75,6.312,5.5
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- India CPI rose 4.82% YoY, above consensus, while trade deficit narrowed to $26.86 billion.
- Nifty fell 1.19% and rupee slipped to 95.99 as US yields climbed before Fed decision.
- Cabinet raised EPF wage ceiling to 25,000 rupees; CAD widened to $7 billion in July.
Yesterday's Recap
India’s inflation print came in at 4.82% YoY, exceeding the 4.8% consensus and prior 4.45% reading. The trade balance improved to minus $26.86 billion from minus $31.98 billion. July current-account deficit widened to $7 billion while the balance-of-payments surplus jumped to $20.8 billion.
Equity markets closed lower, with Nifty 50 at 23,118.60 and Sensex at 74,003.82. The rupee eased 0.16% to 95.99, remaining near a seven-week low as the RBI capped losses around 95.80. Brent crude declined 3.33% to $105.13, easing some imported inflation pressure.
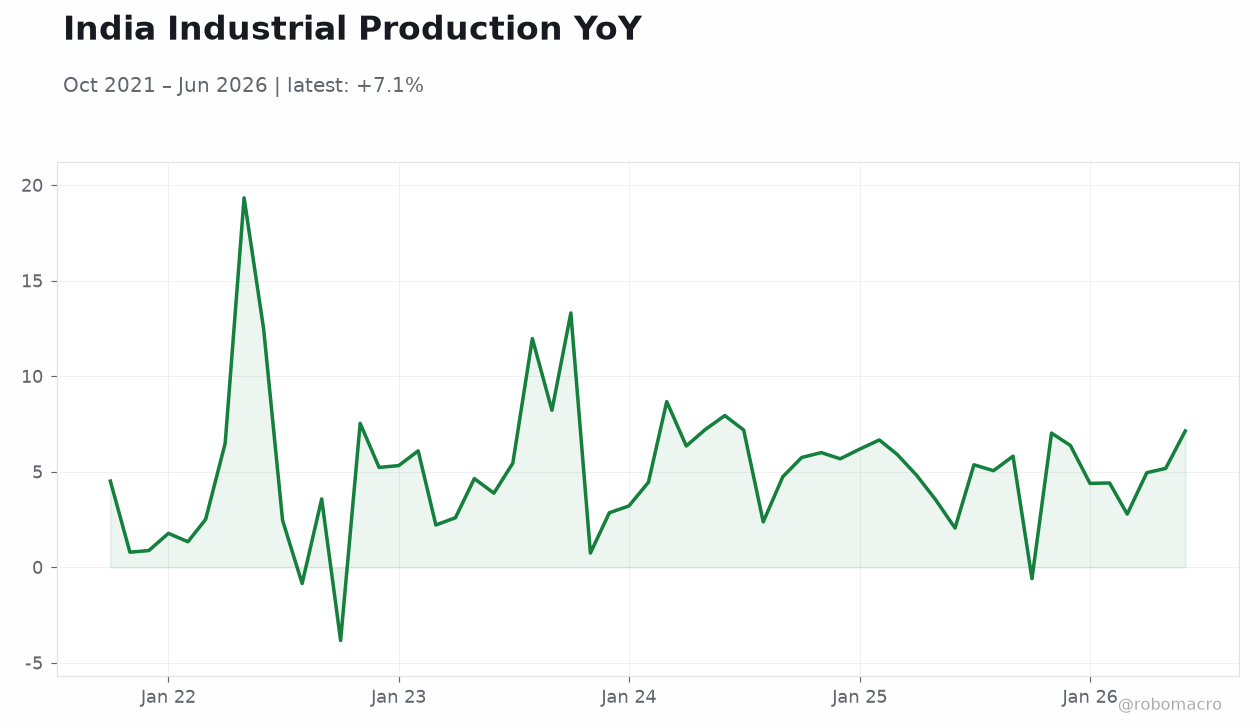
Market commentary noted trade data signal an economy running hot. Reliance Industries ended at 1,240.00 (+0.38%) and HDFC Bank at 721.50 (+0.69%). Gold finished at 4,324.10 (–0.20%) while Bitcoin rose to 76,318.85 (+0.93%).
EUR/INR gained 0.31% to 110.64. No RBI speeches or minutes were released.
The Day Ahead
No Indian data releases or RBI events are scheduled. Attention shifts to the US Fed policy decision and any signals on future rate paths. Traders will watch US Treasury yields and oil prices for spillovers into the rupee and local bonds.
Equity flows may stay cautious until global rate clarity emerges. The New Zealand-India FTA is expected to take effect in the second half of October, offering duty-free access for over half of New Zealand exports. Market participants will monitor any follow-through from yesterday’s hotter inflation reading and narrowing trade gap for clues on domestic demand momentum.
Other Economic Notes
India’s US exports recorded their fastest growth in nine months amid shifting tariffs. The cabinet approved raising the EPF wage upper limit to 25,000 rupees, expanding formal savings coverage. LNG demand in China and India is projected to rebound once Middle East supply constraints ease and prices moderate.
Trade figures showing resilient domestic demand have prompted questions on whether the RBI is behind the curve. ↓ p.2