India Macro Daily(Beta Mode)
Inflation Tops Forecast, Trade Gap Narrows
Market Snapshot
| Asset | Level | Change |
|---|---|---|
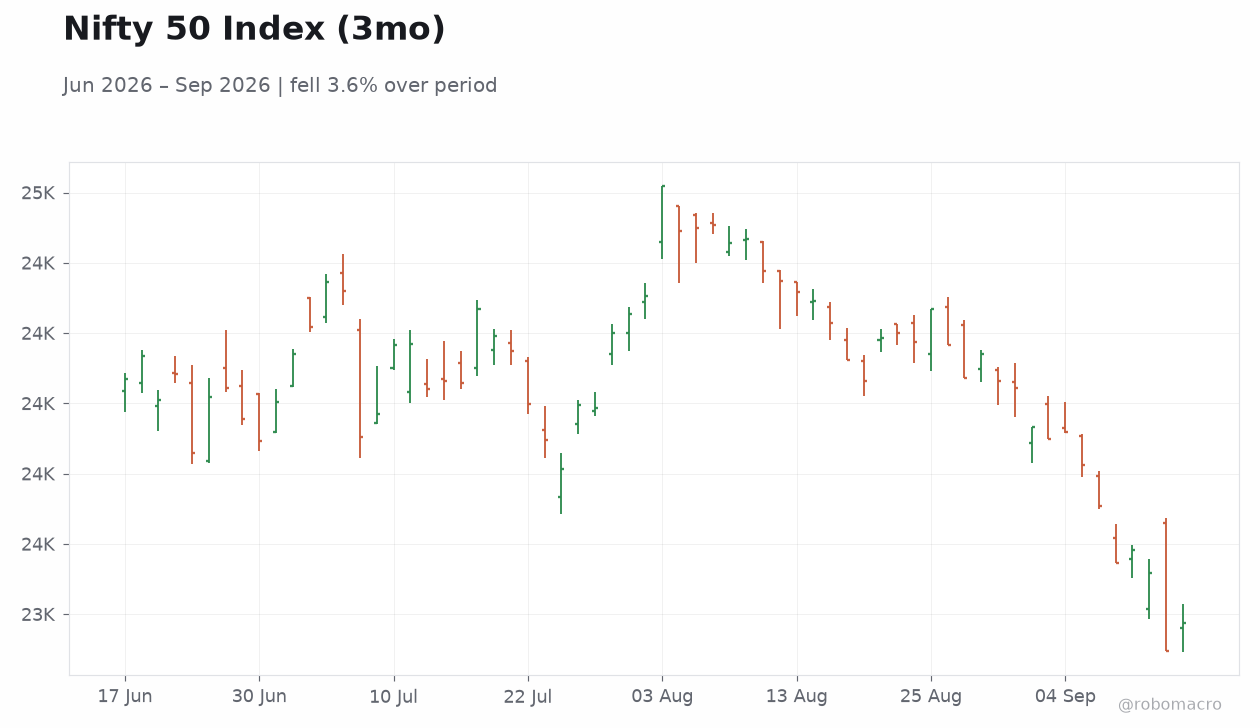
| Nifty 50 | 23,217.60 | +0.43% |
| Sensex | 74,336.45 | +0.45% |
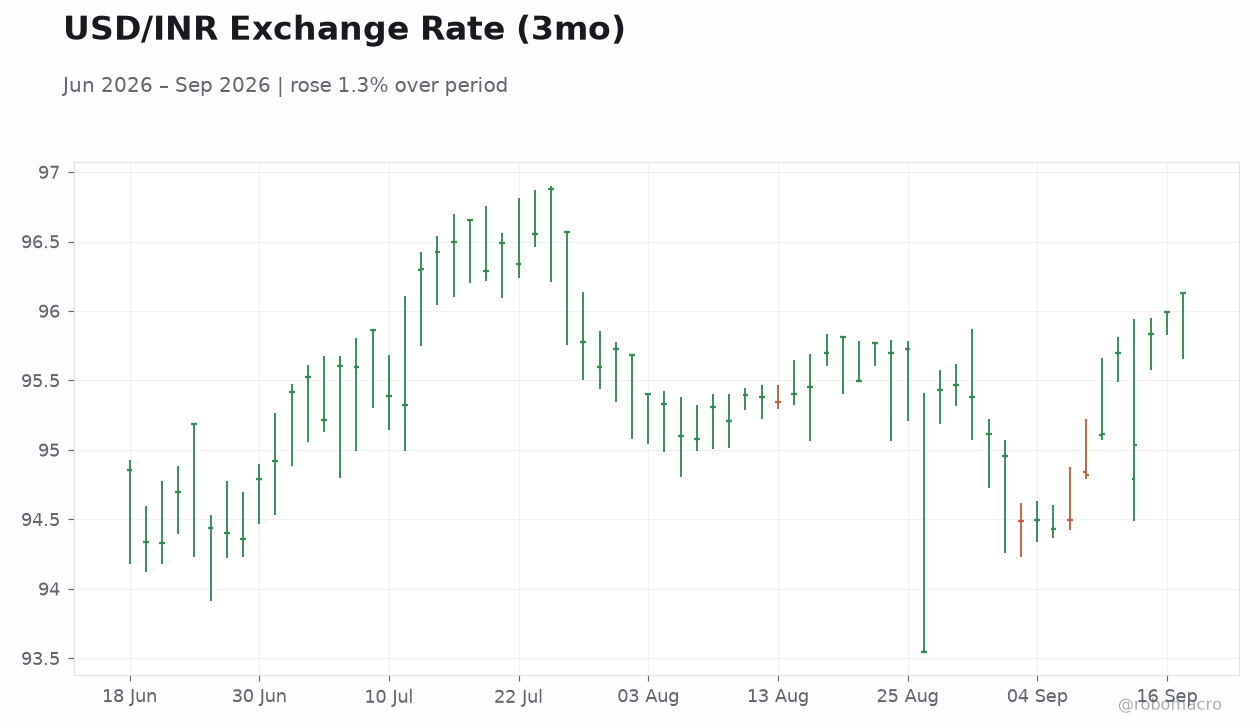
| USD/INR | 96.13 | +0.15% |
| EUR/INR | 109.99 | -0.59% |
| Reliance | 1,243.90 | +0.31% |
| HDFC Bank | 713.00 | -1.18% |
| Brent Crude | 103.81 | -1.91% |
| Gold | 4,392.20 | +0.11% |
| Bitcoin | 76,322.92 | +0.23% |
| India 2Y Govt Yield | - | - |
| India 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Inflation Rate Year-over-Year | 4.45 | 4.80 | 4.82 |
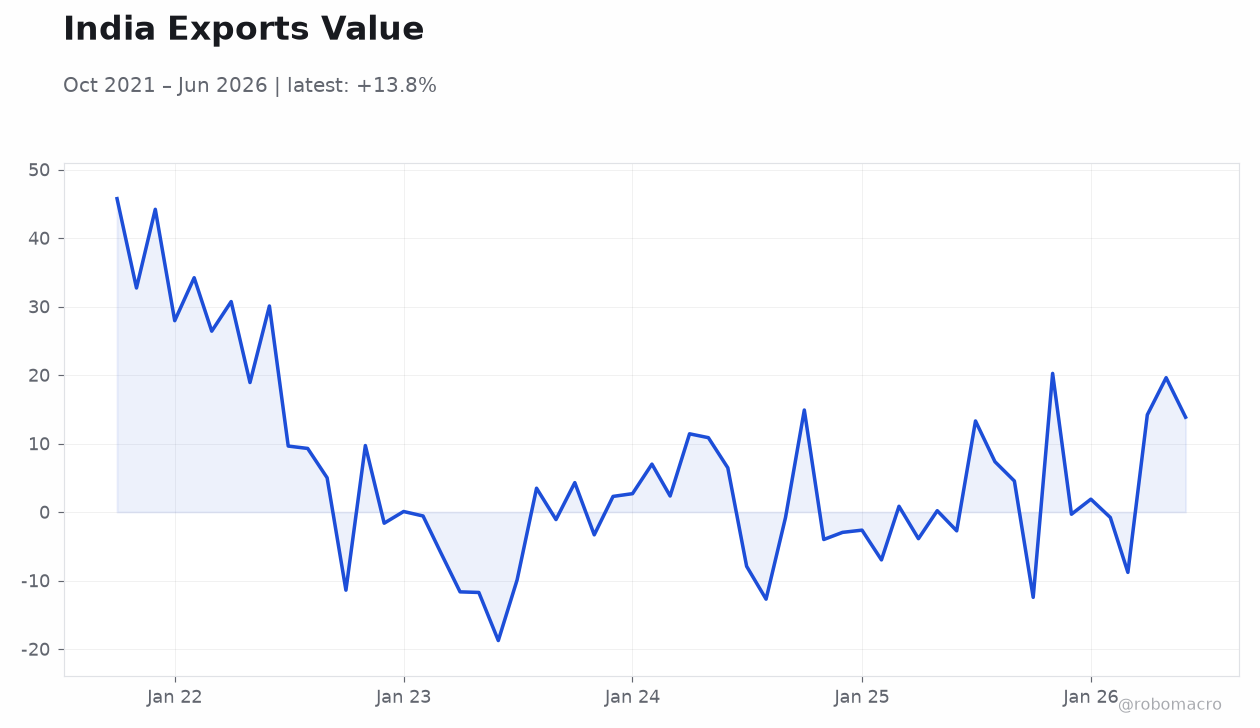
| Trade Balance | -31,980m | - | -26,860m |
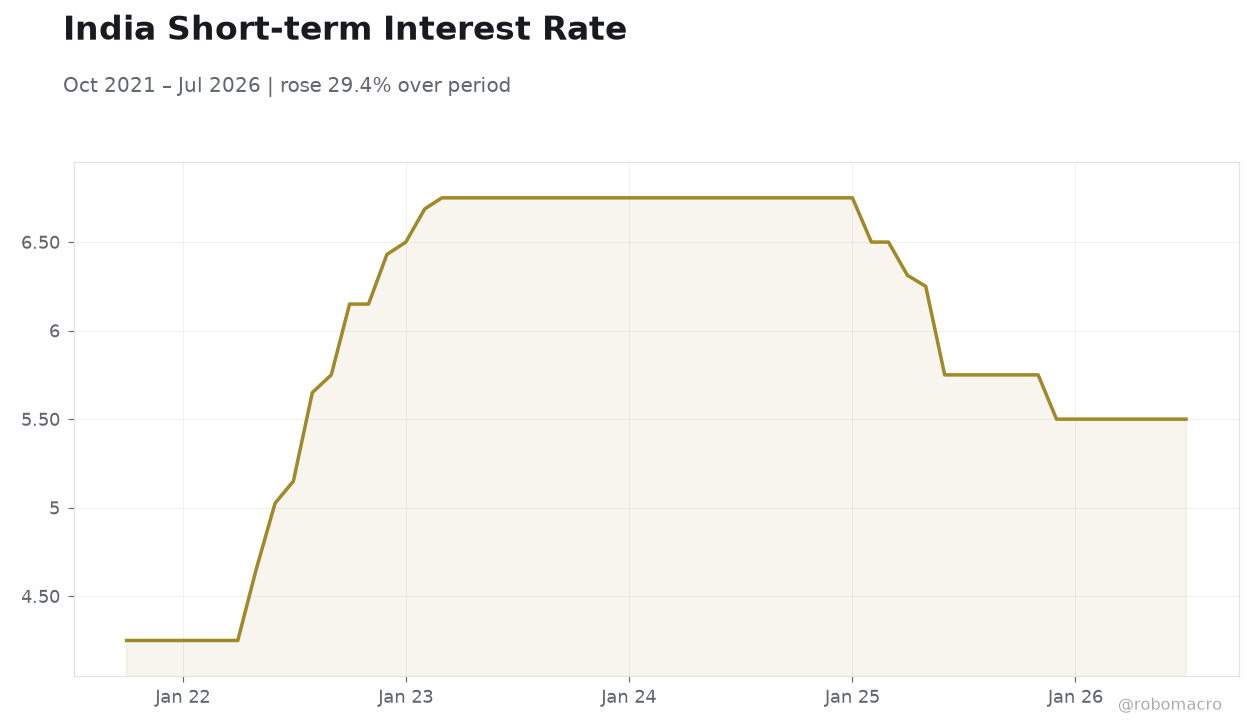 India Short-term Interest Rate | Type: macro_line | Policy Rate %: 5.5 (2026-07-01) | Range: 4.25–6.75 | Trend(5pt): 4.25,6.43,6.75,6.312,5.5
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Inflation prints at 4.82% YoY, above 4.8% consensus
- Trade deficit narrows to $26.86 billion from $31.98 billion
- Nifty rises 0.43% to 23,217.60 as rupee edges to 96.13
Yesterday's Recap
India's inflation rate rose to 4.82% year-over-year, exceeding the 4.8% consensus and prior 4.45% print. The trade balance improved to a $26.86 billion deficit from $31.98 billion previously. Equity benchmarks advanced, with Nifty 50 gaining 0.43% to 23,217.60 and Sensex adding 0.45% to 74,336.45.
The rupee closed at 96.13 against the dollar after a 0.15% move, supported by reported RBI dollar sales. Brent crude fell 1.91% to $103.81, easing pressure on the import bill. Gold inched up 0.11% to 4,392.20 while HDFC Bank shares declined 1.18%.
RBI liquidity absorption operations coincided with these moves, keeping interbank rates steady.
The Day Ahead
No domestic data releases are scheduled. Markets will monitor the US Fed outcome for signals on further rate hikes and potential FPI outflow risks. RBI liquidity management remains in focus as the central bank continues draining excess cash from banks.
Implementation of the India-New Zealand FTA is expected in October, offering duty-free access for over half of New Zealand exports. Petroleum export trends will stay relevant given rising margins and new market access. Global semiconductor supply-chain shifts could draw attention to Prime Minister Modi's pitch for India as a chipmaking hub.
Other Economic Notes
Prime Minister Modi urged technology firms to invest in India's semiconductor sector to build a global manufacturing hub. UPI's shift away from free transactions reflects broader efforts to expand fiscal room while testing bank resilience to future shocks. Petroleum exports have risen on stronger margins, higher volumes and diversified destinations.
India's increased reliance on Russian oil imports faces potential 100% US tariffs under new sanctions legislation. Services export growth and FTA progress with New Zealand provide positive offsets to external sector pressures.
Global Macro News
The US Fed's rate decision looms over India, raising fresh risks of foreign portfolio outflows and higher borrowing costs. Legislation targeting buyers of Russian energy could impose steep tariffs on Indian crude imports, complicating energy security. ↓ p.2