India Macro Daily(Beta Mode)
Rupee Stabilises on RBI Support, Oil Retreats
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| Nifty 50 | 23,346.40 | +0.33% |
| Sensex | 74,294.96 | -0.03% |
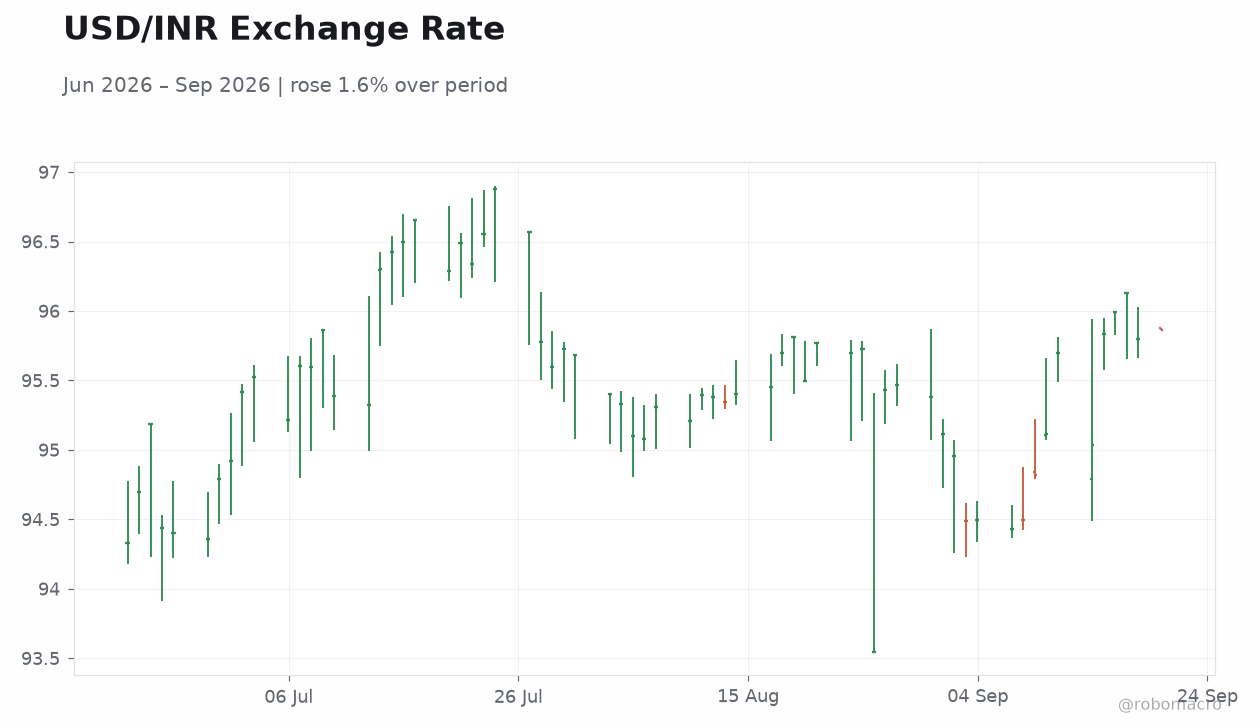
| USD/INR | 95.86 | +0.07% |
| EUR/INR | 110.12 | +0.08% |
| Reliance | 1,226.40 | -1.41% |
| HDFC Bank | 731.00 | +2.52% |
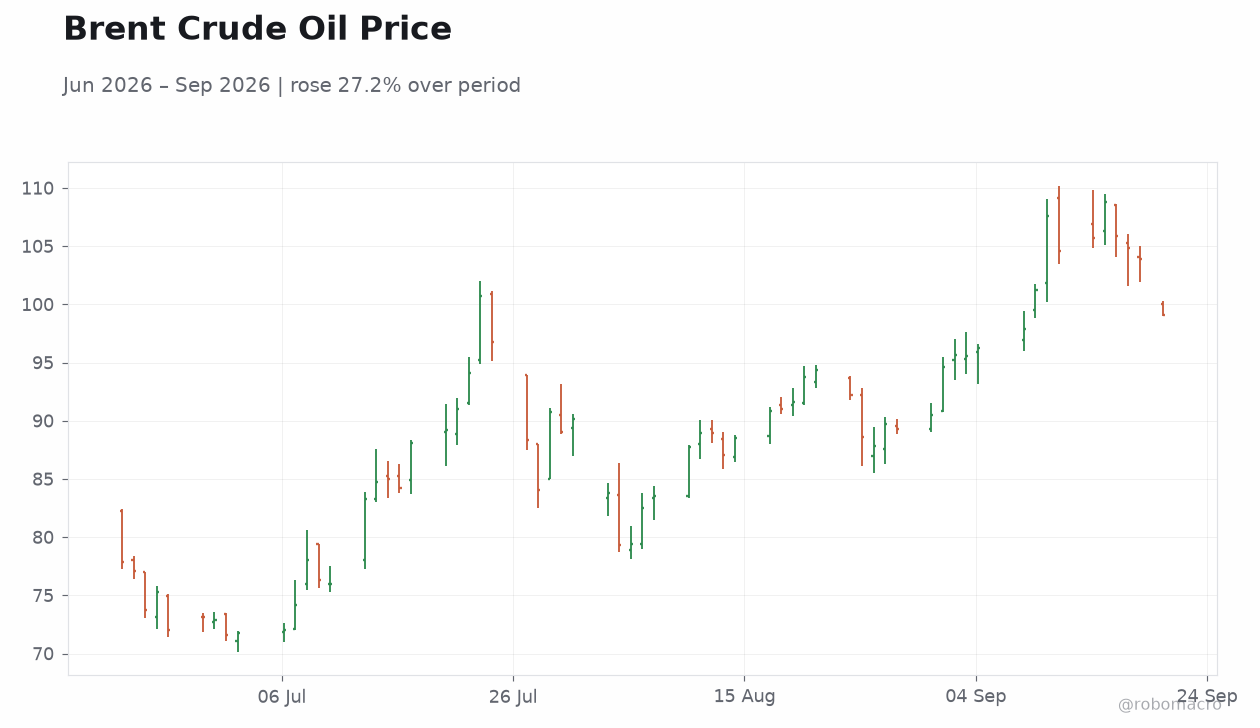
| Brent Crude | 99.06 | -4.63% |
| Gold | 4,399.40 | -0.58% |
| Bitcoin | 81,722.37 | +0.60% |
| India 2Y Govt Yield | - | - |
| India 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
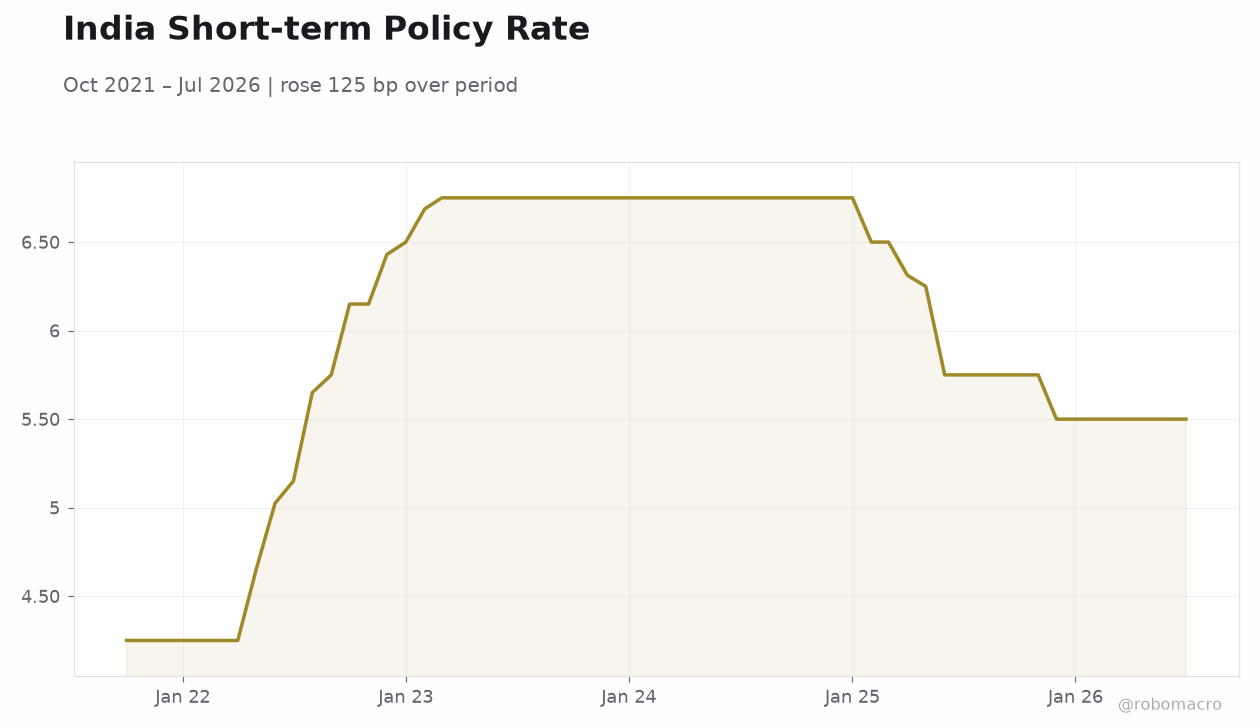 India Short-term Policy Rate | Type: macro_line | Policy Rate %: 5.5 (2026-07-01) | Range: 4.25–6.75 | Trend(5pt): 4.25,6.43,6.75,6.312,5.5
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Wednesday (2026-09-23) | |||
| HSBC Composite PMI Flash | 54.30 | - | 01:00 |
| HSBC Manufacturing PMI Flash | 52.80 | - | 01:00 |
| HSBC Services PMI Flash | 54.10 | - | 01:00 |
- Nifty rose 0.33% while Sensex edged 0.03% lower as Brent crude fell 4.63% to 99.06, easing import pressure.
- Forex reserves dropped $4.9 billion yet stayed at record levels; RBI absorbed Rs 2.23 lakh crore via VRRR auction.
- Software services exports climbed 8.2% to $221.4 billion in FY26.
Yesterday's Recap
Equity markets closed mixed on 19 September with Nifty 50 at 23,346.40 and Sensex at 74,294.96. Brent crude’s sharp decline supported the rupee, which snapped its losing streak and rose 0.07% to 95.86 against the dollar. RBI conducted a variable rate reverse repo auction that withdrew Rs 2.23 lakh crore of liquidity from the banking system.
Forex reserves declined $4.9 billion but remained near historic highs despite ongoing currency pressure from energy imports. Software services exports expanded 8.2% year-on-year to $221.4 billion. Reliance Industries fell 1.41% while HDFC Bank gained 2.52%.
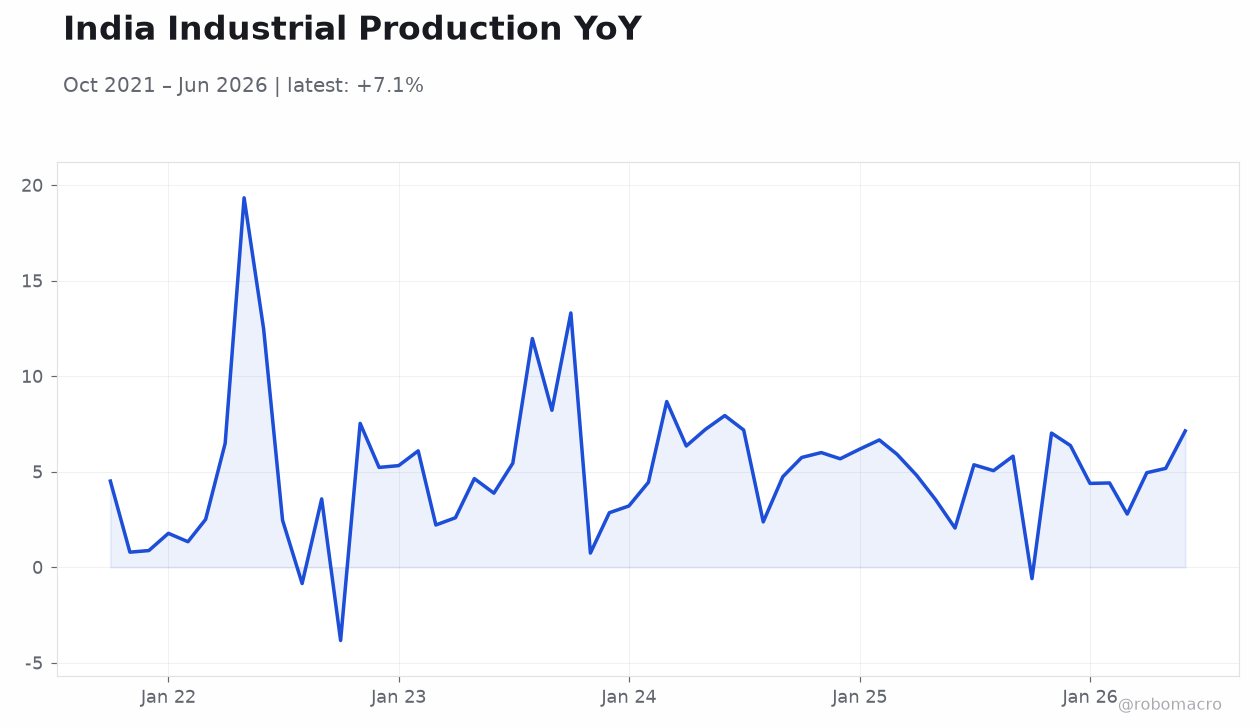
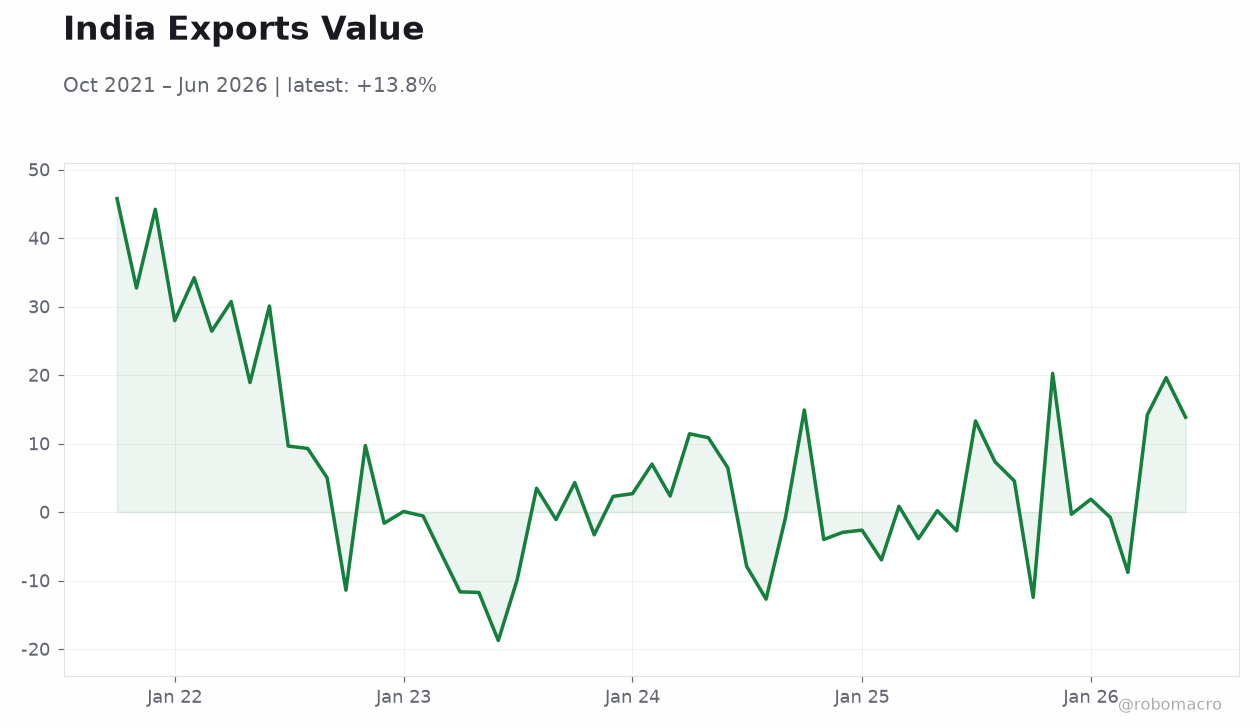
India’s deputy high commissioner urged Bangladesh to remove tariff and non-tariff barriers to deepen bilateral trade and investment flows. A higher gross domestic savings rate remains essential to sustain 7-8% GDP growth through continued infrastructure and manufacturing investment. A cheaper rupee has boosted high-tech exports but delivered limited gains for labour-intensive mid-tech sectors.
The Day Ahead
No data releases are scheduled for 20 September. Attention turns to the HSBC PMI flash prints due 23 September for manufacturing, services and composite activity. These readings will provide the first September gauge of private-sector momentum and could influence near-term RBI policy expectations.
Markets will also monitor any updates on the government’s planned Rs 7.96 lakh crore H2 borrowing programme. Diaspora deposit inflows under the FCNR(B) scheme are being watched as a potential buffer for rupee stability amid energy price volatility. Equity and currency traders will track global oil moves for further relief on the current-account outlook.
Other Economic Notes
India’s forex reserves, though lower by $4.9 billion last week, continue to provide a substantial cushion against external shocks. Reports recommend an early RBI rate increase to anchor inflation expectations at the current 4.44% CPI level and support the currency. Strong software export growth to $221.4 billion underscores the resilience of services earnings despite rupee fluctuations.
Global oil prices retreated sharply, cutting Brent to 99.06 and reducing immediate pressure on India’s import bill. The 2008 financial crisis legacy continues to shape Indian policy caution, with regulators maintaining elevated buffers.