India Macro Daily(Beta Mode)
RBI Swaps Bolster Rupee as Oil Retreats
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| Nifty 50 | 23,346.40 | +0.33% |
| Sensex | 74,294.96 | -0.03% |
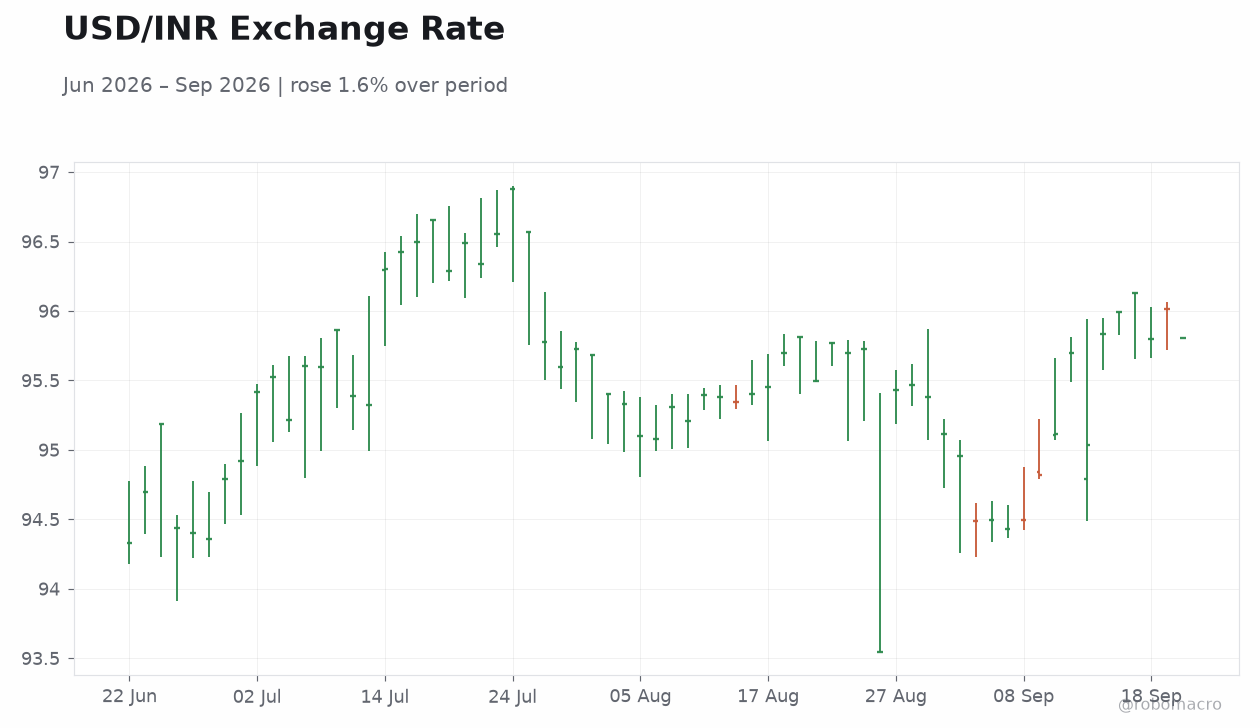
| USD/INR | 95.81 | -0.22% |
| EUR/INR | 109.86 | -0.16% |
| Reliance | 1,226.40 | -1.41% |
| HDFC Bank | 731.00 | +2.52% |
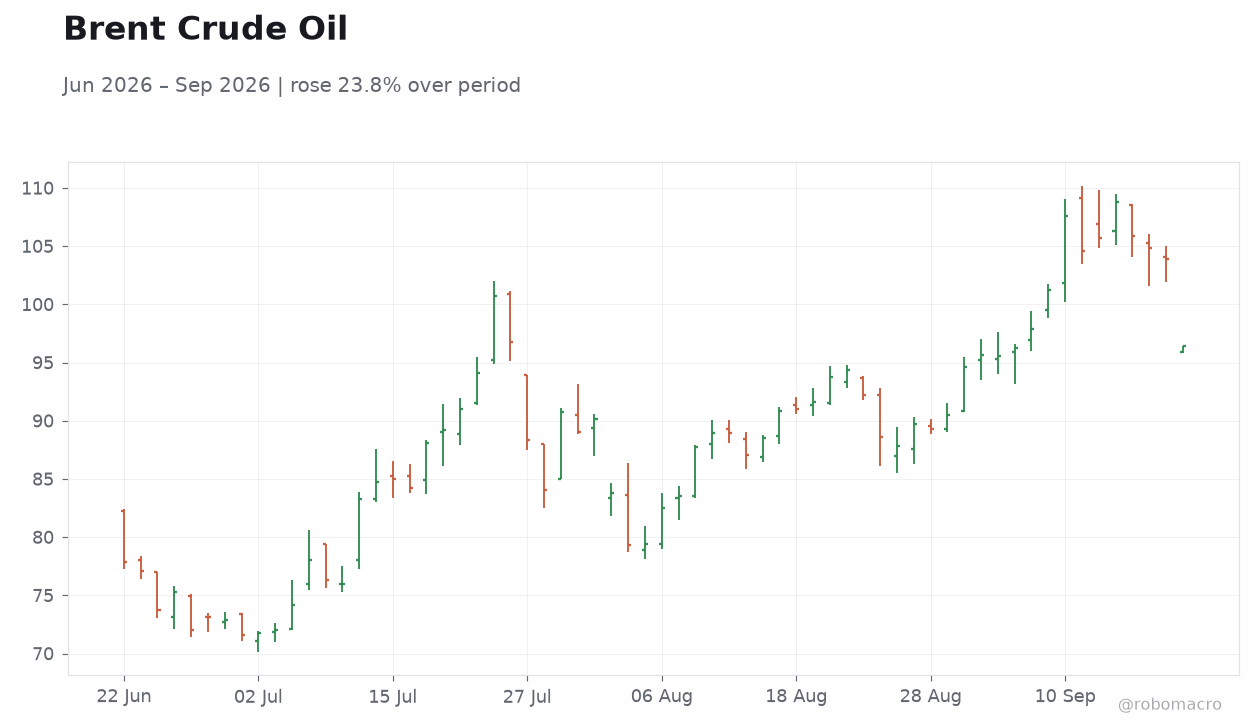
| Brent Crude | 96.42 | -7.17% |
| Gold | 4,399.10 | -0.58% |
| Bitcoin | 86,374.95 | +6.45% |
| India 2Y Govt Yield | - | - |
| India 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
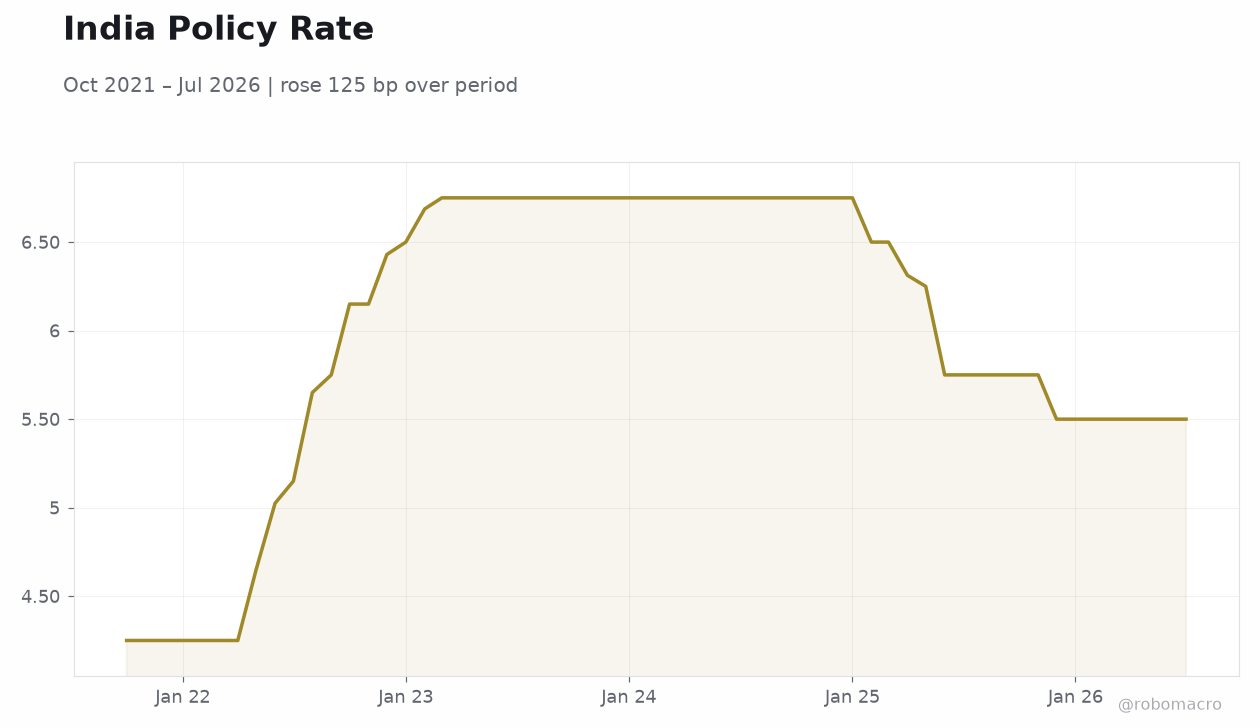 India Policy Rate | Type: macro_line | Percent: 5.5 (2026-07-01) | Range: 4.25–6.75 | Trend(5pt): 4.25,6.43,6.75,6.312,5.5
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Wednesday (2026-09-23) | |||
| HSBC Composite PMI Flash | 54.30 | - | 21:00 |
| HSBC Manufacturing PMI Flash | 52.80 | - | 21:00 |
| HSBC Services PMI Flash | 54.10 | - | 21:00 |
- Rupee snaps losing streak on record RBI forex swaps and Brent drop
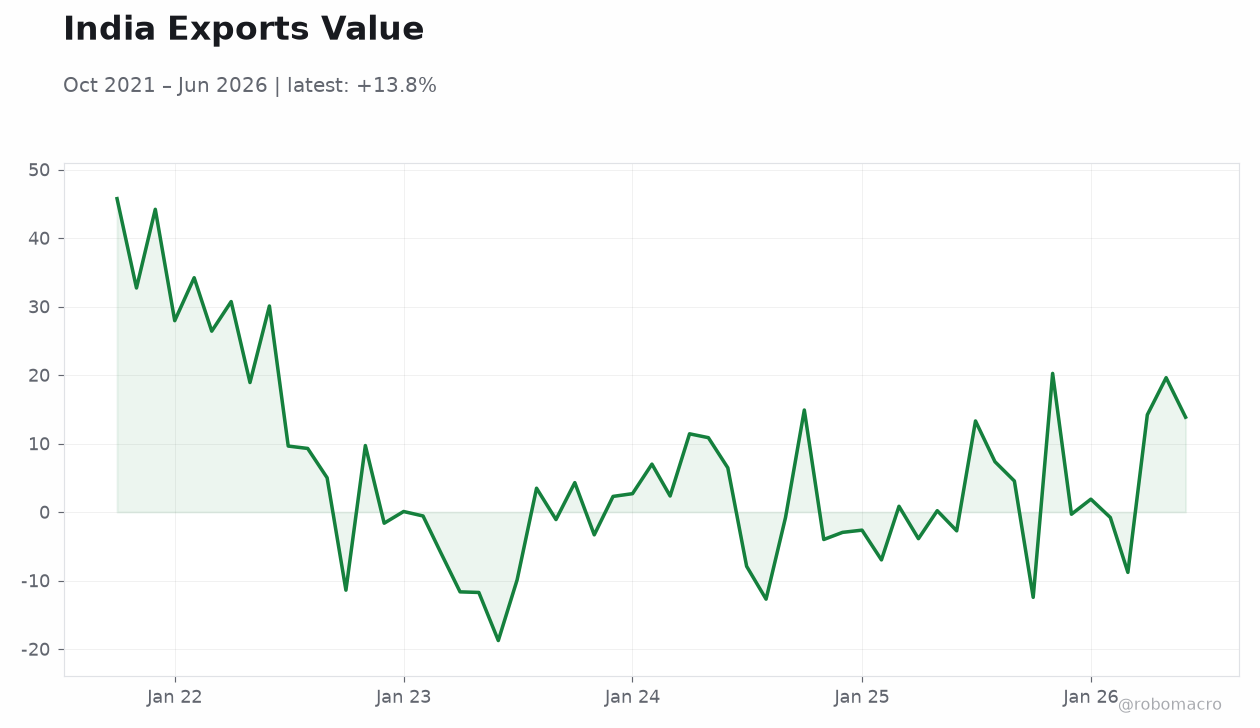
- Nifty rises 0.33% while software exports climb 8.2% to $221.4 bn
- HSBC PMI flashes due tomorrow offer first Q3 activity read
Yesterday's Recap
Equity markets closed mixed on 20 September. Nifty 50 advanced 0.33% to 23,346.40 while Sensex eased 0.03% to 74,294.96. Reliance Industries fell 1.41% to 1,226.40 and HDFC Bank gained 2.52% to 731.00.
The rupee strengthened 0.22% to 95.81 against the dollar as Brent crude plunged 7.17% to 96.42. Gold declined 0.58% to 4,399.10 and Bitcoin rose 6.45% to 86,374.95. No scheduled data releases occurred.
Forex reserves fell $4.9 billion yet the RBI’s swap window attracted a record $143.6 billion, mainly from FCNR-B deposits, helping stabilise the currency alongside the oil retreat.
The Day Ahead
Three HSBC PMI flash prints are scheduled for 21:00 on 22 September. The composite index last printed 54.3, manufacturing 52.8 and services 54.1. Markets will parse any early signals on third-quarter momentum in industry and services.
No other India-specific releases or policy events appear on the calendar. Traders will also monitor global oil and equity flows for any further impact on the rupee. The prints carry medium impact and are expected to set the tone ahead of October trade data.
Other Economic Notes
Software services exports expanded 8.2% to $221.4 billion in FY26, with the United States absorbing $120 billion or 54.1% of the total. A cheaper rupee has supported high-tech shipments more than labour-intensive mid-tech categories. India and New Zealand confirmed their free-trade agreement will take effect on 20 October, targeting a doubling of bilateral goods and services trade to ₹35,000 crore by 2030.
Separate diplomatic outreach seeks to lower tariff and non-tariff barriers with Bangladesh to deepen investment links. Sustaining 7-8% GDP growth will require a higher gross domestic savings rate to finance ongoing infrastructure needs.
Global Macro News
Brent’s sharp 7.17% decline eased pressure on India’s energy import bill and current-account balance. The 2008 financial crisis continues to shape Indian regulation, with tighter capital rules and stronger forex buffers now in place. Reports noted that one Indian-American vote in US tariff deliberations could amplify duties on Indian goods.
↓ p.2